
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Imdex (ASX:IMD) Shares Jumped, What Is Drawing Attention Now?
Recent commentary around Imdex (ASX:IMD) has focused on its free cash flow profile and suggestions of potential undervaluation. That perspective is now shaping how investors weigh the recent share price history.
Recent price action shows that Imdex is still volatile in the short term, with a 1 day share price gain of 6.13% following a weaker 90 day share price return that fell 8.86%. The 3 year total shareholder return of 123.15% points to earlier strong momentum that investors are now reassessing against the current free cash flow debate.
Compare Imdex's free cash flow story with other potential opportunities by scanning a hand picked set of 5 high quality undervalued stocks that share solid fundamentals and possible pricing gaps.
A sharp one-day jump following weaker one-year returns puts Imdex in an awkward spot for fresh capital. Does that recent move still leave enough potential upside to justify the risk on valuation grounds?
Most Popular Narrative: 28% Undervalued
The most followed narrative puts Imdex’s fair value at A$4.57 per share, compared with the last close at A$3.29. That gap is attracting attention from investors who focus on both cash flows and the mining tech story.
Strong industry demand, digital adoption, and expansion into new markets are associated with sustained revenue growth and increased market diversification. Continued innovation and a robust financial position are described as supporting margin expansion, earnings stability, and strategic growth initiatives.
See why 8 investors see Imdex as 28% undervalued.
Result: Fair Value of A$4.57 (UNDERVALUED)
Still, that upbeat Imdex story can unravel quickly if exploration spending tightens, or if rising regulatory and compliance costs squeeze drilling budgets harder.
Find out about the key risks to this Imdex narrative.
Another View On Imdex’s Valuation
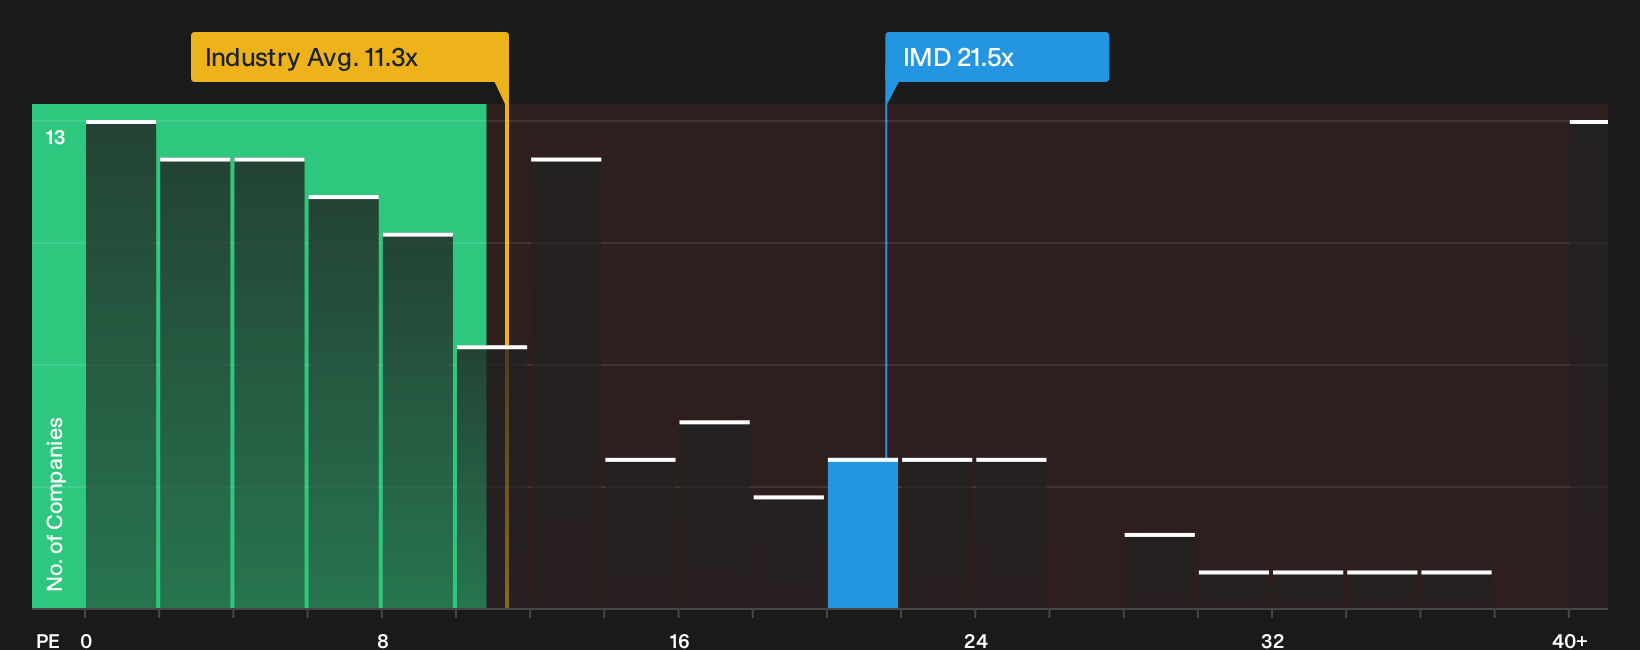
The free cash flow and fair value narrative paints Imdex as 28% undervalued, yet the earnings multiples tell a tougher story. The stock trades on a P/E of 21.5x, while the Australian Metals and Mining group sits nearer 11.3x and the fair ratio is 12.6x. That gap points to richer pricing on earnings. This raises the question: how much comfort should investors really take from the cash flow case?
To weigh that earnings premium against the fair ratio and industry and peer benchmarks in more detail, take a closer look at the valuation breakdown via See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the Imdex story appears finely balanced between promise and concern, consider taking prompt action and stress test the numbers yourself by weighing its 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Imdex?
You do not need to stop at Imdex. Cast a wider net now so you do not miss solid businesses or mispriced opportunities that fit your style.
- Target potential turnarounds by scanning 20 elite penny stocks with strong financials that already show strong financial foundations instead of relying on hype alone.
- Zero in on mispriced quality by reviewing the 5 high quality undervalued stocks that combine healthier balance sheets with room for a better market view.
- Prioritise resilience first by checking the 6 resilient stocks with low risk scores that pair lower risk scores with more durable fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com