
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Jamaican Financial Stocks With Earnings Leverage to Higher Interest Rates
Jamaican inflation just jumped to 8.6%, food and transport costs are biting, and the Bank of Jamaica may feel pressure to keep interest rates higher for longer. That is painful for borrowers, but it can shift earnings power toward certain financial stocks that earn more on every dollar they lend or invest. This article unpacks that story and highlights 3 Jamaican banking and financial services stocks exposed to these inflation and rate shocks.
The three stocks covered below are just a sample, and the full screen surfaces 0 more Jamaican banking and financial services companies with equally compelling rate exposure stories that are not covered in this article.
If you want to identify and analyze the wider set of potential beneficiaries, head straight to the Jamaican banking and financial services beneficiaries of higher interest rates screener to filter the list and focus on your highest conviction ideas.
NCB Financial Group (JMSE:NCBFG)
NCB Financial Group is a large Kingston based financial group that ties directly into the higher rate theme through its broad lending and investment book. It earns about J$37.4b from Consumer & SME Banking, J$20.7b from Payment Services, J$34b from Life and Health Insurance, plus contributions from treasury, wealth and general insurance, and has a market value near J$176.6b.
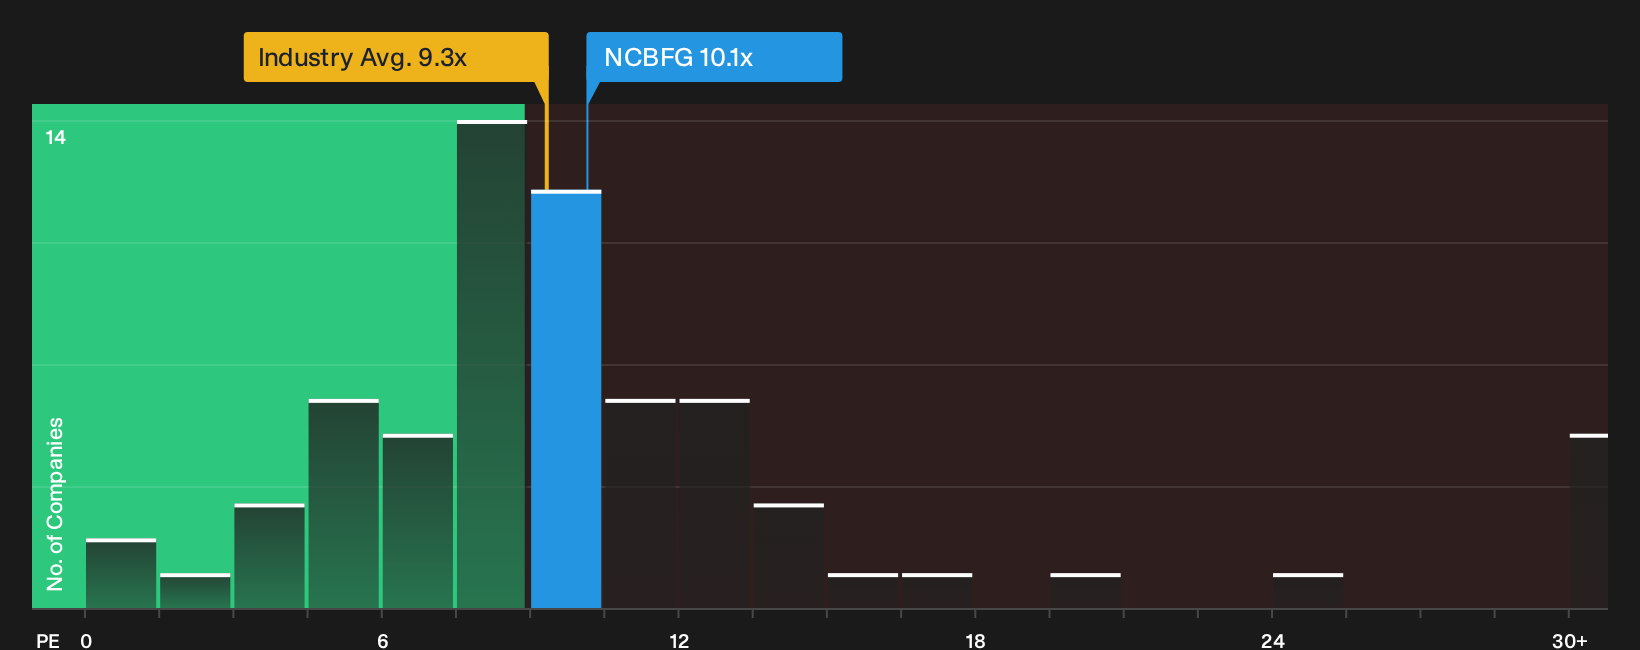
NCB Financial Group gives you a large Jamaican lender, insurer and asset manager. Its core earnings come from interest bearing loans and financial assets that can benefit when policy rates stay higher for longer. The business already shows higher net interest income alongside a lower P/E than the wider market. The effect of its funding mix still hangs over how much of that rate support reaches the bottom line if conditions shift again.
How that funding mix plays out is exactly what the 1 key reward and 4 important warning signs could be masking for NCB Financial Group right now.
Scotia Group Jamaica (JMSE:SGJ)
Scotia Group Jamaica is a long established Kingston based banking group in this higher rate screener because most of its income comes from traditional lending and deposits. Retail and corporate banking generate about J$27.4b and J$26.1b in revenue, with treasury at J$6.4b, insurance at J$5.6b and investment management at J$4.4b, supporting a market value near J$222.5b.
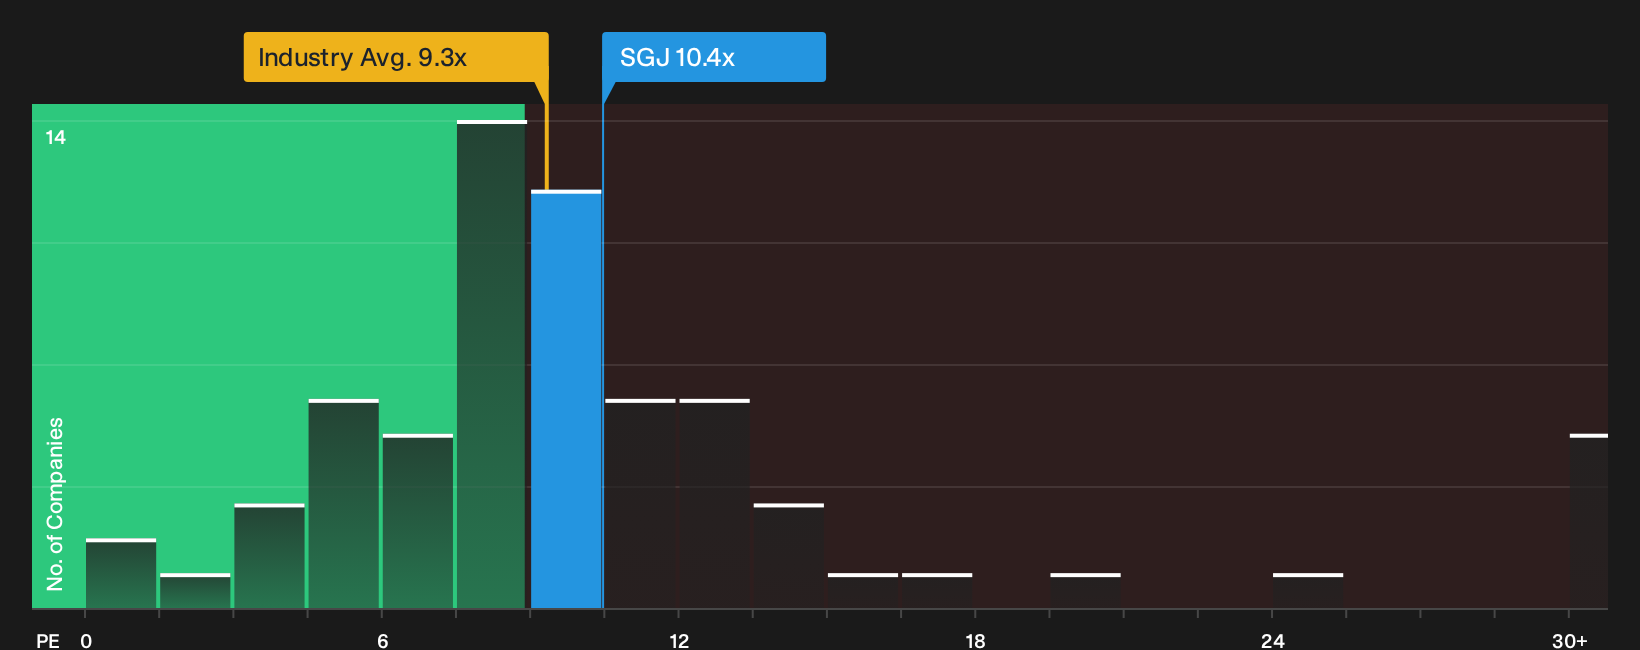
Scotia Group Jamaica gives you a large, domestically focused lender whose core earnings are tightly linked to Jamaican interest rates. It has a 10.4x P/E below the wider market, a 30.4% net profit margin and 12.2% ROE in a period when net income and EPS have been growing. The appeal of that earnings engine in a higher for longer rate setting depends on how one quiet pressure on its profitability evolves.
That quiet pressure is exactly what the 2 key rewards and 1 important warning sign could be revealing for Scotia Group Jamaica before the story moves further.
Eppley (JMSE:EPLY)
Eppley is a Kingston based investment company that fits the higher rate theme because it holds credit and fixed income assets that can reprice as Jamaican yields move. It earns about J$1.3b in Jamaica and carries a market value around J$6.3b.
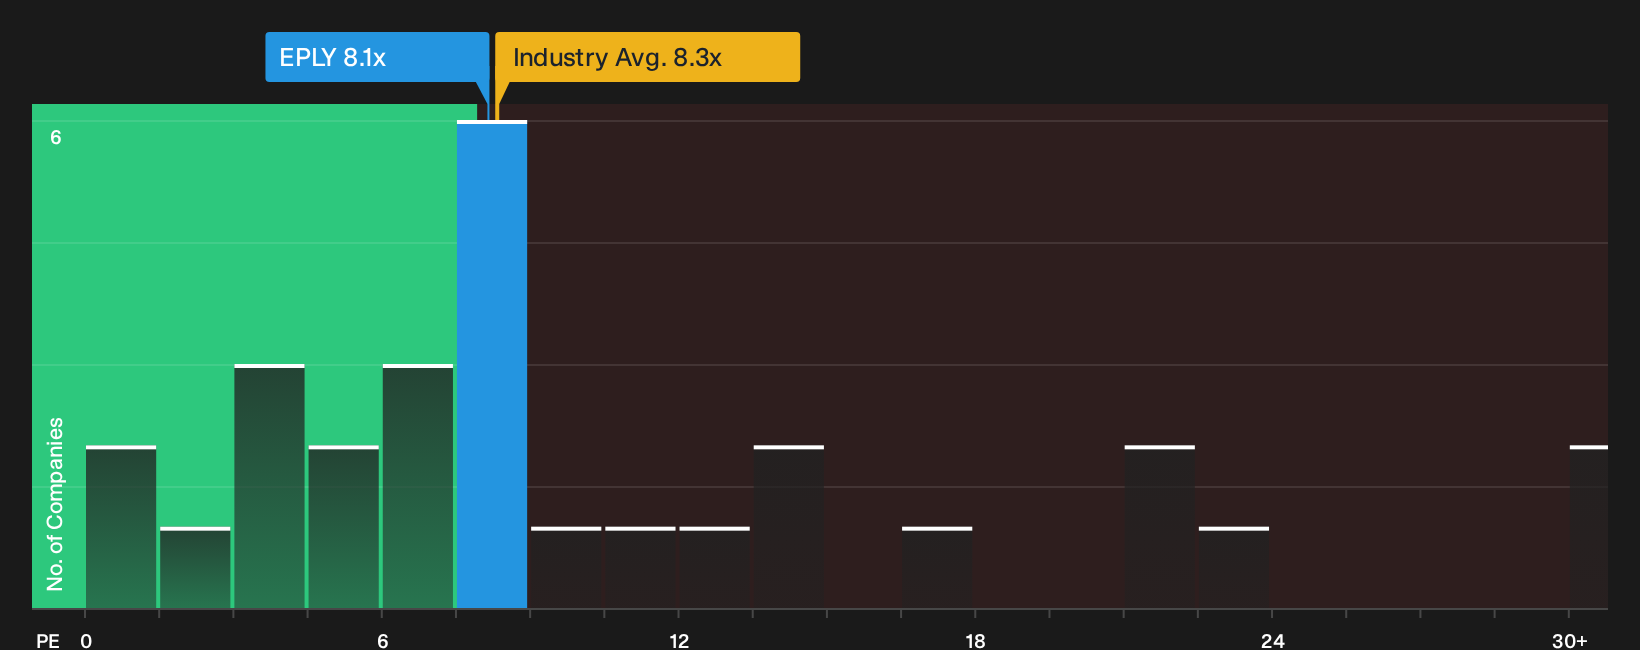
Eppley provides focused exposure to Jamaican credit and fixed income assets, with a P/E of 8.1x compared with a 16x local market and a 12.7x diversified financials benchmark, plus a 3.93% dividend yield. That mix of rate exposure and funding structure influences how much of the interest rate cycle is reflected in earnings quality.
That earnings quality question is where the 1 key reward and 4 important warning signs (1 is major!) comes in, highlighting where Eppley’s rate exposure could quietly magnify returns or cap upside.
Curious About What Else You Might Be Missing?
Fresh ideas move first. By the time every investor is talking about a breakout, the easy entry can be gone. Scan under the radar for now and consider acting while the opportunity is still developing.
- Explore steady compounding potential in companies built to withstand shocks by running through a curated list of solid balance sheet and fundamentals (204 results) before the crowd catches on.
- Follow momentum in future focused automation by zeroing in on hand picked 91 robotics and automation stocks while attention is still directed elsewhere.
- Consider positioning ahead of the grid upgrade theme by reviewing screened 42 power grid technology and infrastructure stocks while the opportunity is still flying under most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com