
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
JPMorgan Chase (JPM), Why Is The Market Looking Twice At Its Latest Update?
JPMorgan Chase (JPM) just logged its first earnings and revenue miss in almost three years, as softer fixed income trading and higher costs contrasted with a stronger net interest income outlook and solid deposit trends.
Recent trading tells a mixed story. The 1-day share price return of 1.25% and 7-day gain of 2.02% show buyers stepping back in after a 30-day share price decline of 2.85%. At the same time, the 1-year total shareholder return of 16.37% and very large 3-year and 5-year total shareholder returns signal that JPMorgan Chase has rewarded patient holders even as near term momentum has cooled.
See how JPMorgan Chase’s rare earnings miss compares with other large banks facing similar rate and credit cycles by exploring our curated set of 32 resilient stocks with low risk scores.
The rare miss, paired with a modest share pullback after a long run of strong returns, leaves a simple question: Is JPMorgan Chase now pricing a weaker franchise or just a mood swing in the market?
Most Popular Narrative: 8% Undervalued
Against a last close of $339.72, the most followed narrative on JPMorgan Chase pins fair value at $370.39. This frames the recent pullback as a potential gap between mood and math.
PMorgan is the best-run large bank in the world, a diversified "fortress balance sheet" spanning consumer, corporate, investment banking and asset management. It tends to emerge from crises stronger.
See why 11 investors see JPMorgan Chase as 8% undervalued.
Result: Fair Value of $370.39 (UNDERVALUED)
Still, the JPMorgan Chase story can break if credit losses spike in a tougher cycle or if lower interest rates pressure net interest income and fee activity.
Find out about the key risks to this JPMorgan Chase narrative.
Another View: JPMorgan Chase Through The P/E Lens
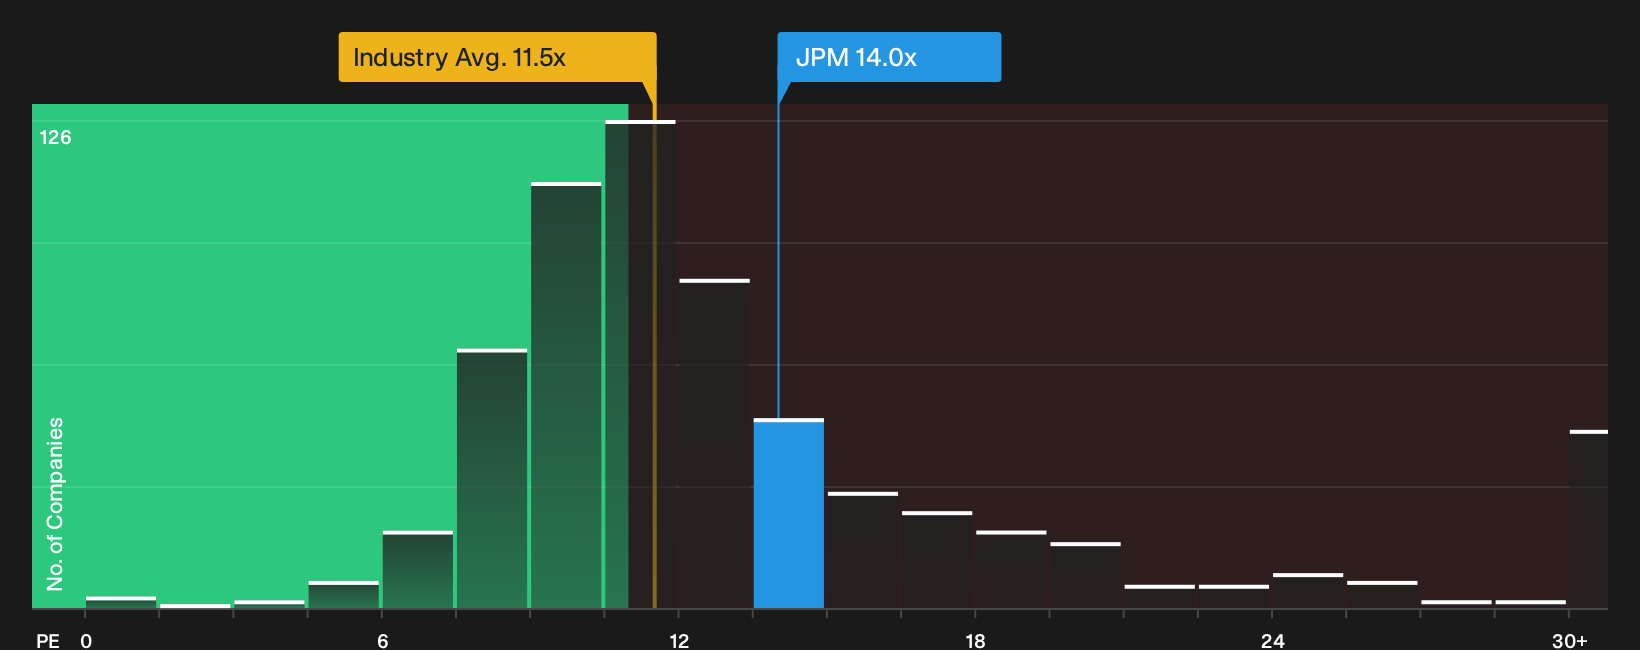
There is a catch to the JPMorgan Chase undervaluation story. On a simple earnings multiple, the stock trades on a P/E of 14x while the US banks group and peer set sit closer to 11.5x, and the fair ratio points to 13.9x.
That small gap sounds trivial in isolation, yet it means investors are paying a richer tag than both industry and peers for roughly similar forecast growth. This raises the question of whether this is quality getting a premium or just leaving less margin for error if sentiment cools.
For a closer look at how this earnings multiple stacks up against what the numbers suggest the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Pulled between rewards and risks, sentiment around JPMorgan Chase is split enough that your own judgment matters more than any single narrative. To weigh the upside against the pressure points for yourself, start by looking at the balance of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond JPMorgan Chase?
Do not stop with one banking giant when you can scan an entire opportunity set tailored to the way you like to invest.
- Target resilient businesses that aim to prioritise balance sheet strength by starting with our list of solid balance sheet and fundamentals (25 results).
- Hunt for potential mispriced opportunities where quality and valuation may line up by reviewing the 33 high quality undervalued stocks.
- Focus on dependable cash returns if income matters to you by working through a curated list of 8 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com