
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will UBS Upgrade Change Bouygues Stock Narrative
- Bouygues Construction recently won a €94 million drainage tunnel contract in Hong Kong, while Bouygues Telecom’s network is being used by new operator Meowan for French fixed and mobile offers.
- The Hong Kong infrastructure project and fresh wholesale demand from Meowan both illustrate how Bouygues monetises its engineering and telecom assets across regions and customer segments.
- We will now examine how Bouygues’ investment narrative might shift in light of the Hong Kong contract awarded to Bouygues Construction.
Scan beyond Bouygues and this Hong Kong contract by reviewing a hand picked list of solid balance sheet and fundamentals (204 results) that may also monetise infrastructure and telecom demand across regions.
Bouygues Investment Narrative Recap
To own Bouygues, you need to be comfortable with a multi pillar story. Equans and the broader construction and energy services activities carry a large, higher margin order book. Bouygues Telecom and TF1 face intense competition and shifting customer habits, which can keep pressure on pricing and advertising income in the near term.
The short term swing factor is still execution at Equans and on large infrastructure projects, because that supports group margins while France remains tough for construction. The biggest risk remains prolonged pricing pressure in French telecom and weaker media advertising. The recent Hong Kong tunnel win and Meowan wholesale deal do not materially change those near term drivers.
The Meowan launch on Bouygues Telecom’s network is the most relevant development here. It highlights how Bouygues can use its fibre build out and mobile grid to attract wholesale clients alongside retail users. Extra traffic volume can help absorb network investment, as long as wholesale pricing does not undercut the economics of its own offers.
For you as a shareholder, the key operational question is whether incremental wholesale demand and new usage can offset ARPU pressure in a crowded French telecom market. If Bouygues can combine disciplined Equans execution with steady telecom cash generation and manage debt sensibly, then the construction wins in places like Hong Kong sit on top of a more balanced group story.
What The Hong Kong Win Means Against Bouygues’ 2029 Targets
Bouygues' narrative projects €60.7 billion revenue and €1.6 billion earnings by 2029. This assumes 2.5% yearly revenue growth and an earnings increase of about €300 million from €1.3 billion today.
Uncover why Bouygues' fair value indicates a 44% potential upside to its current price, which could narrow quickly if sentiment around Bouygues improves.
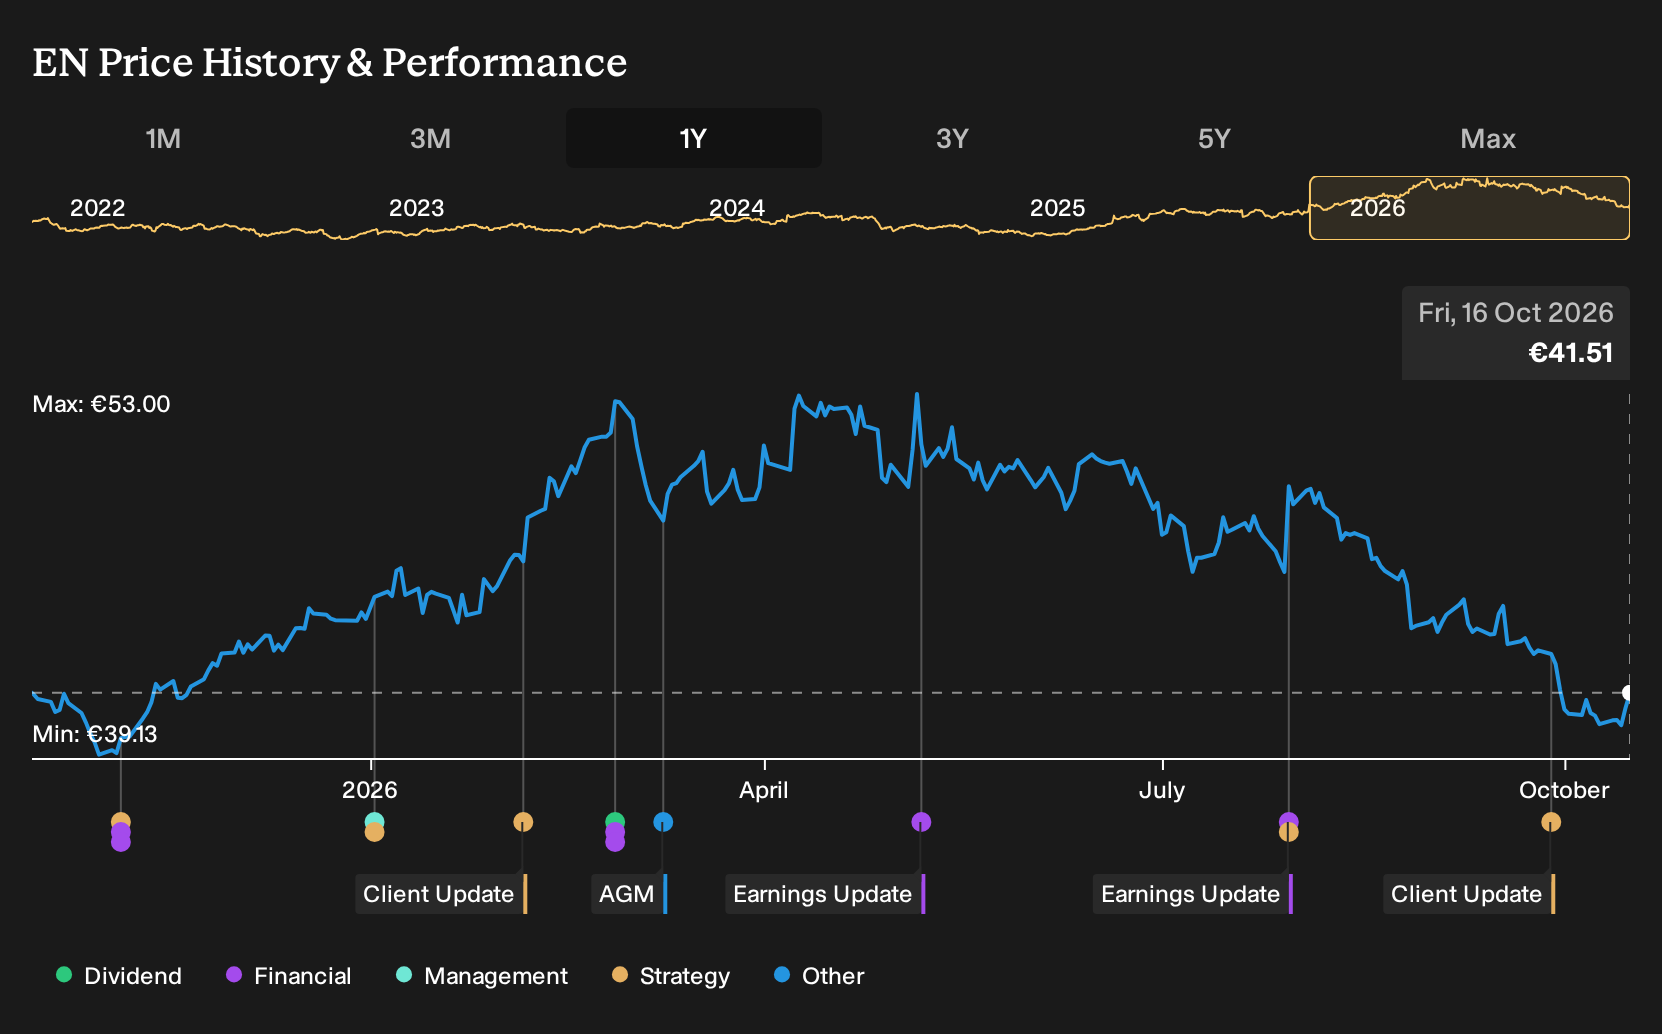
Exploring Other Perspectives
One alternate angle on Bouygues is the bullish view that Equans turns the group into more of an infrastructure compounder, with the Hong Kong contract serving as another proof point. Those analysts were already pencilling in about €63.3b of revenue and €1.9b of earnings by 2029. You can now ask how this fresh news might reshape those optimistic forecasts and compare them with more cautious views.
Explore 2 other Bouygues fair value estimates, including one that suggests there may be as much as 67% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Bouygues research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Bouygues. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bouygues' overall financial health at a glance.
Looking For More Bouygues-Like Investment Ideas?
If the Bouygues story has sharpened how you think about risk, cash flow and balance sheets, it can be useful to compare it with other companies that share some of those traits. The Simply Wall St Screener lets you do that in a structured way so you can keep building a watchlist that fits your own risk and income preferences.
- If you like the idea of resilient businesses with room to compound over time, start with a curated set of 191 high quality undervalued stocks that pair quality fundamentals with share prices that may not fully reflect them.
- If capital preservation sits high on your priority list, focus on a 234 resilient stocks with low risk scores that filters for companies with stronger balance sheets and lower overall risk scores.
- If income matters as much as price appreciation, consider a 216 dividend fortresses built around higher yielding payers that combine distribution strength with underlying financial support.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com