
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
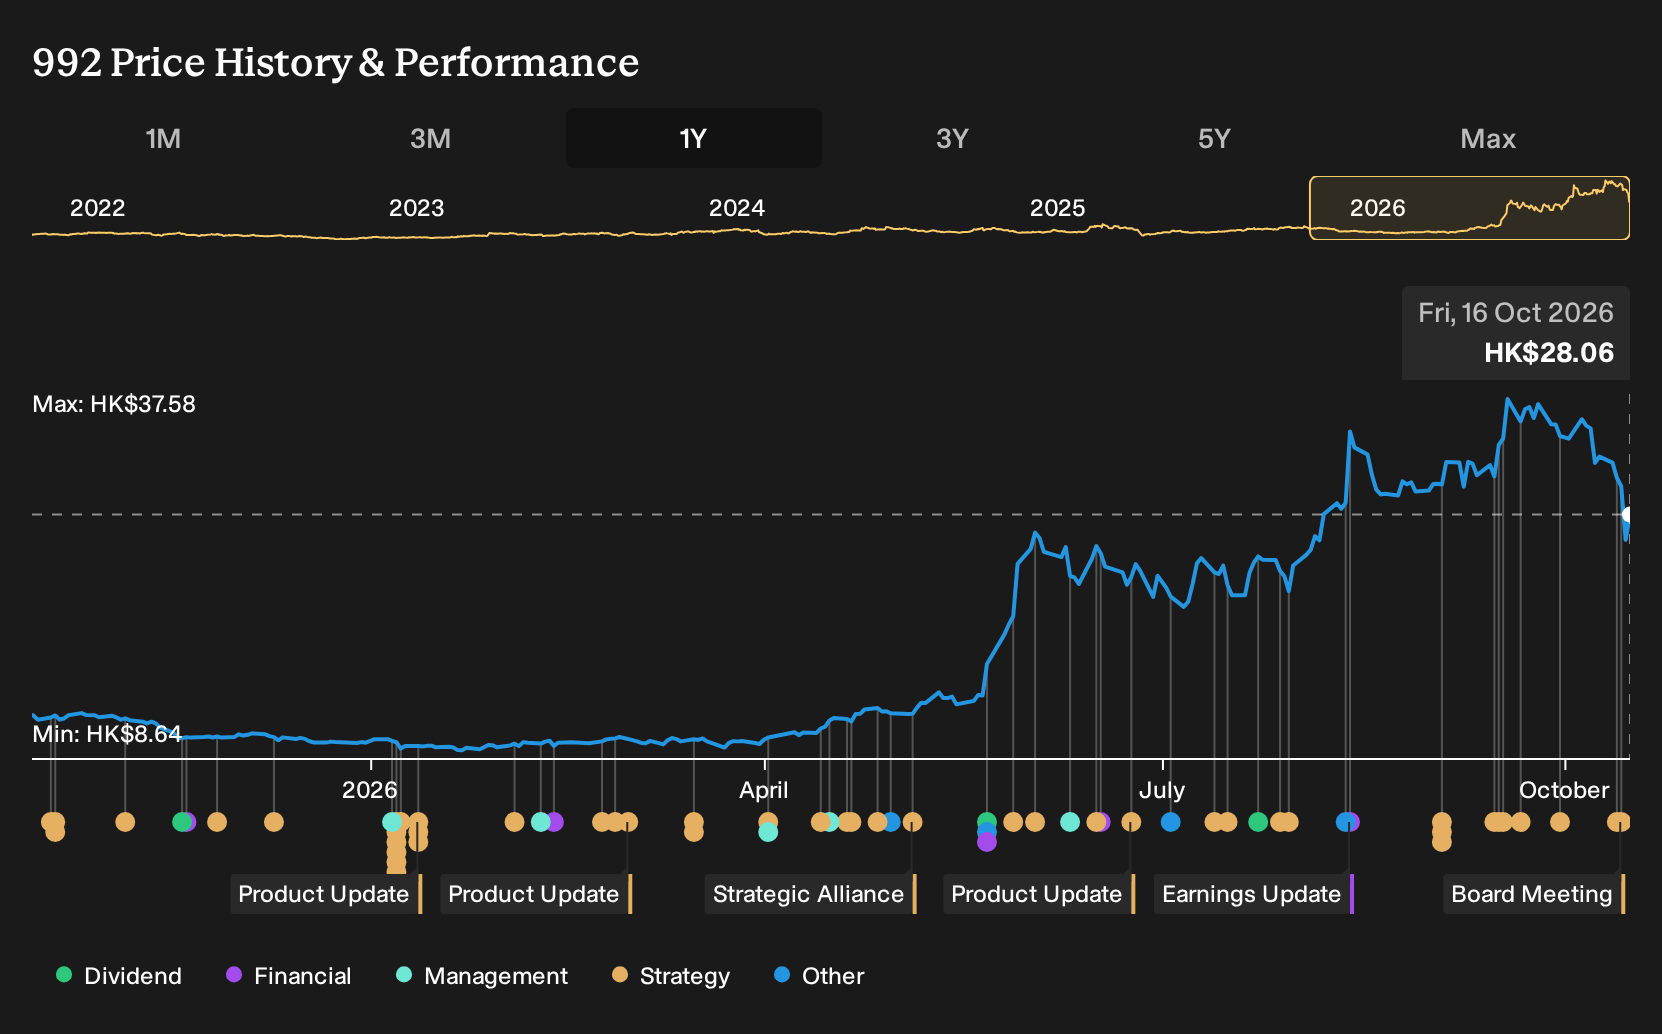
Lenovo Stock In Focus After Driverless Truck Platform Win
- On 13 October 2026, Bot Auto TX Inc. announced it had selected Lenovo Group's AD1 autonomous driving domain controller, built on NVIDIA Hyperion, as the production compute platform for its Class 8 driverless trucks. The company is targeting initial integration from early 2027 with a hardware bill of materials of about $50,000 per truck for compute and sensors.
- The Lenovo AD1 win gives the company a foothold in Level 4 autonomous trucking, tying its compute hardware directly to Bot Auto's plan to scale autonomous capacity and accumulate a billion driverless miles by 2031, while emphasizing cost efficiency versus rival systems.
- We will now look at how Lenovo Group's broader investment narrative might be reshaped by this AD1 autonomous trucking design win.
Scan how Lenovo Group's AD1 trucking win fits into a wider autonomy and AI hardware story by comparing it with other hand picked 55 AI infrastructure stocks.
Lenovo Group Investment Narrative Recap
To own Lenovo Group, you need to believe the pivot toward AI infrastructure, services and higher value PCs can matter more than near term margin pressure. The Bot Auto TX AD1 win fits that story by putting Lenovo hardware into a Level 4 autonomy stack, but by itself it does not change the near term earnings profile or reset the biggest catalysts.
Right now, the key swing factor is whether heavy R&D and AI infrastructure spending in the Infrastructure Solutions Group can scale into profitable volume before it drags too hard on group margins. The main risk is that PC and device demand softens as cyclical tailwinds fade, leaving Lenovo carrying elevated costs, thinner 0.9% margins and more scrutiny on its high P/E and recent share price volatility.
The AD1 trucking deal lines up most closely with the broader push into AI infrastructure and data center hardware, where analysts already see strong demand for high performance servers and edge compute. This is the same part of Lenovo Group that is investing heavily, so each concrete customer program gives investors another operational proof point for that spend, even if revenue from one design win is limited.
For catalysts, the focus is on whether the Infrastructure Solutions Group can move from investment mode toward better profitability and whether Solutions and Services keeps building recurring, higher margin income. The Bot Auto partnership adds an applied AI workload that leans on NVIDIA Hyperion and Lenovo compute, which helps illustrate how Lenovo’s AI hardware and services pitch can extend beyond traditional PCs, while still leaving execution, pricing and supply chain risks firmly in view.
Lenovo Group's narrative projects $138.8b revenue and $6.0b earnings by 2029. This assumes 15.0% yearly revenue growth and an earnings increase of about 7.5x from $798.0m today.
Uncover why Lenovo Group's fair value indicates a 62% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One contrasting angle focuses on Lenovo Group's reliance on low margin hardware, even as Bot Auto's AD1 deal highlights new AI uses. The most bearish analysts were already assuming slower 9.3% yearly revenue growth and about $5.0b earnings by 2029. That is a far more cautious story. This trucking announcement could eventually push those expectations higher or pull consensus closer to them. Readers can use these wide opinion gaps as a prompt to explore several different scenarios before deciding how this news fits their own Lenovo thesis.
Explore 4 other Lenovo Group fair value estimates, including one that suggests it could be worth just HK$27.61.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis and judgment.
- A great starting point for your Lenovo Group research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Lenovo Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lenovo Group's overall financial health at a glance.
Looking for more investment ideas beyond Lenovo Group?
If this Lenovo Group story has you thinking about portfolio upgrades, it can help to compare it with other companies that share similar qualities, whether that is value, resilience or income potential.
- For investors who want quality on sale, scan a hand picked 191 high quality undervalued stocks that pair solid fundamentals with discounted prices.
- If capital preservation sits high on your priority list, filter for sturdier businesses by checking out a 234 resilient stocks with low risk scores that screens for lower risk profiles.
- Income focused investors can zero in on cash returns by reviewing a 216 dividend fortresses that focus on yields of 5% and above.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com