
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Leadership Reshuffle Require Action From Hamilton Lane Stock Investors?
- Hamilton Lane has reshaped its senior ranks, appointing long-time director Hartley R. Rogers as Co-CEO alongside Juan Delgado-Moreira, while former Co-CEO Erik R. Hirsch shifts into an Executive Co-Chair role focused on long-term growth initiatives.
- This restructuring concentrates decades of private markets and client-facing experience at the top of Hamilton Lane, which could influence decisions around fund design, fee-earning AUM growth, and how the business balances expansion with regulatory and operational complexity.
- We will look at how Hamilton Lane's investment narrative intersects with Hartley Rogers stepping in as Co-CEO alongside Juan Delgado-Moreira.
Scan how Hamilton Lane's leadership reshuffle compares with other asset managers quietly repositioning their executive teams by reviewing our curated list of list of solid balance sheet and fundamentals (25 results).
Hamilton Lane Investment Narrative Recap
To own Hamilton Lane, you need to believe the firm can keep drawing capital into private markets products while managing higher regulatory and technology related costs. The core near term swing factor is how quickly fee earning AUM grows across evergreen and customized mandates. This leadership reshuffle concentrates long tenured insiders at the top, which on its own does not materially change that operating backdrop.
The biggest operational risk still comes from fee pressure and rising complexity as Hamilton Lane adds more customized and tech enabled solutions. If execution slips on compliance, client service or platform reliability, margin progress could stall. Governance remains a support, with an experienced board and management team and high reported return on equity.
The most relevant announcement is that Erik Hirsch is moving from Co CEO to Executive Co Chair, while Hartley Rogers becomes Co CEO alongside Juan Delgado Moreira. Hirsch will focus on long term growth initiatives and remain on the board. That keeps a long serving capital allocator close to decisions on product mix, distribution partnerships and technology investment.
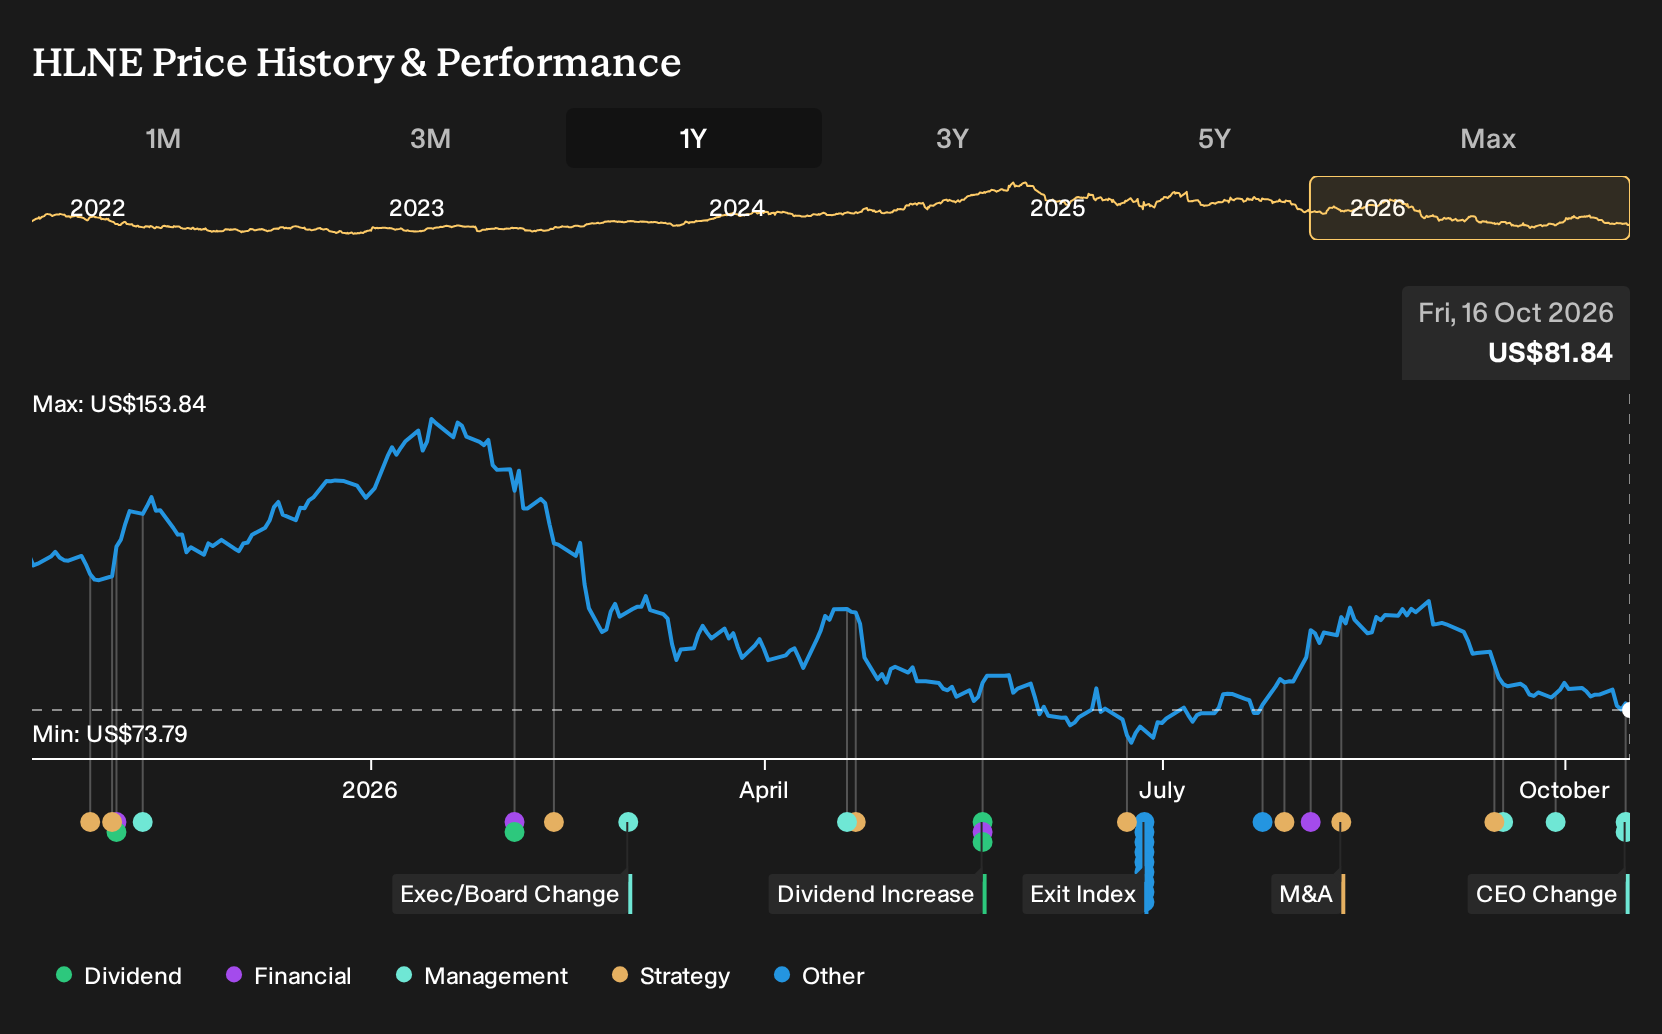
For catalysts, the key question is whether this leadership setup maintains momentum in evergreen funds, separate accounts and tech driven services that support fee related revenue. Execution around regulatory change and fee terms will be important, especially as investors weigh the firm’s recent share price decline against analyst expectations for continued earnings expansion.
Hamilton Lane's current analyst narrative points to about US$1.1b in revenue and US$496.8m in earnings by 2029, built on an assumed 13.9% yearly revenue growth rate and an earnings increase of roughly US$247.6m from about US$249.2m today.
Uncover why Hamilton Lane's fair value indicates a 58% potential upside to its current price, a gap that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One alternate view on Hamilton Lane leans hard into Evergreen growth as the main catalyst. In that story, the most optimistic analysts were mapping out revenue of about US$1.2b and earnings near US$521.2m by 2029, noticeably above consensus. Your takeaway is simple: opinions differ widely, and this leadership shuffle may push those forecasts in new directions.
Explore 8 other Hamilton Lane fair value estimates, including one that suggests as much as 194% potential upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hamilton Lane research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hamilton Lane. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hamilton Lane's overall financial health at a glance.
Looking For More Investment Ideas Beyond Hamilton Lane?
If Hamilton Lane is only one piece of your watchlist, it can help to scan a wider set of companies that match the kind of risk, quality and income profile you want.
- If you are hunting for mispriced quality, run through our lens on 33 high quality undervalued stocks that pair robust fundamentals with attractive valuations.
- If capital preservation sits high on your list, focus on businesses highlighted in our 32 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- If dependable income matters most, filter for companies in our universe of 8 dividend fortresses that offer higher yields with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com