
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Afry (OM:AFRY) Could Be 20% Undervalued As New Energy Mandates Land
Afry (OM:AFRY) has picked up two fresh energy mandates, advising on Vietnam’s 1.5 GW Quynh Lap LNG power project and supporting Swissgrid on three Swiss substations, pushing its engineering expertise further into long duration infrastructure.
Afry’s recent energy contracts land against a tricky backdrop for holders, with the share price at SEK105.4 after a 3.74% 1-month share price return but a year-to-date share price decline of 30.38% and a 1-year total shareholder return that has fallen 33.44%. This suggests sentiment is still rebuilding despite fresh project wins.
Contrast Afry’s long-duration energy work with other potential ideas in the sector by scanning our curated 42 power grid technology and infrastructure stocks for grid and infrastructure plays tied to similar investment themes.
Afry is picking up complex energy work while the share price has fallen sharply over the past year. That combination raises a key issue: is this resilient business already cheap enough at SEK105.4 or not yet?
Most Popular Narrative: 20.3% Undervalued
Afry’s most followed valuation view points to a fair value of SEK132.17, versus the latest close at SEK105.4, which frames the current share price as meaningfully below that narrative estimate while investor sentiment is still fragile after a weak 1-year return profile.
The company has undertaken large-scale restructuring and portfolio optimization, including a new group structure and significant cost reduction initiatives. These are expected to improve operational efficiency, utilization rates, and net margins over the medium term.
Geographic expansion through strategic acquisitions in emerging markets, as seen with the purchase of Reta Engenharia in Brazil, is diversifying revenue away from cyclical Europe and opening new growth opportunities in critical high-demand sectors (e.g., mining/metals). This is described as supporting sustainable earnings growth.
See why 16 investors see Afry as 20% undervalued.
The narrative anchors that SEK132.17 view on analysts’ assumptions using a 6.65% discount rate, a path to SEK27.7b of revenue and SEK1.7b of earnings by 2029, and a P/E of 10.6x on those future profits. This is described as being below the current European Professional Services industry multiple of 17.4x mentioned in the same framework.
Those projections also sit alongside SWS’ internal check that Afry screens as trading 58.9% below an estimated future cash flow value of SEK256.36 per share. This comes even as recent financials show a 3.4% annual decline in earnings over five years and a slip in net margin from 3.6% to 3.1%, so readers need to weigh discounted cash flow optimism against a tougher recent track record.
Result: Fair Value of SEK132.17 (UNDERVALUED)
Still, the Afry narrative can weaken if restructuring costs stay elevated or if weaker client demand keeps utilization soft and squeezes already thin margins.
Find out about the key risks to this Afry narrative.
Another View: Afry Through The Earnings Multiple Lens
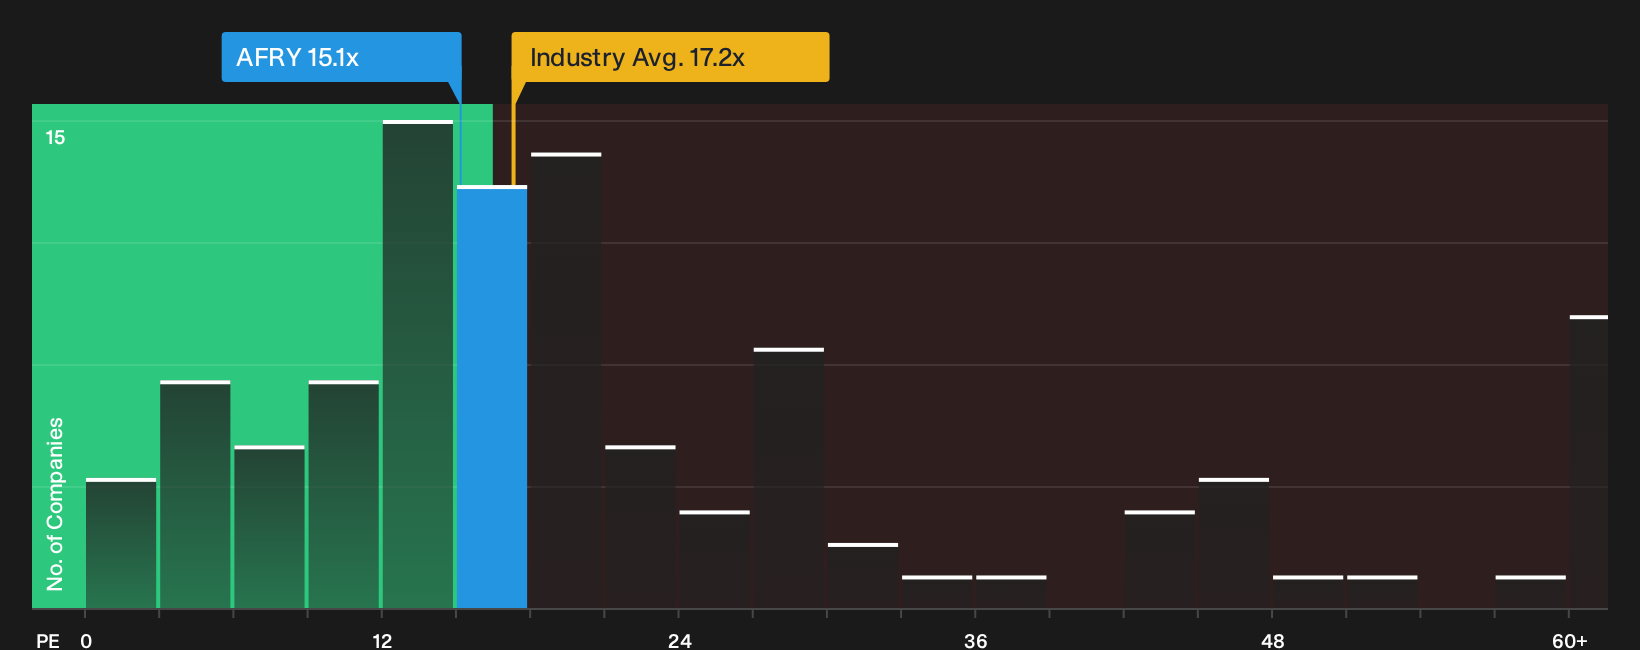
Afry may screen as undervalued on fair value estimates around SEK132, yet its current P/E of 15.1x sits slightly above the peer average of 14.7x, while still below a fair ratio of 23.1x. That mix of a mild premium to peers but a discount to the fair ratio leaves a simple question: Is the market being cautious or giving you a margin of safety?
To see how that P/E gap could close over time and what it might mean for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals from Afry’s recent projects and valuation views can pull you in both directions, so move quickly, review the data for yourself, and weigh the 2 key rewards and 1 important warning sign
Looking for more Afry investment ideas?
If Afry has your attention but you want a broader watchlist, use the Simply Wall Street Screener to spot opportunities before they move without you.
- Target dependable cash generators by scanning companies with a list of solid balance sheet and fundamentals (204 results) that can better handle shocks and still fund growth.
- Hunt for potential mispricing by reviewing a curated 191 high quality undervalued stocks that pair strong fundamentals with prices that may not fully reflect them yet.
- Prioritise sleep-at-night exposure by checking a 234 resilient stocks with low risk scores that aims to limit nasty surprises while keeping your capital working.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com