
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Why JOST Werke (XTRA:JST) Is Drawing Fresh Attention
Fresh attention on JOST Werke (XTRA:JST) has been sparked by commentary that pairs its multi year shareholder gains with a relatively high P/E multiple compared with industry and peer averages.
Recent trading reflects that tension between strong history and richer valuation. The share price is up 9.09% over the past 90 days and 11.73% year to date. The 1 year total shareholder return of 21.21% and 3 year total shareholder return of 45.27% point to momentum that has rewarded patient holders, even as some investors reassess JOST Werke at a higher P/E multiple.
Compare JOST Werke's higher P/E ratio with other potentially mispriced industrial players by scanning our hand picked 186 high quality undervalued stocks for ideas beyond this one stock.
Bulls point to JOST Werke’s strong multi year returns and growth in revenue and net income. Bears focus on the richer P/E multiple. Which side do the current valuation metrics actually support?
Most Popular Narrative: 24% Undervalued
Against a last close of €60, the most widely followed narrative places JOST Werke’s fair value at €79. This frames the current P/E debate in the context of discounted future cash flows and margins rather than today’s headline multiple.
Hyva integration and cross-selling synergies are ramping, with management confirming synergy targets of €23 million to €28 million and a payback period of under one year. This directly supports higher EBIT margins and EBITDA for JOST Werke.
See why 9 investors see JOST Werke as 24% undervalued.
Result: Fair Value of €79 (UNDERVALUED)
Still, two things can quickly challenge that 24% undervalued case for JOST Werke if they worsen: sustained logistics cost pressure in EMEA and ongoing working capital drag from higher safety stocks.
Find out about the key risks to this JOST Werke narrative.
Another View: JOST Werke Looks Expensive On Earnings
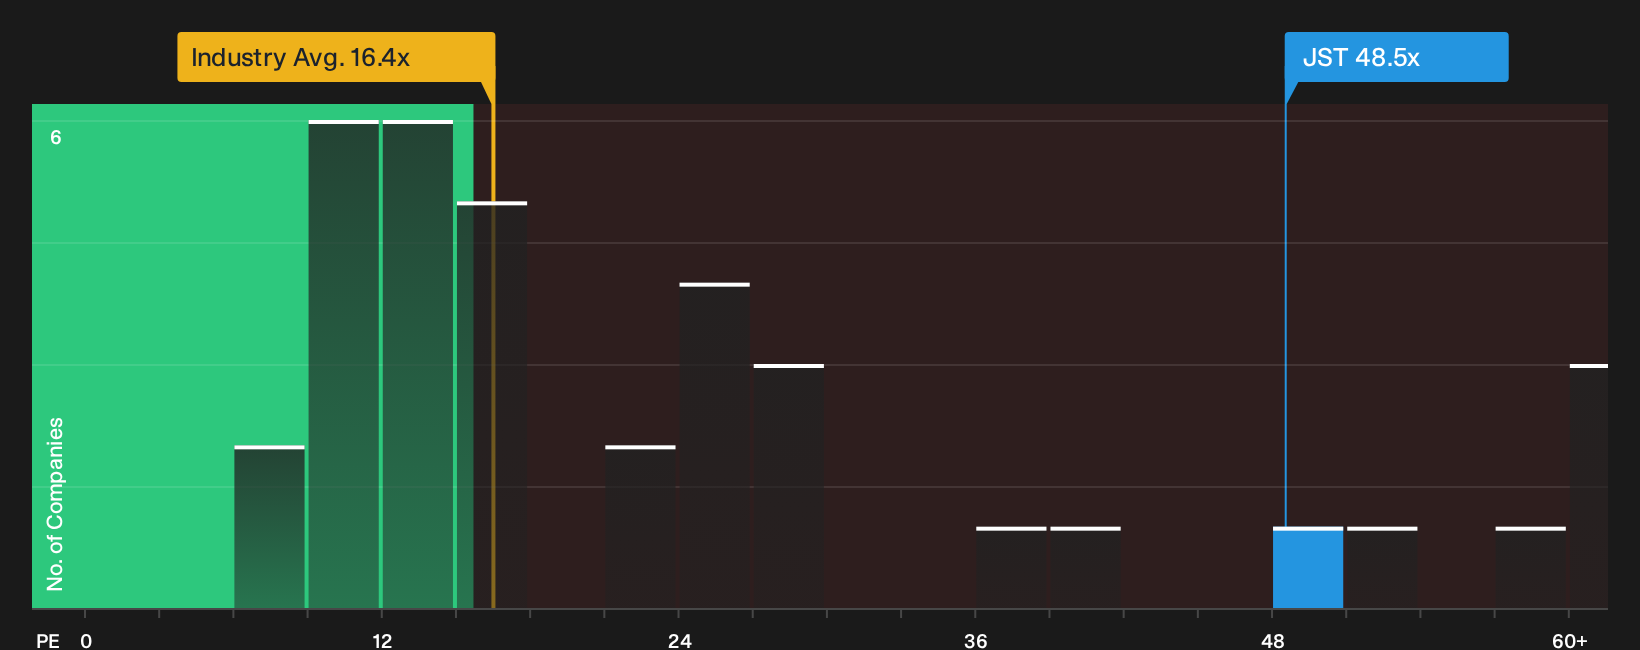
The DCF narrative paints JOST Werke as materially undervalued, yet the P/E lens tells a very different story. The stock trades on 48.5x earnings, versus 30.3x for peers and 16.3x for the wider German Machinery group, while the fair ratio points to 31.4x as a level the market could move toward. That gap signals real valuation risk if sentiment swings away from growth forecasts.
Investors weighing these conflicting signals may want to stress test their own earnings assumptions against this richer multiple profile before leaning too hard on the discounted cash flow story, then review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around JOST Werke’s P/E and fair value can feel confusing, so prioritize doing your own homework and weigh both sides carefully, starting with the 3 key rewards and 4 important warning signs.
Looking for more investment ideas beyond JOST Werke?
Do not just stop at JOST Werke. Give yourself options by lining up a watchlist of other candidates that match your preferred investing style and risk level.
- Hunt for potential value opportunities by reviewing companies flagged in the 186 high quality undervalued stocks that combine stronger fundamentals with comparatively lower valuations.
- Prioritize resilience and balance sheet strength by scanning the list of solid balance sheet and fundamentals (204 results) to see which businesses pair lower leverage with healthier financial buffers.
- Get ahead of the crowd by checking the 615 high quality undiscovered gems and see which underfollowed stocks have fundamentals that could warrant a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com