
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Caught Out By HD Korea Shipbuilding's Fall? Here's What Bears Saw
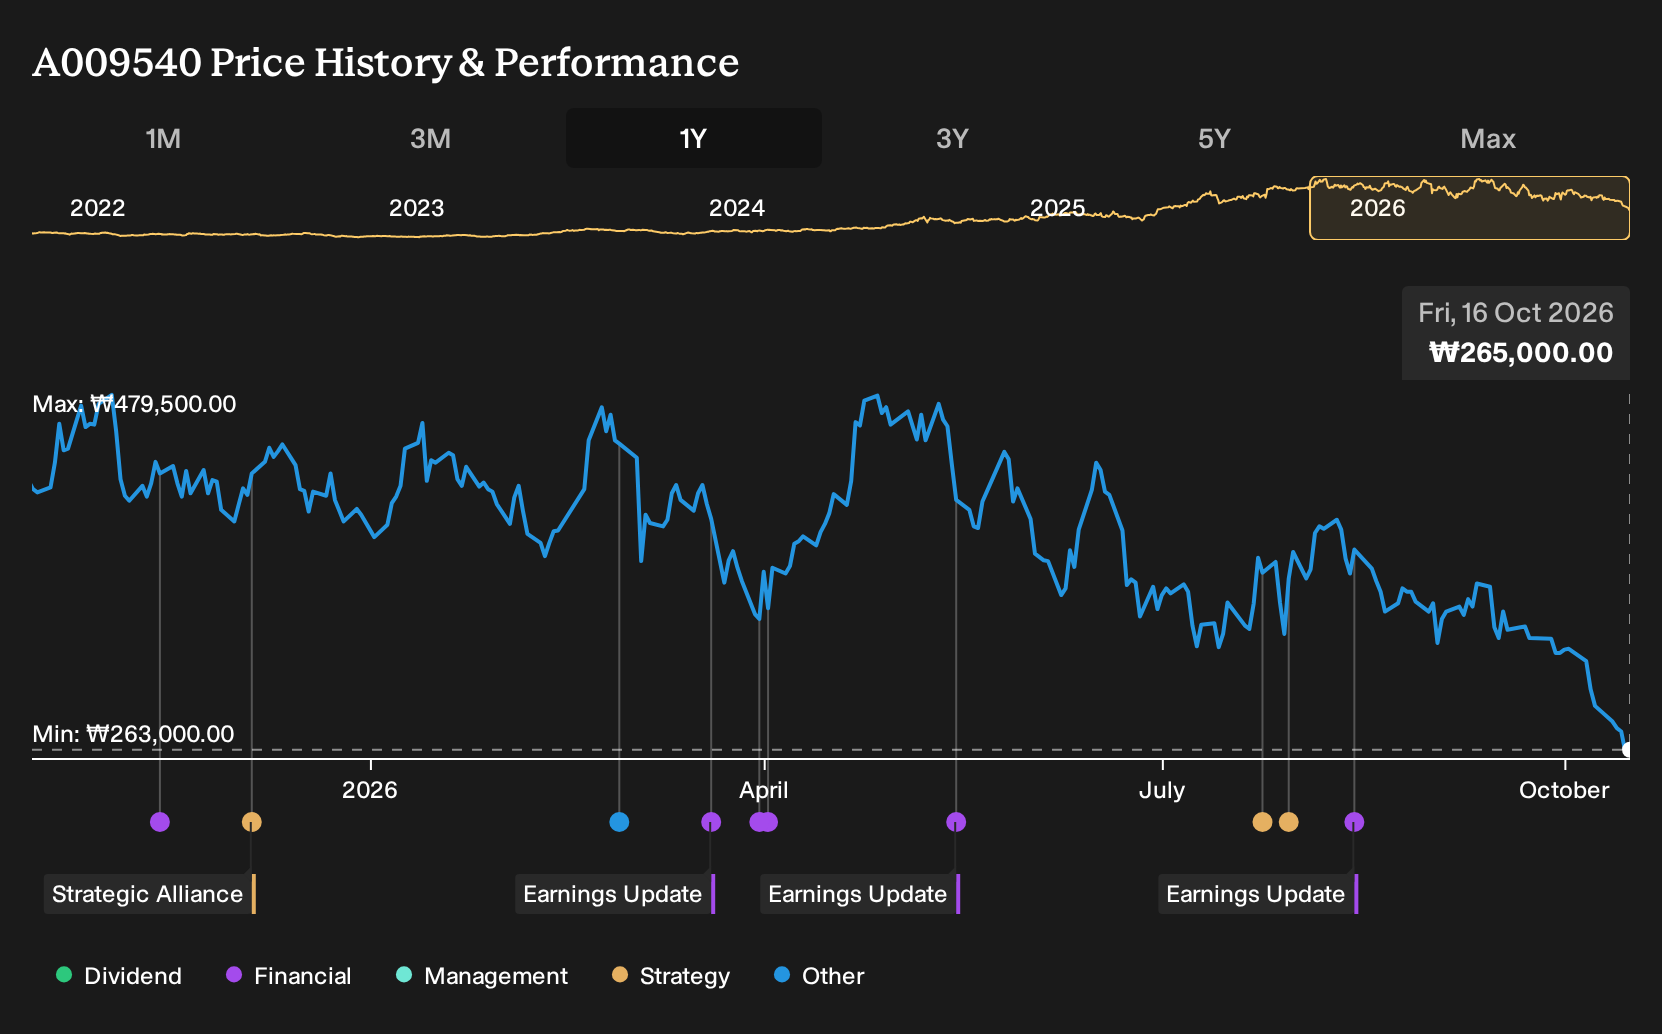
HD Korea Shipbuilding & Offshore Engineering just reported Q2 2026 figures showing higher total revenue and a net margin that moved from 4.8% in Q2 2025 to 14.4%, a big shift for any industrial heavyweight. Investors who held HD Korea Shipbuilding & Offshore Engineering over the past year are down 34.7%, including dividends. If you had been deciding whether to buy on 16 October 2025, how should this mix of stronger results and painful share loss shape what you expected next?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
HD Korea Shipbuilding & Offshore Engineering has already moved. See which of 187 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Choose Between On HD Korea Shipbuilding
The shares cost ₩420,000 at the start of the period, which meant any decision on HD Korea Shipbuilding & Offshore Engineering needed a clear view on what that figure already assumed.
The bullish narrative argued for a fair value of ₩494,000. It leaned on expectations that decarbonization and offshore projects would support demand for eco-friendly vessels and higher-margin offshore work.
The bearish view put fair value at ₩283,000. That case focused on exposure to fossil fuel-related orders and industry overcapacity as potential threats to revenue stability and profitability.
What The HD Korea Shipbuilding Results Actually Tested
The clearest data point was Q2 2026 profitability. HD Korea Shipbuilding & Offshore Engineering reported revenue of ₩8,927,046.477m and net income of ₩1,287,492.189m, with net margin moving from 4.8% to 14.4%. That shift lined up more with the bullish view on margin potential, although it did not on its own settle how durable those economics are.
The lesson is simple: when a story hinges on operating leverage, treat net margin as the claim to test. Track whether higher earnings come from better profitability, not just a bigger order book, before trusting any narrative elsewhere.
What HD Korea Shipbuilding's Share Drop Now Asks You To Believe
HD Korea Shipbuilding & Offshore Engineering now trades at ₩265,000, after a loss of 34.7% over the past year. The selected Narrative sees Fair Value above that level and leans on engines, vessel mix and offshore or defense work as the main pillars.
For the fall to look like an opening rather than a warning, a buyer today would need confidence that high margin engine, LNG or LPG carriers, offshore and defense projects can be executed well enough to support sturdier earnings despite choppy ordering cycles.
"The rapid mix shift in Engine & Machinery toward dual fuel output, with dual fuel representing 73% of 2 stroke and 79% of 4 stroke engines and Hyundai Marine Engine operating at a 24.4% margin, leaves room for HD Korea Shipbuilding & Offshore Engineering to translate further mix upgrades and volume in high margin engines into upside for segment operating margins and consolidated earnings."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Where HD Korea Shipbuilding Points Next
HD Korea Shipbuilding lives where heavy metal meets long delivery cycles. Your attention naturally stops there.
Look one step sideways and another need appears. Governments want hardware at sea and in the air, but also secure networks and protected data.
A different contractor focuses on that layer. It builds tools that help defend communications, verify identity and keep critical systems online.
The same buyers weighing hulls and engines also wrestle with cyber risk and air traffic density. That tension creates a separate, growing checklist.
If HD Korea Shipbuilding reflects appetite for hardware, this other specialist reflects appetite for secure information. Both pressures are shaping budgets investors now track.
The argument comes with a number attached. → Uncover the robotics company trading 21% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com