
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Institutional Buying Will Impact RHI Magnesita (LSE:RHIM) Investors
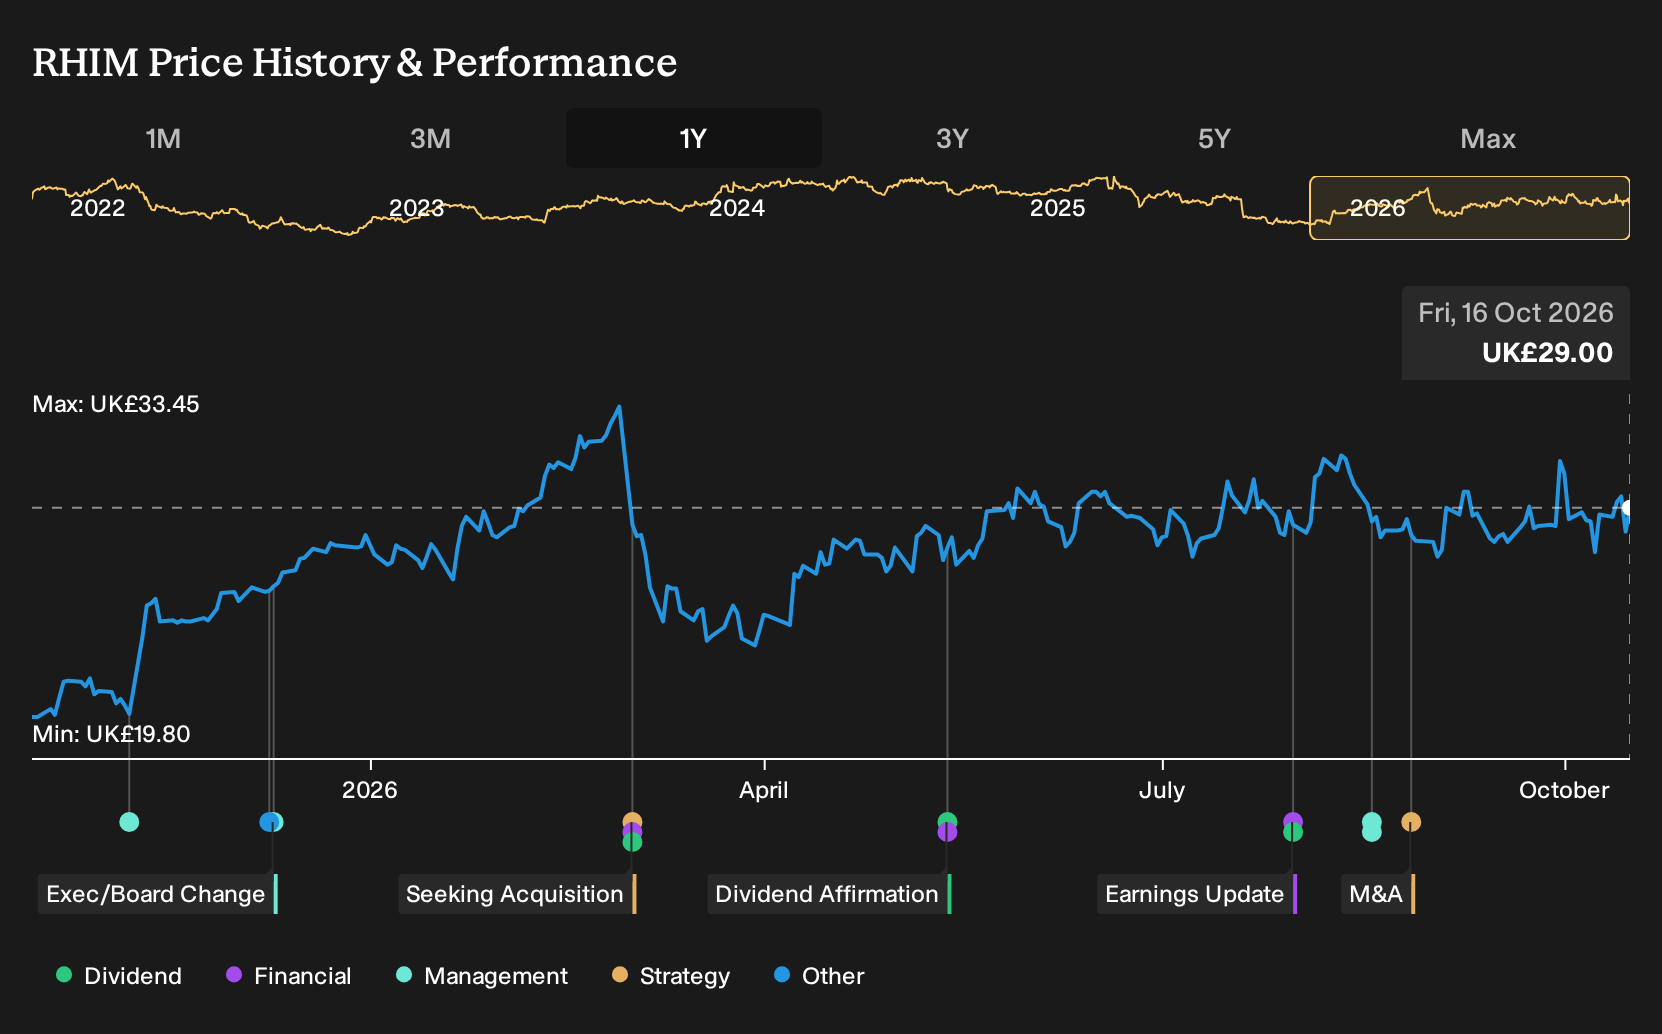
- Recent disclosures showed Man Group and Dimensional Fund Advisors building long positions in RHI Magnesita, together approaching 4% of the refractory producer's share capital, alongside continued investment in U.S. recycling infrastructure and local production capacity.
- These institutional allocations highlight how RHI Magnesita's push into circular-economy recycling and U.S. onshore manufacturing is reshaping its cost base and raw material risk profile.
- We will now see how RHI Magnesita's investment narrative may shift as institutional buying meets its recycling focused local production strategy.
Scan how RHI Magnesita’s circular-economy push compares with other materials players by lining it up against our hand picked list of solid balance sheet and fundamentals (9 results).
RHI Magnesita Investment Narrative Recap
To own RHI Magnesita, you need to be comfortable with a business built on heavy industry cycles but trying to reshape its cost base through local production, recycling and digital efficiency. The short term story still revolves around getting postponed higher margin industrial projects delivered and seeing the cost optimisation program feed through cleanly into earnings.
The biggest near term risk sits on the other side of that. Intense price competition in commoditised refractories, structural overcapacity at customers and exposure to external alumina and labour costs all leave limited room for execution missteps, especially with debt not well covered by operating cash flow.
The most relevant recent development is the disclosed buying from Man Group and Dimensional Fund Advisors, which together are close to 4% of RHI Magnesita’s share capital. That does not change the operational path, but it does put more outside attention on whether recycling projects, US localisation and automation actually translate into more resilient earnings.
Fresh institutional interest also lands at a moment when the stock trades near sector level P/E multiples and analyst expectations already assume meaningful earnings growth. For you as a shareholder, the key question is whether the circular economy push and cost program can offset pricing pressure and project timing risk without putting extra strain on already stretched cash generation and leverage.
RHI Magnesita is currently framed around analyst expectations that revenue will expand at 3.2% a year, taking total income to about €3.6b and earnings to €211.7 million by 2029, up from €111.0 million today. This implies an earnings increase of roughly €100 million over that period.
Uncover why RHI Magnesita's fair value indicates a 17% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on RHI Magnesita focuses on earnings power if industrial project work really snaps back. The most optimistic analysts were already pencilling in revenue of about €3.7b and earnings near €212.0 million by 2029, which implies a richer P/E. Fresh institutional buying could prompt a reassessment of whether that potential upside story still holds or needs revisiting.
Explore 2 other RHI Magnesita fair value estimates, including one that suggests as much as 144% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your RHI Magnesita research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for RHI Magnesita. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate RHI Magnesita's overall financial health at a glance.
Looking For More RHI Magnesita-Like Investment Ideas?
If RHI Magnesita has sharpened your interest in industrial and materials stories, broaden your watchlist by scanning other businesses through the Simply Wall St Screener. You get the same structured data and visual tools, applied to very different types of opportunities.
- For investors who want quality and value to line up, start with companies that pair robust fundamentals with a discount to intrinsic worth through the 7 high quality undervalued stocks.
- If capital preservation matters as much as upside, focus on businesses with steadier profiles by running results through the 4 resilient stocks with low risk scores.
- To spot potential future leaders before they hit the mainstream, cast a wider net across under-followed ideas using the 5 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com