
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Morgan Sindall Group And 2 Other British Cash Flow Stocks To Watch
Britain is being urged to steer clear of cheap Chinese AI tools because of security and data concerns, which adds more pressure on local firms to fund their own technology and operations. That kind of backdrop puts a premium on solid cash generation. This article looks at three United Kingdom listed companies that appear priced below their long term cash flow potential, based on SWS DCF work.
The three stocks below are just a starter set, and the full screen on Simply Wall St surfaces 23 more companies with equally interesting cash flow stories that are not covered here. To see the wider opportunity, head straight to the Undervalued Stocks Based On Cash Flows screener to identify, analyze, and focus on the ideas that best fit your own criteria.
Morgan Sindall Group (LSE:MGNS)
Morgan Sindall Group brings together construction, regeneration, and housing partnerships, which puts its cash flows close to the heart of this screener’s theme. Partnership Housing in particular links project development with long-term contracts, creating visibility that discounted cash flow models can weigh carefully.
Morgan Sindall Group is a £1.8b construction and regeneration group, with revenue mainly from Fit Out at about £1.9b, Infrastructure at roughly £900 million, and Partnership Housing at around £800 million, plus smaller Mixed Use and other contributions.
"The Group's record-high, rapidly expanding secured order book (up 39% to £12bn) and strong pipeline in both Partnership Housing and Mixed Use indicate forward visibility. However, reliance on these large, long-duration projects also increases exposure to risks of regulatory delays, planning bottlenecks, and changes in government policy."
For investors, what really matters next is how one quiet shift in project economics feeds through into future margins and cash conversion.
That margin story is only half the picture, and the full narrative for Morgan Sindall Group shows how cash conversion, contract mix, and risk could be quietly reshaping Morgan Sindall Group’s valuation profile.
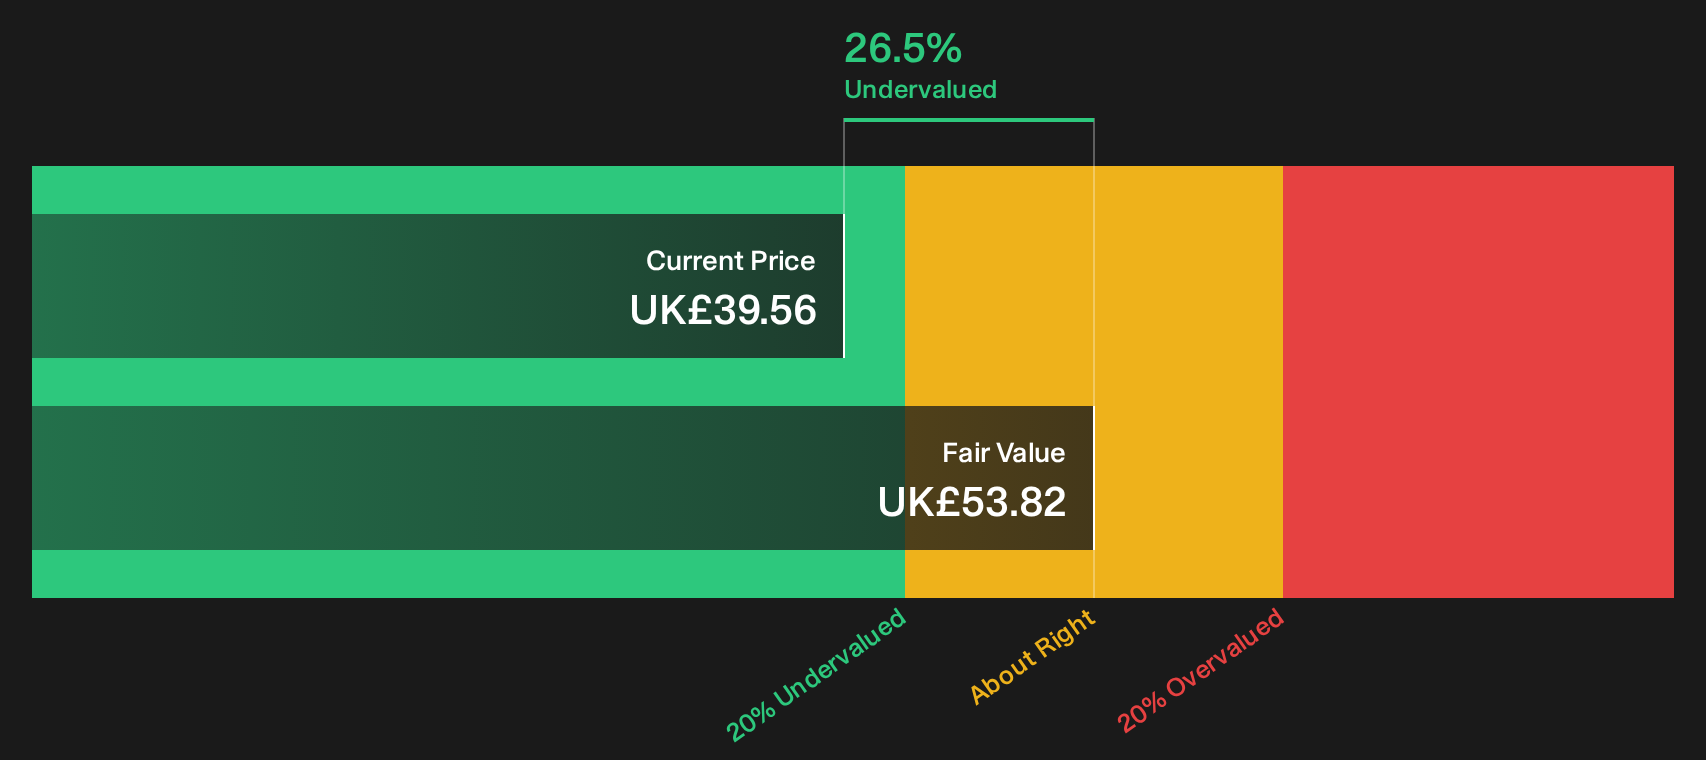
Shell (LSE:SHEL)
Shell is a global energy giant whose cash-flow heavy oil, gas and fuel retail operations fit naturally with a screen that looks for robust free cash generation backed by large, integrated production and refining systems across multiple business lines.
Shell runs a wide energy and petrochemicals platform focused on oil and gas production, LNG, fuel and lubricants retailing, and refining. Most revenue comes from Marketing at about US$134.6b and Chemicals and Products at roughly US$131.8b, while Renewables and Energy Solutions contributes around US$41.8b. The group’s market value is about £225.1b.
"Shell's renewable energy management agreement with Google in the UK is concrete evidence of this strategy."
What really shapes Shell’s cash-flow story now is how one shift in its LNG and trading engine filters through future pricing power.
That LNG shift is only the start, and the full narrative for Shell shows how Shell’s cash engine, capital choices, and transition bets could be quietly decoupling from old oil-cycle playbooks.
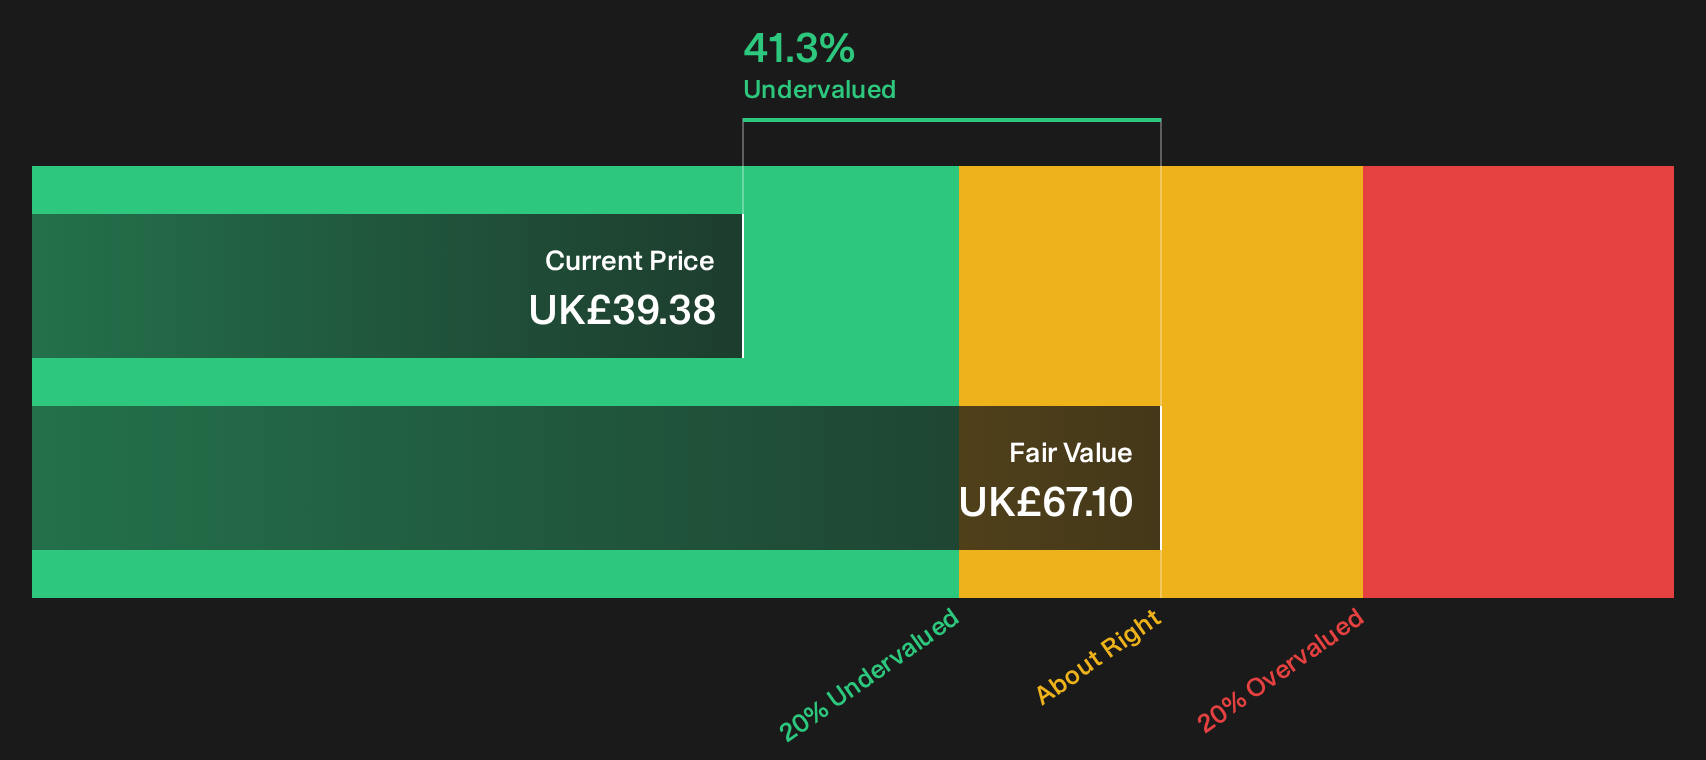
Smith & Nephew (LSE:SN.)
Smith & Nephew is a medical devices group best known for orthopaedic implants and sports medicine tools, while its Advanced Wound Management arm adds repeat-use dressings, bioactive grafts, and negative pressure devices that tie directly to the screener’s cash flow focus.
Orthopaedics generates about $2.5b of annual revenue, Sports Medicine & ENT contributes roughly $2.0b, and Advanced Wound Management adds around $1.8b, with the group valued at about £9.1b on the market today.
For this screener, Smith & Nephew matters because it mixes long-life implants with recurring wound-care products that can support reliable cash generation when hospitals are watching budgets closely.
"Acceleration in new product innovation, such as expanded robotic-assisted surgery (CORI, CORIOGRAPH), new implants (CATALYSTEM Hip, TRIGEN MAX Tibia Nailing), and significantly increased contributions from recent product launches (75% of H1 growth from products <5 years old), is described as positioning the company to capture greater market share and sustain higher long-term revenue growth as global demand for advanced orthopaedic and minimally invasive solutions rises."
The real test will be how one quiet shift in where each new dollar of sales comes from eventually filters through pricing power and margins.
That mix of cash-heavy implants and repeat-use wound care is exactly what the full narrative for Smith & Nephew unpacks. It highlights where accelerating product adoption could reshape Smith & Nephew’s earnings quality.

Curious About What You Might Be Missing?
Fresh ideas often move first. Breakout stories can gain momentum while the most attractive entry points quietly drop away under the radar. Do not get caught late. Consider your options in advance.
- Track resilient cash engines before they start gaining wider attention by scanning the 4 resilient stocks with low risk scores, which focuses on keeping volatility in check while still targeting meaningful upside.
- Spot early AI momentum where revenues come from established business activity rather than promotion by reviewing the curated 39 profitable AI stocks that aren't just burning cash that already generate profits.
- Consider potential infrastructure themes in advance by working through the hand-picked 41 power grid technology and infrastructure stocks, which is aligned with ongoing upgrades to transmission and grid technology.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com