
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Our Pick Of The Best AI Infrastructure Stocks In October 2026
AI is pulling enormous capital into chips and models, yet the quieter story sits in the physical plumbing that keeps those systems running. Anthropic is even talking about a much larger US economy by 2030 as artificial intelligence spreads, which would lean heavily on power, cooling and data centers rather than just clever code. This piece highlights three “picks and shovels” stocks from our screener that plug into that build out.
The stocks covered below are just a quick sample of the theme. The full screen surfaced 52 more AI infrastructure companies with equally compelling stories that are not unpacked here. To identify which of those could fit your portfolio and analyze them side by side, head straight into the AI Infrastructure Stocks screener.
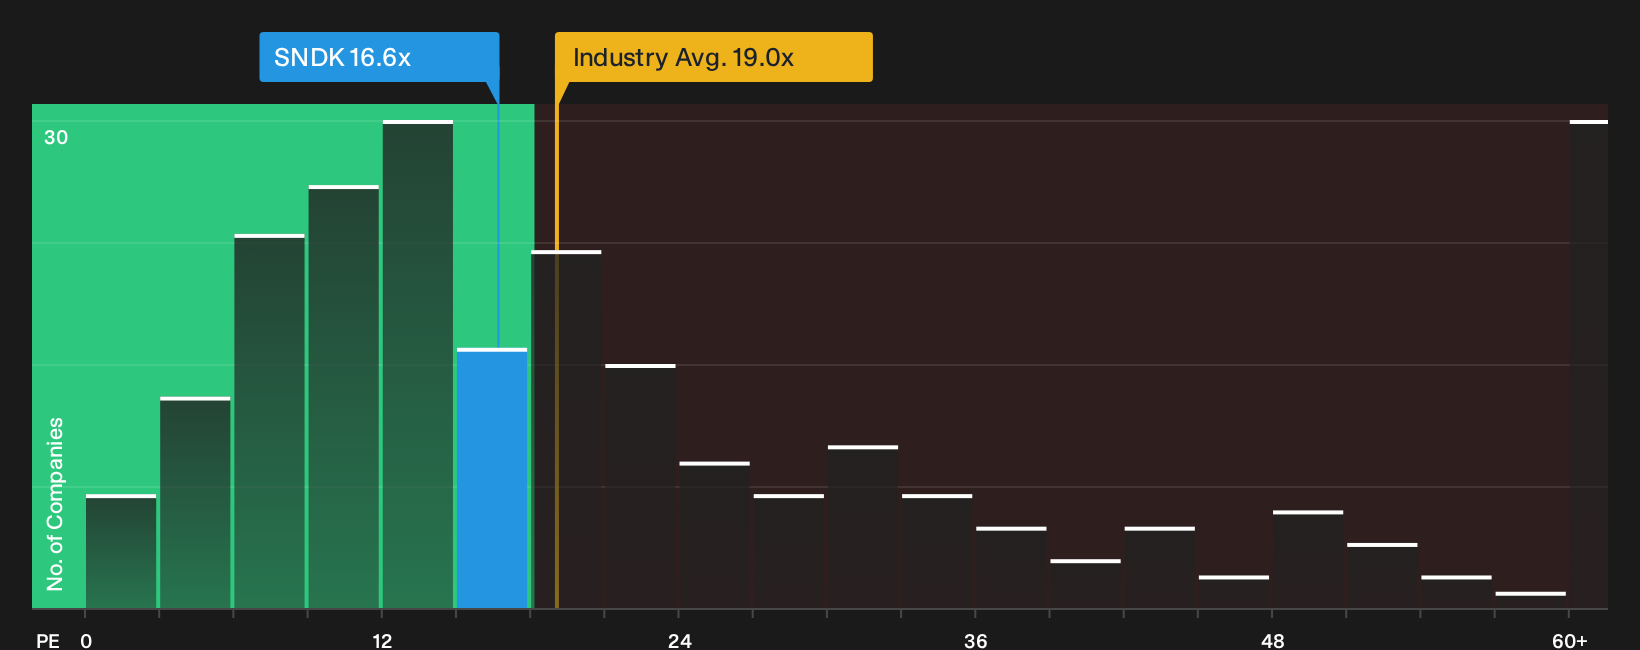
Sandisk (SNDK)
Overview: Sandisk develops and sells NAND flash based solid-state drives and embedded storage that power data centers, cloud AI workloads, and connected devices worldwide.
Operations: Sandisk generates about US$20.2b from data storage devices and solutions, with revenue spread across China, Hong Kong, the wider Asia region, the United States, and EMEA.
Market Cap: US$190.2b
Sandisk matters for this AI infrastructure screen because its enterprise SSDs sit directly in the storage racks that keep training runs and inference clusters fed with data.
"Rapid AI and cloud workload expansion is driving data center NAND exabyte growth at a pace well above overall supply, positioning Sandisk's enterprise SSD portfolio and deepening hyperscaler engagements to support sustained revenue acceleration and structurally higher pricing power."
What happens to that pricing power if a single assumption about future supply discipline or long-term AI storage demand quietly shifts?
If that quiet shift is what worries you, the full narrative for Sandisk explains how Sandisk's AI storage story could evolve if those assumptions start to decouple.
Cerebras Systems (CBRS)
Overview: Cerebras Systems designs wafer scale AI chips and full rack compute systems that help data centers run large AI models at high speed.
Operations: Cerebras Systems generates about US$680.7 million from semiconductors, with roughly US$236.6 million from the United States and US$443.5 million from Europe, the Middle East, and Africa.
Market Cap: US$30.2 billion
Cerebras Systems matters in this AI infrastructure screen because its wafer scale racks turn theoretical AI demand into physical compute capacity inside power hungry data centers.
"In March 2026, AWS integrated Cerebras CS-3 systems directly into Amazon Bedrock, splitting the inference workload so Trainium3 handles the 'prefill' phase while the Cerebras wafer dedicates its massive SRAM bandwidth to the sequential 'decode' phase, yielding up to a 15x speed improvement over monolithic GPU setups."
What happens to Cerebras Systems margins if one quiet assumption about how quickly those ultra fast racks stay fully loaded starts to shift?
If that load risk is on your mind, the full narrative for Cerebras Systems explains how Cerebras Systems could turn utilization swings into an opportunity that supports long-term AI infrastructure demand.

Seagate Technology Holdings (STX)
Overview: Seagate Technology Holdings supplies high-capacity hard drives and SSDs that anchor hyperscale and cloud data centers storing AI training data.
Operations: Seagate generates about US$12.2b from manufacturing and distributing storage solutions, with most sales from the United States, Singapore, and the Netherlands.
Market Cap: US$145.3b
Seagate Technology gives this AI infrastructure screen exposure to the long term storage tier that keeps expanding data lakes and model archives affordable for cloud providers.
"HAMR penetration hitting 50% then 70%. These are dated, specific milestones. They are the cleanest read on engine two, and they are largely independent of the pricing environment."
What happens to Seagate Technology margins if a single quiet assumption about how long that cost edge lasts starts to shift?
If that risk is on your radar, the full narrative for Seagate Technology Holdings explains how Seagate Technology could continue to translate HAMR adoption into stronger cash generation and additional storage share gains.

Seeking Alternatives Before The Crowd?
Fresh breakouts do not wait. Momentum shifts, under the radar for now, can get caught quickly once capital starts flying in. Do your homework while it matters and act now.
- Spot strong balance sheets early and sift through a curated list of solid balance sheet and fundamentals (25 results) before the rest of the market starts chasing quality.
- Track powerful income ideas and review a hand picked 8 dividend fortresses while yields are still high and prices have not fully adjusted.
- Front run the next automation wave and scan the curated 91 robotics and automation stocks before robotics momentum is fully priced into these companies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com