
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is SRG Global (ASX:SRG) Undervalued Following Its Contract Pipeline Update?
SRG Global (ASX:SRG) is back in focus after fresh commentary on its contract-based cash flows and an expanding project pipeline tied to government infrastructure work and long term demographic trends.
The recent pullback, with a 7 day share price return of down 8.62% and a 30 day share price return of down 9.09% to A$3.50, comes after a stronger run earlier in the year. The year to date share price return is 17.45%, while the 1 year total shareholder return of 30.54% and very large 3 year and 5 year total shareholder returns suggest SRG Global has already rewarded patient holders. Momentum has cooled in the short term as investors reassess the contract pipeline and cash flow story.
Expand your watchlist beyond SRG Global by scanning a curated list of solid balance sheet and fundamentals (12 results) that echoes its contract-backed cash flows and infrastructure exposure.
After a sharp multi year run and a short term pullback to A$3.50, SRG Global now sits at a crossroads. Do current valuation signals still justify taking fresh risk on the stock?
Most Popular Narrative: 19% Undervalued
Against the last close at A$3.50, the most followed narrative pegs SRG Global’s fair value at about A$4.32, implying that recent weakness sits against a higher long term assessment built on its contract book and earnings profile.
The company's asset care and maintenance services now generate approximately 80% annuity-style (recurring) earnings, improving predictability of cash flows and underpinning stable, long-term EBITDA and net earnings growth.
Advances in proprietary engineering, digital project management, and process innovation allow SRG Global to deliver superior project outcomes and operational efficiencies, supporting sustained industry-leading EBITDA and EBIT margin performance.
See why 22 investors see SRG Global as 19% undervalued.
Result: Fair Value of A$4.32 (UNDERVALUED)
Still, SRG Global’s reliance on government infrastructure budgets and concentrated blue chip clients could quickly unsettle that undervaluation story if funding or contracts were to shift.
Find out about the key risks to this SRG Global narrative.
Another Take On SRG Global’s Valuation
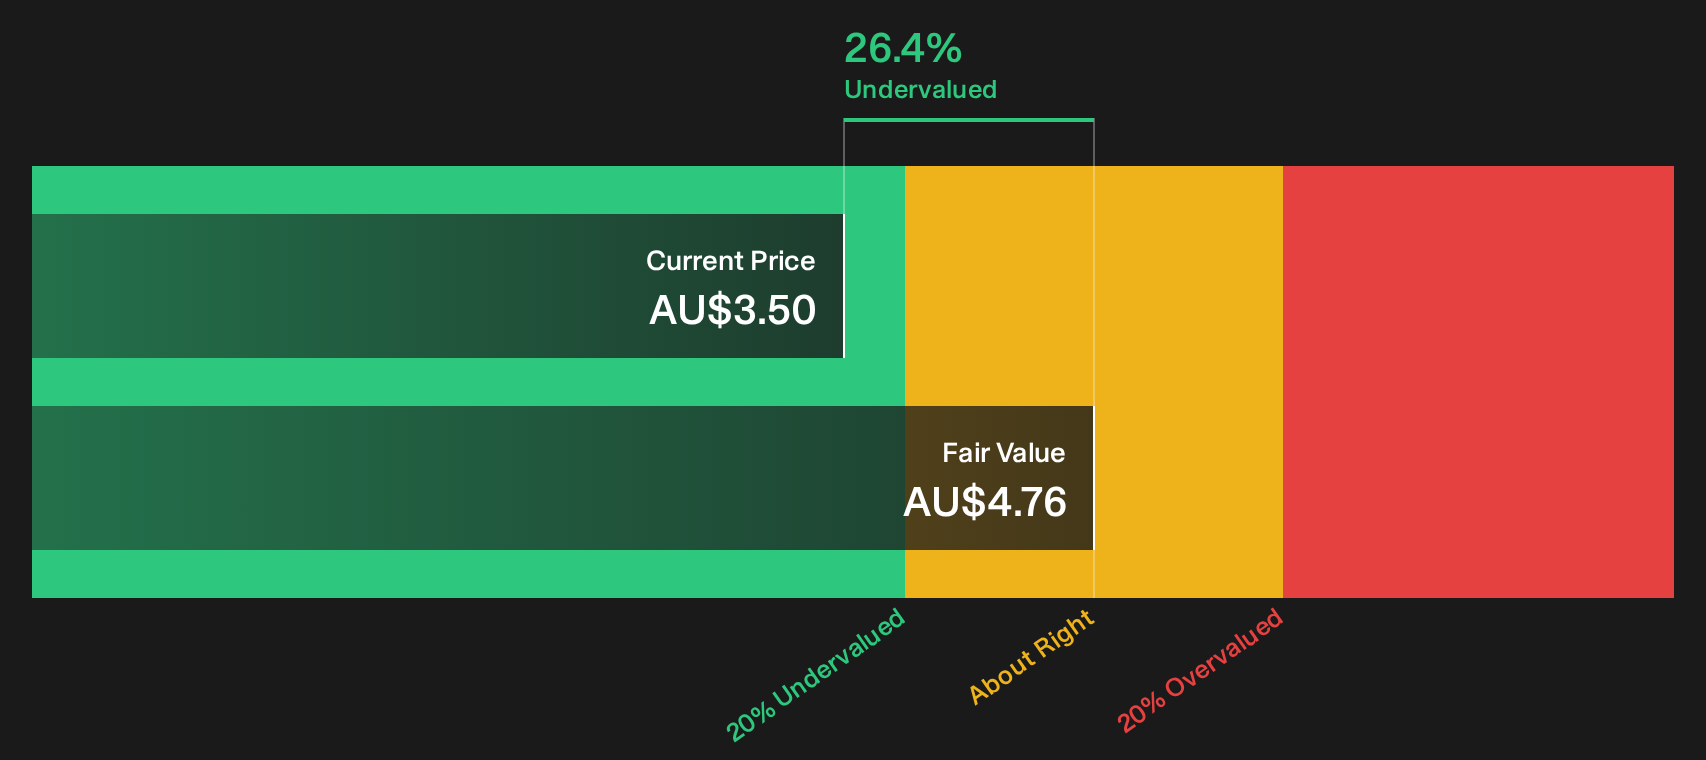
The SWS DCF model offers a second lens. On this view, SRG Global at A$3.50 trades below an estimate of future cash flow value of A$4.76, which also points to the shares being undervalued. If both methods lean the same way, where do you see the biggest flaw in the story?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages on SRG Global’s value case and risk profile call for your own judgment, so move quickly and weigh both sides with the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond SRG Global?
SRG Global gives you one angle on contract-backed earnings, but your portfolio deserves a wider bench of opportunities that match your risk and income goals.
- Target potential mispricings by scanning a focused set of value opportunities using the 4 high quality undervalued stocks.
- Strengthen capital preservation by reviewing a curated pool of resilient businesses through the 6 resilient stocks with low risk scores.
- Boost your income watchlist by zeroing in on yield-heavy opportunities with the 4 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com