
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Global Partners (GLP) Stock Still Seems Cheap After Credit Facility Extension
Global Partners has delivered a strong multi year share price run, and the latest move on its financing raises a fresh question about whether the current valuation is still supported by its earnings power. With the stock now trading at US$49.71, the issue for investors is what that price really assumes about future profit generation.
- Over the past 5 years the stock has returned 211.0%, which puts a lot of weight on the idea that Global Partners' earnings can support a materially higher valuation than in the past.
- The decision to extend the US$1.5b credit facility to 2031 may support steadier cash flow timing and lower near term refinancing pressure, which can influence how investors think about the sustainability of future earnings.
- Would you pay the same price for Global Partners's peers? See how Global Partners's 10.1x P/E compares with its peers.
The issue now is whether Global Partners' current share price is justified by the earnings the business produces today and what investors expect those profits to look like over time.
If you want a reference point for Global Partners' earnings driven story, it helps to line it up next to 33 high quality undervalued stocks.
Does Global Partners Look Undervalued on Earnings?
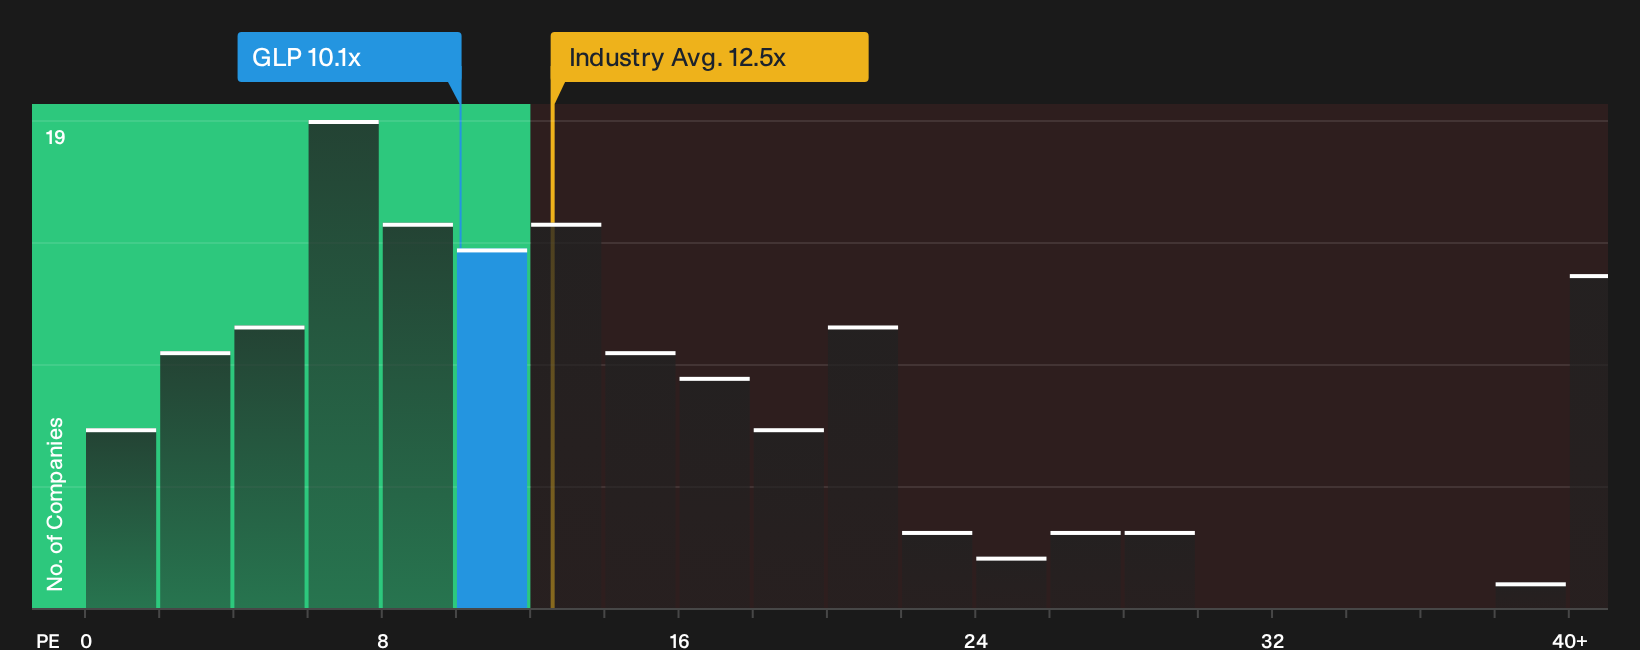
The P/E ratio fits Global Partners because earnings are a key driver for how investors usually think about fuel distribution and related assets. At a current P/E of 10.1x, the stock trades below both the Oil and Gas sector average of 12.5x and the peer group on roughly 14.1x. That places Global Partners on a lower earnings multiple than many comparable businesses at today’s share price.
The fair P/E level implied by the valuation model, which blends the company’s growth profile, margins, risk and scale, sits above the current 10.1x figure, so the stock screens as undervalued on this metric. Because the US$1.5b credit facility has been extended to 2031, some investors may see less refinancing pressure, yet the P/E still points to a discount versus what the model suggests for Global Partners' earnings power. Explore the numbers behind Global Partners's P/E valuation.
The Global Partners Narrative: What Would Justify Today's Price?
Global Partners' valuation puzzle only really comes into focus once you spell out the future that would need to play out for this price to make sense. This is where Simply Wall St Narratives on the Community page come in. Each one turns those assumptions about growth, profitability and earnings durability into a clear thesis that can be revisited over time, so you can see how the fair value case holds up as the business story develops.
One of the top community narratives on Global Partners: 9% overvalued
"Expansion of the company's terminal network through recent acquisitions in key markets is expected to strengthen market presence, enhance distribution efficiency, and support long-term revenue growth from higher throughput volumes."
Discover why this Narrative puts Global Partners at 9% overvalued.
An unresolved question for Global Partners
The valuation work only tells part of the story for Global Partners, since Simply Wall St’s broader review has also flagged specific concerns that careful investors may want to weigh before drawing conclusions. Take a closer look at 3 warning signs (2 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com