
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
China Export Shift Might Change The Case For Investing In CAR Group Stock (ASX:CAR)
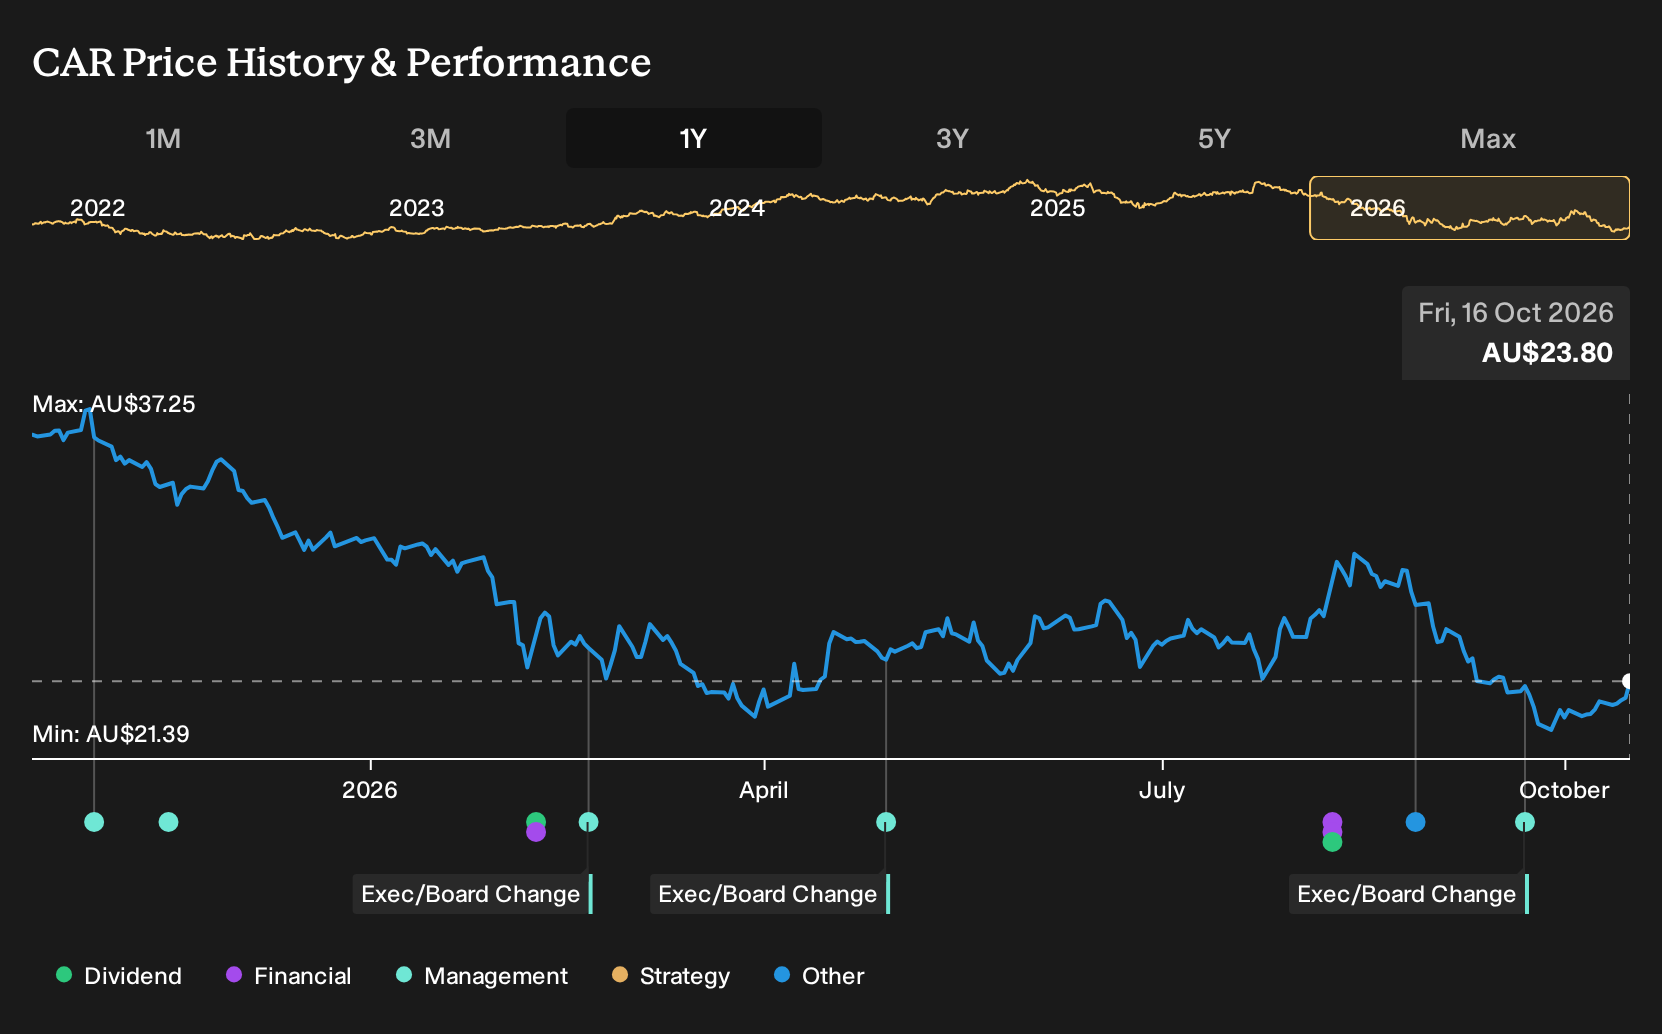
- CAR Group faces pressure on long-term cash generation as investors reassess its future transaction volumes and cash inflows after a 31.4% share price decline over the past year.
- China's move to moderate hybrid vehicle exports to Europe brings an extra layer of uncertainty for CAR Group's global marketplace activity and fee-based income.
- We now assess how CAR Group's investment narrative holds up in light of fresh concerns about its long-term cash flow potential.
Compare how CAR Group stacks up against other opportunities by scanning a curated set of 4 high quality undervalued stocks that may also be pricing in heavy market caution around long-term cash flow.
CAR Group Investment Narrative Recap
To own CAR Group, you need to believe its global classifieds and data platforms can keep drawing vehicle buyers and sellers even as transaction volumes move around. In the short term, the focus is on whether softer sentiment around hybrids and exports actually dents listing activity or simply shifts the mix between markets. The recent news appears more like an added headwind than a thesis breaker.
Right now, the key catalyst is execution on higher margin digital products and adjacent services that support cash generation even if volumes stay muted. The biggest risk is that dealers and manufacturers pull back advertising spend or experiment more with direct channels and alternative mobility. This would expose CAR Group's reliance on listing and advertising fees.
With no fresh company announcements directly tied to the moderation in China hybrid exports, the most relevant reference point remains CAR Group's broad push into subscriptions, finance, insurance and data products. Those efforts are intended to spread revenue beyond pure listing volumes and give the business more ways to earn from each transaction.
For investors, the operational question is whether these adjacent services can offset pressure if cross border vehicle flows or European volumes remain softer for an extended period. Execution risk lies in integration and product uptake across regions such as Brazil, Korea and North America, where penetration remains relatively low and the ongoing digital shift underpins the case for continued platform usage.
Analysts expect CAR Group's revenue to reach A$1.6b and earnings to land at A$464.1 million by 2029, which reflects a 9.8% yearly revenue growth assumption and an earnings increase of about A$168.7 million from A$295.4 million today.
Uncover why CAR Group's fair value indicates a 38% potential upside to its current price that could close faster than investors expect.
Exploring Other Perspectives
Fair value opinions on CAR Group from four Simply Wall St Community members cluster between A$32 and about A$33.93, which signals a relatively tight band even before factoring in the China hybrid export news. You can weigh that against risks around EV adoption, alternative mobility and rising digital competition, then compare several contrasting views for yourself.
Explore 3 other CAR Group fair value estimates, including one that suggests as much as 43% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your CAR Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CAR Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CAR Group's overall financial health at a glance.
Looking for more CAR Group investment ideas?
If you want to stress test your view on CAR Group, compare it with other businesses facing similar questions around cash generation, balance sheet strength and income potential using the Simply Wall St Screener.
- For investors hunting for mispriced quality, scan a curated set of 4 high quality undervalued stocks that combine stronger fundamentals with cautious market expectations.
- If capital preservation ranks high on your checklist, filter for stability and resilience by reviewing a 6 resilient stocks with low risk scores that may better match your risk tolerance.
- Income focused readers can broaden their watchlist by assessing a hand picked 4 dividend fortresses that aim to pair higher yields with more durable payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com