
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Nordson (NDSN) Following Its Run Higher Faces A Fair Value Reality Check
Nordson stock moves and recent performance snapshot
Nordson (NDSN) has been drawing attention after recent share moves, with the stock closing at US$322.31. Investors are weighing that price against the company’s multi segment industrial and medical dispensing business.
Recent trading has cooled slightly, with the share price down 1.9% over the past day and 1.8% over the past week. However, Nordson still carries clear positive momentum given its 11.5% 90 day share price return and 33.7% year to date gain, supported by a 39.9% 1 year total shareholder return.
Scan for other industrials that exhibit similar momentum and financial resilience using the hand picked list of solid balance sheet and fundamentals (25 results), which reflects some of Nordson's quality traits.
The recent surge in Nordson, along with only a mild pullback this week, raises a practical question for you: Is it worth paying up now, or does waiting for a cheaper entry make more sense based on the valuation math?
Most Popular Narrative: 8% Undervalued
Nordson’s most followed narrative pegs fair value at $349.71, which sits modestly above the latest close at $322.31 and frames the current price as requiring steady execution rather than a big re rating.
The current numbers and guidance, together with this narrative’s view that Nordson is fairly valued but positive, indicate a share price that already reflects a significant degree of execution on growth, margin resilience and cash generation, with potential gains linked to continued delivery rather than a change in valuation multiples.
See why 14 investors see Nordson as 8% undervalued.
Result: Fair Value of $349.71 (UNDERVALUED)
Still, this Nordson narrative can be unsettled if the heavier tilt toward semiconductor and electronics, or the high free cash flow profile, leads investors to assign a richer P/E multiple.
Find out about the key risks to this Nordson narrative.
Another View: What Nordson’s P/E Is Really Saying
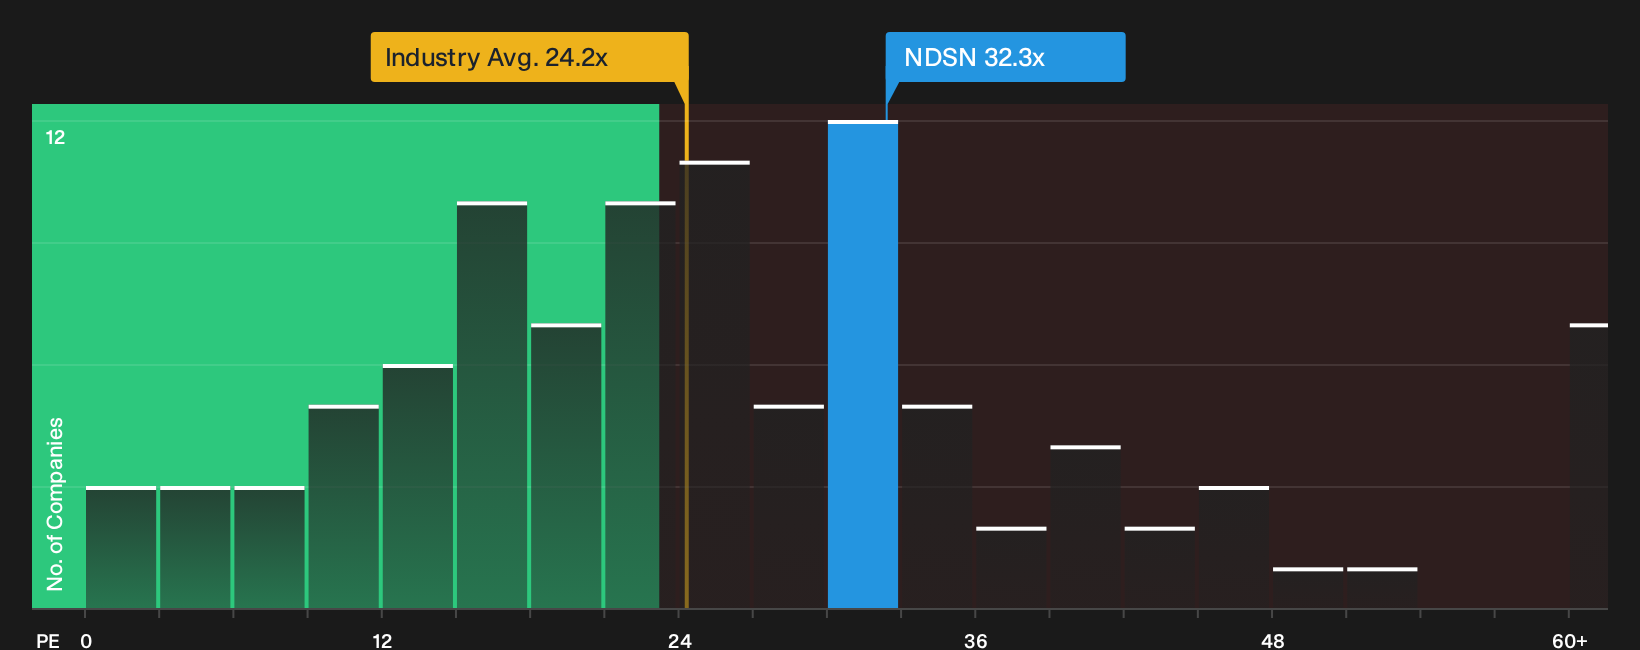
Nordson screens differently once you move from fair value narratives to the straight P/E math. The shares trade on 32.3x earnings, which is below the 35.7x peer average yet well above both the US Machinery group at 24.2x and a fair ratio of 22.3x.
That mix of relative cheapness versus peers but a premium to the wider industry and the fair ratio points to real valuation risk if expectations cool. It also gives you a clear question to answer before adding exposure: whether you think Nordson can keep justifying a P/E that far above where the market could move the ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nordson for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Nordson’s recent run and valuation questions split opinion. This is exactly why it helps to act quickly and test the numbers yourself against both the risks and the rewards. To weigh those trade offs in one place, start with the 2 key rewards and 1 important warning sign
Looking for more Nordson style investment ideas?
If you stop at Nordson, you risk missing other quality opportunities that fit your style, so keep scouting and let the data do the heavy lifting.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (25 results) that filters for financial strength first.
- Hunt for potential value opportunities where quality and pricing meet by running the 33 high quality undervalued stocks tailored to those criteria.
- Lock in ideas for income focused portfolios by reviewing a focused 8 dividend fortresses built around higher yielding payout profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com