
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Teck Resources Shareholders Got Right
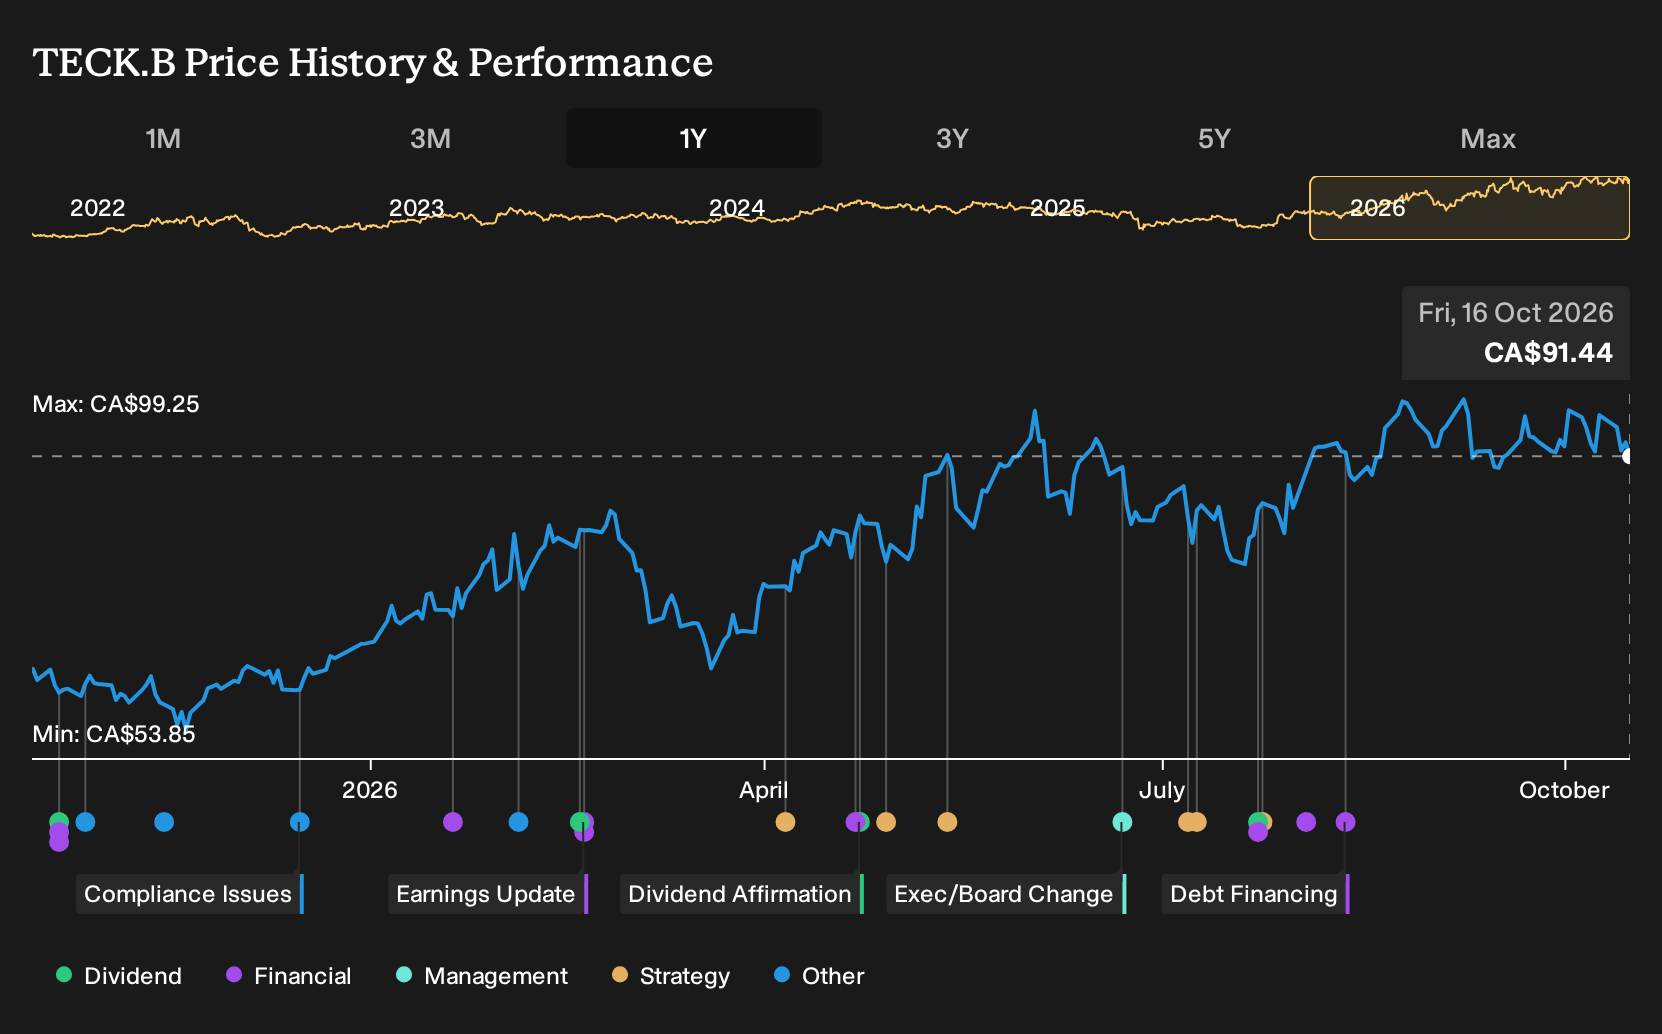
If you had been weighing Teck Resources on 16 October 2025, the debate was sharp. Bulls pointed to copper, decarbonization and a cleaner balance sheet. Bears worried about Highland Valley delays, cost creep and regulatory friction. For Teck Resources shareholders, the return over the past year was 51.6%, including dividends. If you were deciding whether to buy that day, how would you have weighed copper upside against execution risk and permit headaches?
Teck Resources has already moved. Pinpoint other ways to investigate the theme among 17 top copper producer stocks.
The Argument Teck Resources Investors Were Actually Having
The shares cost CA$62.25 at the start of the period, and Teck Resources sat between two sharply different stories about copper and project risk.
The bullish narrative argued for a Fair Value of CA$68.09, a price that would only make sense if its copper pivot and decarbonization tailwinds played out, including an assumption that revenue could grow 8.9% a year for three years.
The bearish case pointed to a Fair Value of CA$50, based on worries that Highland Valley delays and broader permitting friction might keep revenue growth to just 0.8% and limit margins to 7.2% in that same timeframe.
What The Results Changed For The Teck Resources Debate
Teck Resources then reported Q2 2026 revenue of C$3,605m and net income of C$854m, with net margin rising from 10.2% to 23.7%. That profitability shift supported the bullish view that copper focused execution could lift earnings power, although it did not directly resolve earlier worries about Highland Valley permitting or long term demand.
The lesson is clear. When a thesis hinges on better margins, do not stop at revenue. Track net margin and absolute profit in later filings and see whether they move toward the scenario investors were originally debating.
What Teck Resources' Price Already Assumes
Teck Resources now trades at CA$91.44 after a 51.6% gain over the past year, while the selected Narrative’s Fair Value sits below the current price.
That view leans on heavy copper spending, merger execution and mature asset costs. A buyer today is effectively assuming the copper focused portfolio delivers durable volumes and margins. How does concentrated peak capex risk affect that bet?
"The main factor that has to go right is that the copper heavy portfolio, including QB, Highland Valley and the Anglo Teck merger, delivers stable volumes and attractive margins once the current peak investment phase passes. The current numbers and independent assessments that describe the stock as slightly overvalued or fairly valued indicate that much of the expected copper and byproduct upside is already reflected in Teck Resources' share price."
The price and this Narrative do not agree. → Uncover what this Narrative says Teck Resources is actually worth
Teck Resources And A Different Metal Question
Teck Resources represents one path into the critical materials story. You can also look slightly aside and ask where shortages feel sharpest.
Defense and chip production both depend on a metalloid that rarely made headlines until supply was disrupted. Western buyers saw how fragile that chain was when a single country controlled mining and refining.
One small explorer is testing another approach. It has assembled ground near long producing deposits for this metalloid and a related hardening material.
The idea is straightforward. If allied governments keep backing domestic supply, even early drill results could take on outsized importance.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 96% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com