
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
DIC (TSE:4631) Could Be 70% Below Fair Value Following ECOVART Ink Rollout
DIC (TSE:4631) has put its ECOVART gravure ink into global rollout, targeting Japan, China and Southeast Asia, as packaging customers look for lower solvent use and tighter environmental compliance.
That ECOVART rollout lands at a time when DIC’s share price has been gathering pace, with a 30-day share price return of 4.52% and a 90-day gain of 14.09%. The year-to-date share price return of 39.45% sits alongside a 1-year total shareholder return of 49.09% and a 3-year total shareholder return of 137.76%, pointing to momentum that investors will be weighing against the opportunity and risk in its sustainability focused products and exposure to cosmetic pigments.
Scan beyond DIC and explore other materials and chemicals stocks that are leaning into sustainability tailwinds with our hand picked 73 high quality undiscovered gems.
The recent three-month surge in DIC highlights what has already gone right. The real puzzle now is how much of the value story is still on the table.
Price-to-Earnings of 8.5x: Is it justified?
DIC closed at ¥5,062, and on a P/E of 8.5x it is priced well below several benchmarks that investors often watch for chemicals stocks.
The P/E ratio links the share price to reported earnings and gives you a quick read on how much you are paying for each unit of profit. For a mature materials group like DIC, which already has established product lines in inks, pigments, and resins, this kind of earnings-based yardstick often carries more weight than pure revenue multiples.
On the numbers provided, the stock trades on a P/E of 8.5x. That level is materially lower than the estimated fair P/E of 13.8x that our model suggests the market could move towards. It also sits well below the peer average of 18.6x and the JP Chemicals industry average of 13.1x. This points to the market assigning a clear discount despite the recent share price strength.
Explore the SWS fair ratio for DIC.
Result: Price-to-Earnings of 8.5x (UNDERVALUED)
Still, DIC faces real pressure if regulatory demands raise compliance costs faster than its ability to adjust prices, or if specialty pigments and resins see weaker customer budgets.
Find out about the key risks to this DIC narrative.
Another look at DIC using cash flows
On earnings multiples DIC looks inexpensive, yet the SWS DCF model values the shares at ¥8,613.77 per share versus the current ¥5,062 price. That is a large gap based on projected cash flows, and the key issue is how comfortable investors are with the assumptions behind the model.
Look into how the SWS DCF model arrives at its fair value.
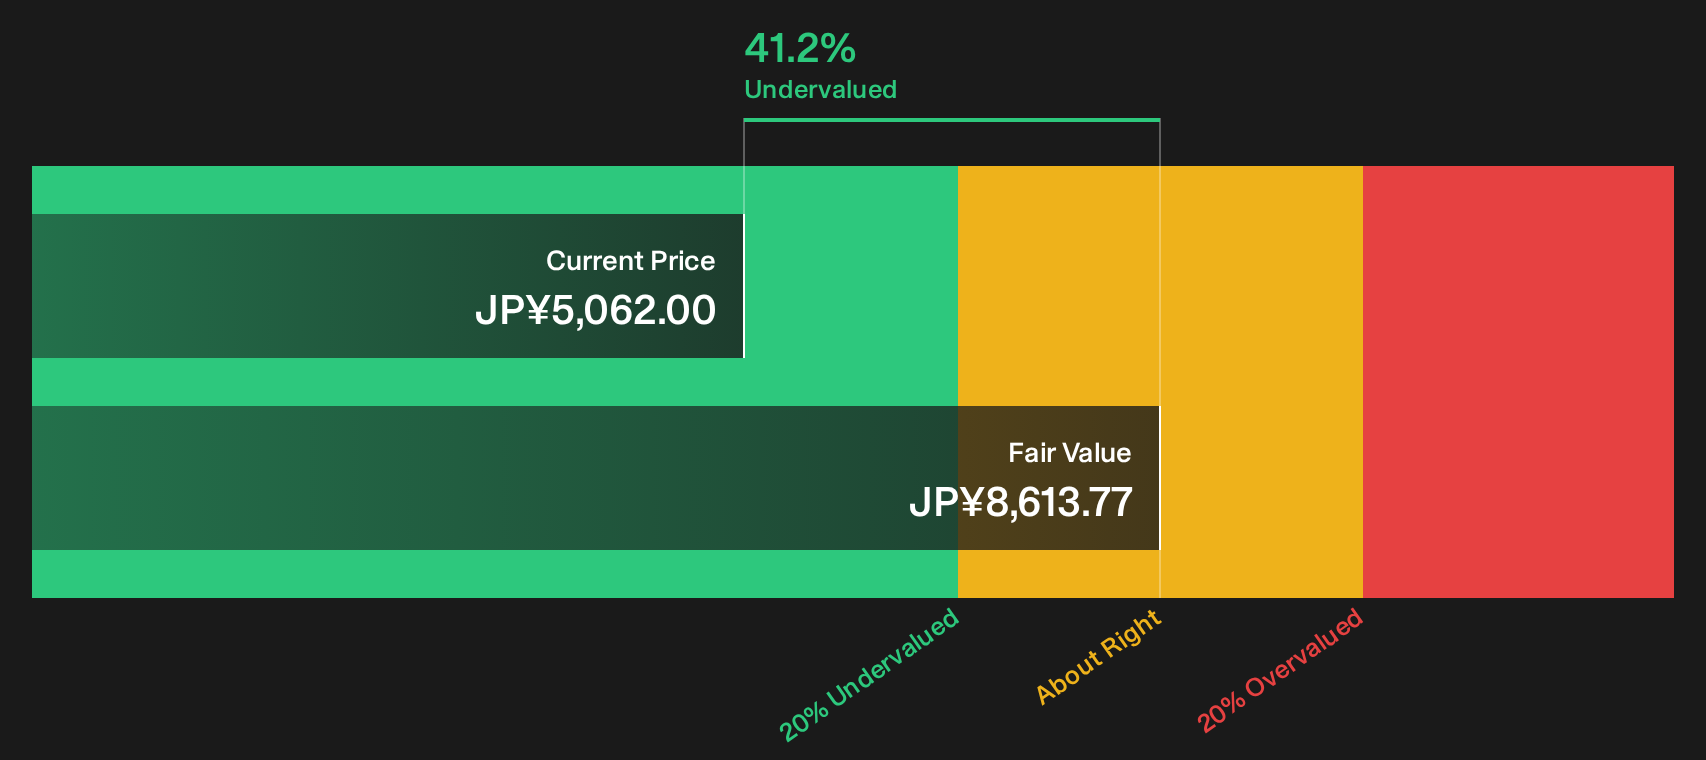
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DIC for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals in DIC’s story are exactly why fresh eyes matter, so move quickly, review the numbers and weigh both the potential upside and the clear red flags with the 4 key rewards and 3 important warning signs.
Looking for more DIC-sized opportunities?
If you stop with DIC, you risk missing other ideas the numbers already point to, so widen your net with a few focused screeners.
- Target potential upside with disciplined valuation by scanning the 13 high quality undervalued stocks that match your risk and return preferences.
- Anchor your portfolio with income ideas by reviewing the 29 dividend fortresses that combine yield with underlying business strength.
- Protect your downside first and then seek upside by filtering for the 23 resilient stocks with low risk scores that still offer room for future gains.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com