
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Where Does Kraft Heinz (KHC) Value Sit As Sales Face Pressure?
Kraft Heinz has been working through a drawn out reset, and the share price today puts a sharper spotlight on what investors are paying for its sales. With the stock still reflecting multi year share price pressure, the live question is whether current revenue levels justify where the market has marked the company.
- Over the past 5 years the stock has fallen 16.2%. This keeps attention firmly on whether the underlying sales base can support even the current valuation, let alone any recovery hopes.
- The decision to ramp up a US$700 million turnaround program while accepting lower expected profits by 2026 can reshape how much of every dollar of sales ultimately turns into cash for shareholders.
- There is a second opinion on Kraft Heinz worth weighing. See what analysts think Kraft Heinz's shares could be worth.
The issue now is whether Kraft Heinz's current share price is adequately supported by the scale and quality of its sales today.
If you are weighing whether Kraft Heinz's current price matches the strength of its sales, it can help to compare that question across 33 high quality undervalued stocks.
Is Kraft Heinz Fairly Priced on Sales?
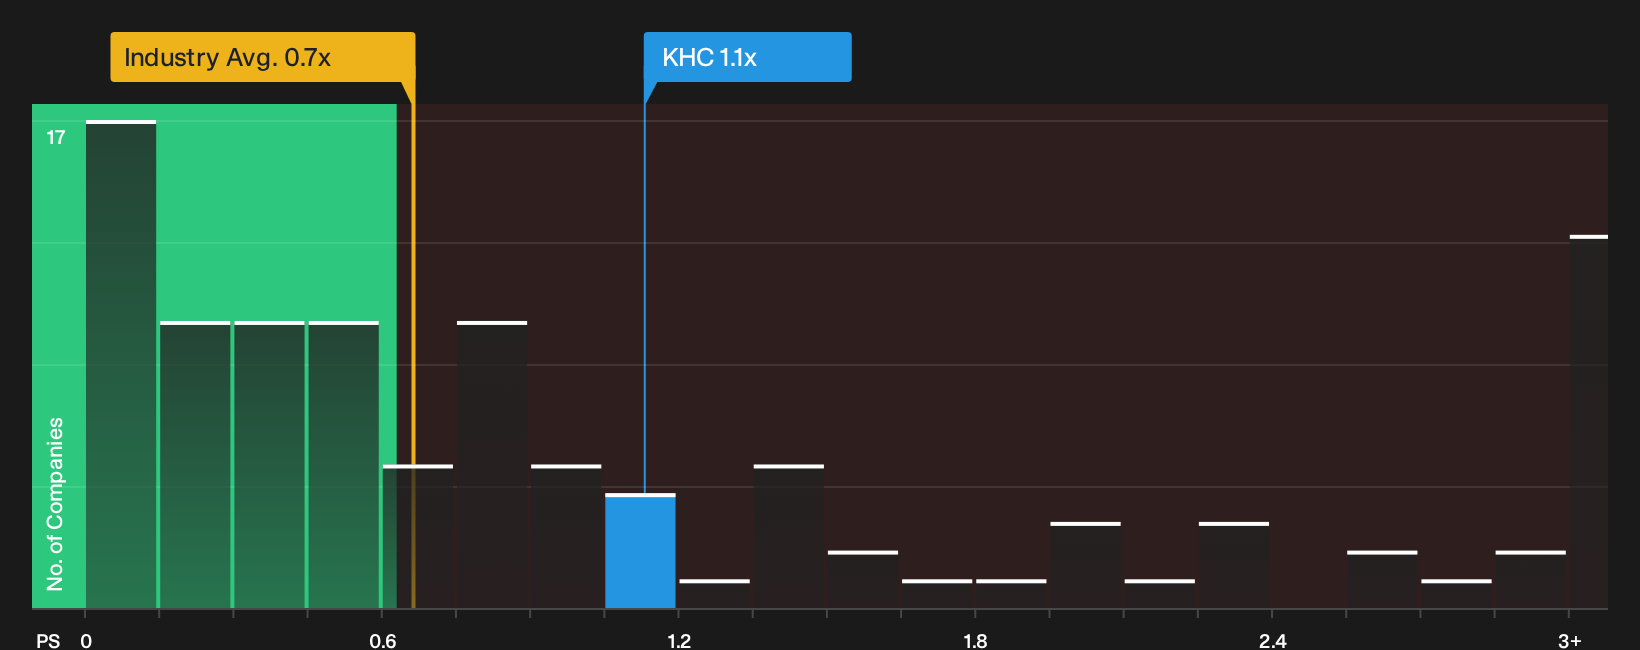
P/S matters for Kraft Heinz because it ties the value of the equity directly to what the supermarket shelf can reliably sell. The stock trades on a P/S ratio of 1.1x, compared with a food industry average of 0.7x and a peer group around 1.4x. In other words, the market is asking you to pay somewhat more per dollar of revenue than the sector overall, but a bit less than closer comparables.
Because the fair P/S multiple that accounts for Kraft Heinz's margins, size and risk profile sits close to the current 1.1x mark, this ratio on its own points to a price that is about right on sales rather than clearly cheap or expensive. The decision to increase a US$700m turnaround program and accept lower expected profits by 2026 means investors are effectively paying this revenue multiple while management is still working to prove that future cash and earnings can match it. Explore the numbers behind Kraft Heinz's P/S valuation.
The Kraft Heinz Narrative: What Would Justify Today's Price?
Kraft Heinz's Simply Wall St Narratives pick up where the P/S puzzle leaves off and explain which specific assumptions on growth, profitability and earnings need to hold for the stock to be worth meaningfully more or less than it is today. They appear on the Community page as a set of clear scenarios that you can read as ongoing testable theses about the business rather than a one off snapshot.
Bulls and bears on Kraft Heinz are looking at the same brands and cash flows but reach very different conclusions on what that is worth.
Bull case: 32% undervalued
"A stable dividend, strong free cash flow, improving share trends, continued productivity, and a renewed willingness to invest behind the brands can go a long way..."
Discover why this Narrative puts Kraft Heinz at 32% undervalued.
Bear case: 25% overvalued
"Although Kraft Heinz is lifting brand, marketing and R&D spend to a new base level, the risk is that higher promotion intensity simply defends share rather than reverses volume declines..."
Explore why this Narrative puts Kraft Heinz at 25% overvalued.
One more Kraft Heinz puzzle worth checking
Everything so far has focused on what Kraft Heinz looks like today, but there is a separate lens that compares this price with where professionals think the business could be a few years from now. Explore where analysts expect Kraft Heinz to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com