
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Eton Pharmaceuticals (ETON) Draws Fresh Valuation Focus, Is It Still A Bargain?
Eton Pharmaceuticals (ETON) has drawn fresh attention after recent trading left the share price at $50.31. This move comes alongside reported annual revenue of $105.595 million and net income of $12.688 million.
Recent trading has cooled some of the earlier heat in Eton Pharmaceuticals, with the share price down 8.88% over the past week and 9.35% over the past month. However, the 90 day share price return of 22.5% and a 1 year total shareholder return of 176.73% point to strong longer term momentum that is still being digested by the market.
Scan rare disease peers showing similar momentum to Eton Pharmaceuticals by reviewing the hand-picked 20 high quality undiscovered gems that match this blend of revenue scale, profitability, and recent share price strength.
After a 176.73% 1 year total return and fresh weakness in recent sessions, Eton Pharmaceuticals now forces a sharper question: Does the current valuation still leave enough upside to justify the risk buyers take from here?
Most Popular Narrative: 29% Undervalued
At a last close of $50.31 against a narrative fair value of $71, the current pricing of Eton Pharmaceuticals reflects a wide gap that analysts link to how quickly its rare disease portfolio can scale.
The company's focus on acquiring and developing therapies aligned with long-term demographic trends such as an aging population and rising prevalence of chronic and rare diseases provides a robust runway for multi-year revenue and earnings growth, supporting the case that current valuation does not fully reflect Eton's future financial potential.
See why 16 investors see Eton Pharmaceuticals as 29% undervalued.
Result: Fair Value of $71 (UNDERVALUED)
Still, the bullish Eton Pharmaceuticals narrative leans heavily on a concentrated rare disease portfolio and on regulatory outcomes that could shift if studies or approvals disappoint.
Find out about the key risks to this Eton Pharmaceuticals narrative.
Another View: What Eton Pharmaceuticals' P/E Is Saying
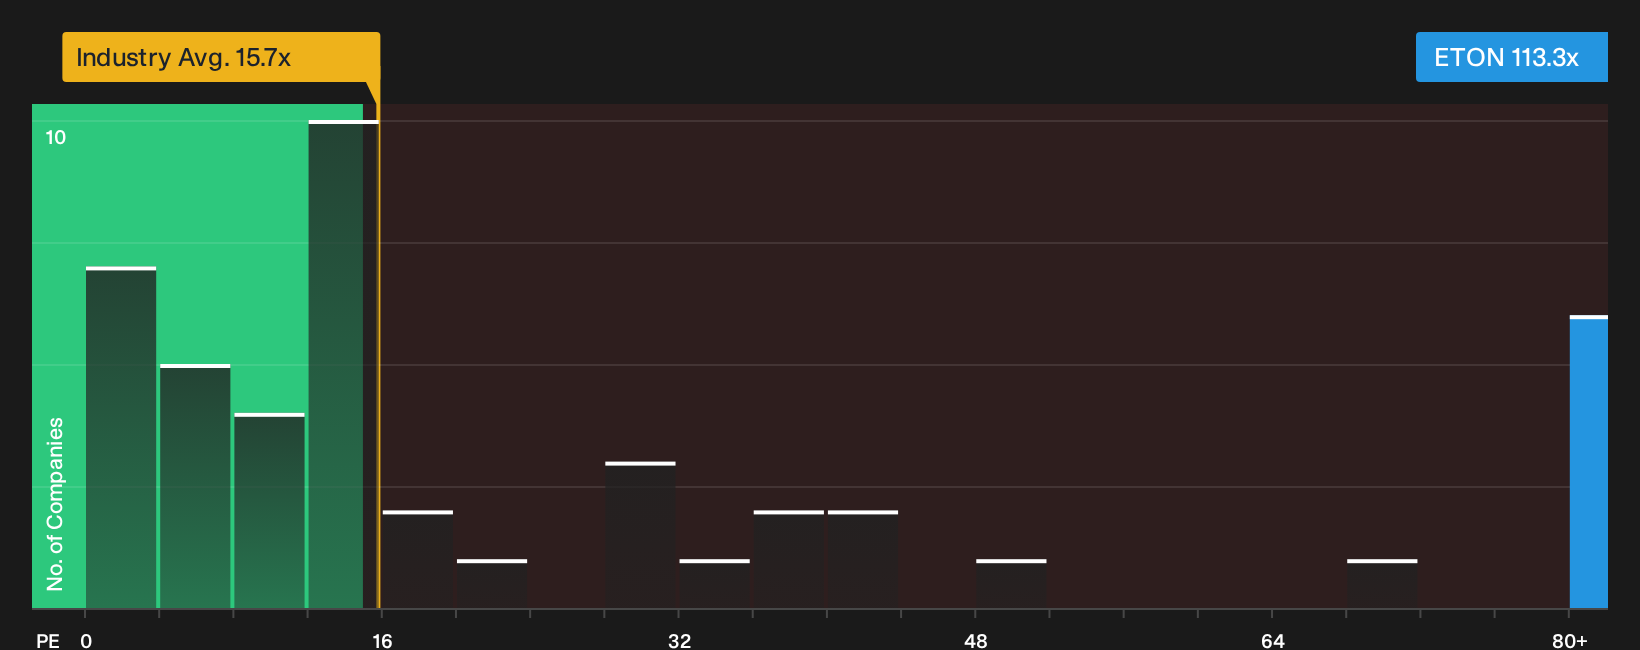
The rare disease story paints Eton Pharmaceuticals as undervalued on fair value estimates, yet the current P/E of 113.3x tells a very different story. That ratio is far above the US pharmaceuticals sector on 15.7x and well beyond peers on 11.9x.
The fair ratio sits at 30.7x, which is less than a third of where the shares trade today. If the market gravitates closer to that fair ratio, valuation risk sits firmly with anyone paying up at current multiples. The real question is which lens you trust more when you size your exposure.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Eton Pharmaceuticals valuation and risk profile make this a judgment call, so move quickly, pressure test the data, and then weigh the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Eton Pharmaceuticals?
If Eton Pharmaceuticals has your attention but you want a wider watchlist, use the Simply Wall St Screener to spot fresh opportunities before they move.
- Target potential mispricing by reviewing companies that screen as high quality yet overlooked through the 33 high quality undervalued stocks.
- Strengthen your downside protection by focusing on businesses that feature on the list of solid balance sheet and fundamentals (25 results).
- Lower portfolio stress by concentrating on companies that pass the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com