
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Moody's (MCO) Is Reworking How It Assesses Credit Risk
- Moody's (NYSE:MCO) is overhauling its credit risk framework to reflect a macro backdrop of higher interest rates and persistent inflation.
- The firm's chief credit officer outlined a sharper focus on corporate leverage, pricing power, and geopolitical exposure in credit reviews.
- Moody's plans to adjust methodologies, product design, and client messaging so its ratings better capture long-term funding and cost pressures.
- This rethink of credit risk in a higher rate, higher inflation world is important, but investors should weigh other Moody's factors too. We have also flagged 1 warning sign for Moody's.
For readers who want more ideas linked to changing credit conditions and data-driven analysis, consider exploring 38 profitable AI stocks that aren't just burning cash.
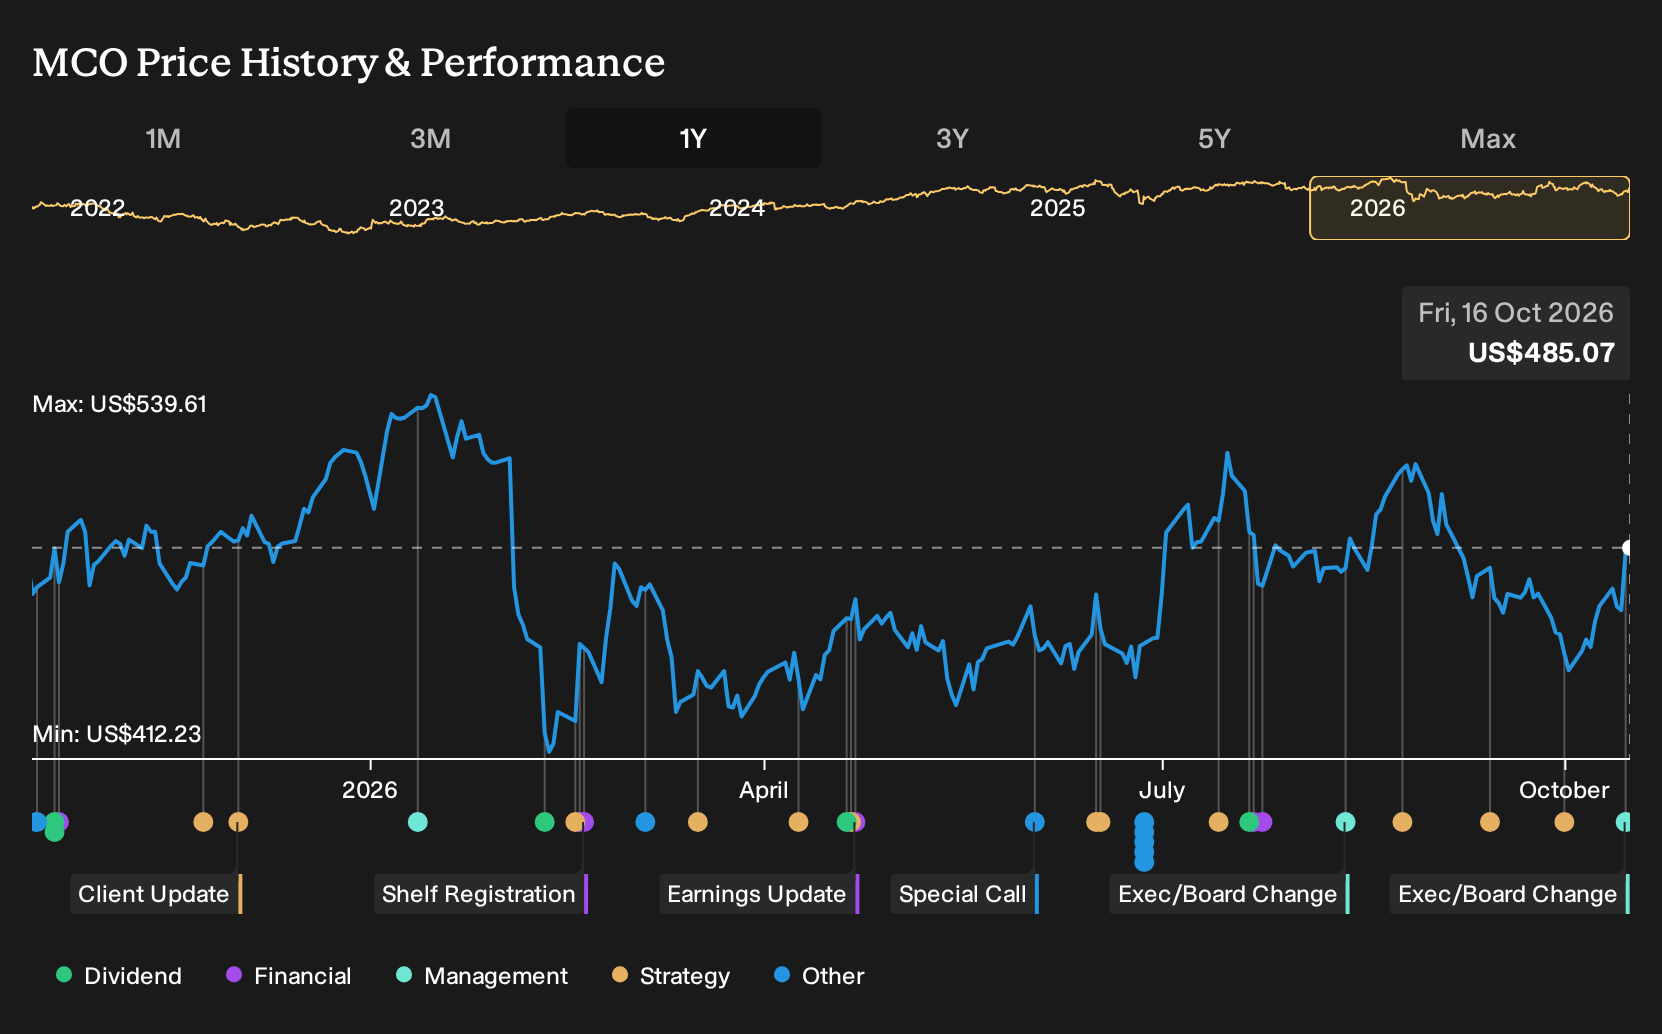
Moody's, a US based risk assessment group with an integrated presence across the Americas, Europe, the Middle East, Africa, and Asia Pacific, sits at the center of how creditors benchmark corporate and sovereign risk. As a result, shifts in its framework can influence how funding costs are assessed across global capital markets.
Moody's credit rethink leans into its AI and private credit Narrative, but execution risk remains
For investors, Moody's decision to retool its credit risk framework in a world of higher rates and persistent inflation broadly lines up with the existing Narrative. The focus on leverage, pricing power and geopolitical risk supports the idea that creditors and regulators will keep leaning on independent ratings and analytics, one of the key demand drivers analysts highlight. It also connects to Moody's push to embed decision grade data inside AI tools and private credit workflows, where more granular risk views are central to the story.
See how these catalysts shape Moody's path to a $562 fair value.
The unresolved piece is execution. Investors will want to see upcoming earnings calls and guidance updates spell out how the new framework feeds into Moody's Analytics annual recurring revenue disclosure and the US$300m to US$350m AI related cost saving targets, rather than just appearing as a theoretical methodology shift.
Add Moody's to your Watchlist and get alerts as these catalysts play out.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com