
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Waste Connections (WCN) Could Be 15% Undervalued As Bernstein Backs The Shares
Analyst call puts Waste Connections in the spotlight
Bernstein’s decision to name Waste Connections (WCN) its top pick in U.S. waste management has thrown fresh attention on the stock, with the firm highlighting pricing, recycled commodities, and oil-linked waste operations.
Waste Connections’ share price has recently picked up, with a 7 day share price return of 9.9% and a 30 day gain of 8.1%. However, the 90 day share price return is down 1.7%, and the 1 year total shareholder return is slightly negative at 2.1%. This is despite a stronger 3 year total shareholder return of 25.8% and 5 year total shareholder return of 29.8%.
Scan how Waste Connections stacks up against other potential winners in the sector with a curated list of list of solid balance sheet and fundamentals (25 results).
Waste Connections now trades at a meaningful discount to both analyst targets and some estimates of fair value after its sharp rebound. Is this genuine mispricing, or is it the market’s way of flagging real risks ahead of the valuation work to come?
Most Popular Narrative: 15% Undervalued
Waste Connections closed at $167.90, while the most followed narrative anchors fair value at $197.40. This frames a material valuation gap built on cash flow and margin assumptions rather than short term trading swings.
The AI and broader digital initiative set, including the already deployed commercial pricing tool, a routing system now in pilot and customer service applications scheduled for rollout through 2027, is described by management as having the potential to deliver up to about 100 basis points of EBITDA margin uplift as these projects move from upfront spending to full operational impact.
Renewable natural gas projects, where about one third of the portfolio was already operating entering 2026 and all 12 planned plants are expected to be online by early next year with RNG capital outlays essentially complete by year end, are presented as being positioned to shift from a capital outflow to a new earnings and free cash flow contributor from 2027.
See why 19 investors see Waste Connections as 15% undervalued.
Result: Fair Value of $197.40 (UNDERVALUED)
Still, the Waste Connections story can be knocked off course if Chiquita Canyon cash outflows run above guidance or if fuel costs squeeze margins for longer than analysts model.
Find out about the key risks to this Waste Connections narrative.
Another View: What Waste Connections’ P/E Is Telling You
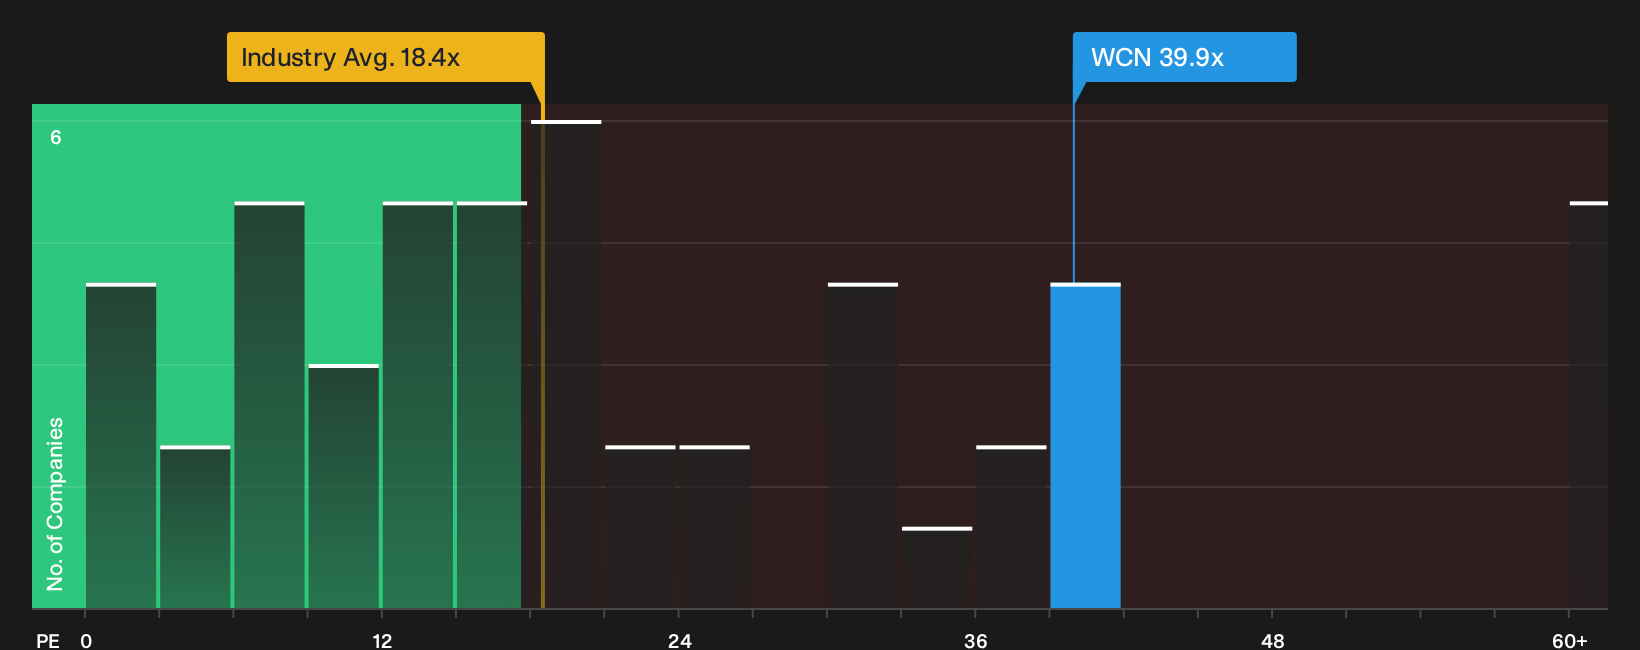
The first fair value story paints Waste Connections as 39% undervalued based on cash flows. The P/E picture is very different. At about 39.9x earnings, the shares trade well above the Commercial Services industry on 18.4x and the peer group near 31.9x, while the fair ratio sits at 25.6x. Is the market overpaying for quality, or is the cash flow work spotting value that earnings multiples miss?
To see how these valuation gaps could close in either direction, including where the P/E might drift toward the fair ratio over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or early opportunity for Waste Connections? Weigh the risks that have investors cautious against the upside drivers that have others optimistic by reviewing the 3 key rewards and 2 important warning signs.
Looking for more Waste Connections style investment ideas?
If you only stop at Waste Connections, you risk missing other opportunities that match or sharpen your thesis, so widen your search now while the data is fresh.
- Target mispriced quality by scanning the 33 high quality undervalued stocks that combine robust fundamentals with prices that have yet to catch up.
- Prioritise resilience by focusing on 32 resilient stocks with low risk scores that pair steadier business profiles with more controlled risk scores.
- Get ahead of the crowd by hunting through 20 high quality undiscovered gems that have strong under-the-radar fundamentals before they attract wider attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com