
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
ServisFirst Bancshares (SFBS) Could Be 18% Undervalued After New 2,000,000 Share Buyback
ServisFirst Bancshares (SFBS) has introduced a new share repurchase plan after the board approved buybacks of up to 2,000,000 shares, which will remain in effect through December 31, 2027.
The new repurchase plan follows a mixed run for ServisFirst Bancshares, with the share price climbing 9.61% year to date but declining over 30 and 90 days. At the same time, a 3-year total shareholder return of 78.72% points to stronger longer term value creation than the recent pullback suggests.
Compare ServisFirst Bancshares' new buyback plan with other potential value ideas by scanning our hand-picked 33 high quality undervalued stocks that also pair shareholder returns with solid fundamentals.
ServisFirst Bancshares trades below both analyst targets and an estimated intrinsic value, even after the recent pullback and fresh buyback plan. Is this a sensible discount, or is the market flagging real risks?
Most Popular Narrative: 15% Undervalued
The most followed narrative values ServisFirst Bancshares at $46.33 using a 7.24% discount rate, compared with the latest close at $39.36. That gap sets up a clear question about whether the new repurchase plan simply leans into what is already framed as a discount.
Expansion of commercial lending teams and ongoing hiring in key Southeastern markets positions the company to capitalize on robust population and business growth in the Sun Belt, supporting above-average organic loan and deposit growth, which is likely to drive top-line revenue and long-term earnings growth.
Increasing merchant services and treasury management fee initiatives, combined with a push to raise penetration rates among existing business customers, are expected to accelerate noninterest income growth and diversify revenue streams, enhancing overall profitability and margins.
See why 4 investors see ServisFirst Bancshares as 15% undervalued.
Result: Fair Value of $46.33 (UNDERVALUED)
Still, rising credit costs around commercial real estate and pressure on deposit growth could quickly challenge the bullish ServisFirst Bancshares narrative that investors are leaning on.
Find out about the key risks to this ServisFirst Bancshares narrative.
Another View: ServisFirst Bancshares Through The P/E Lens
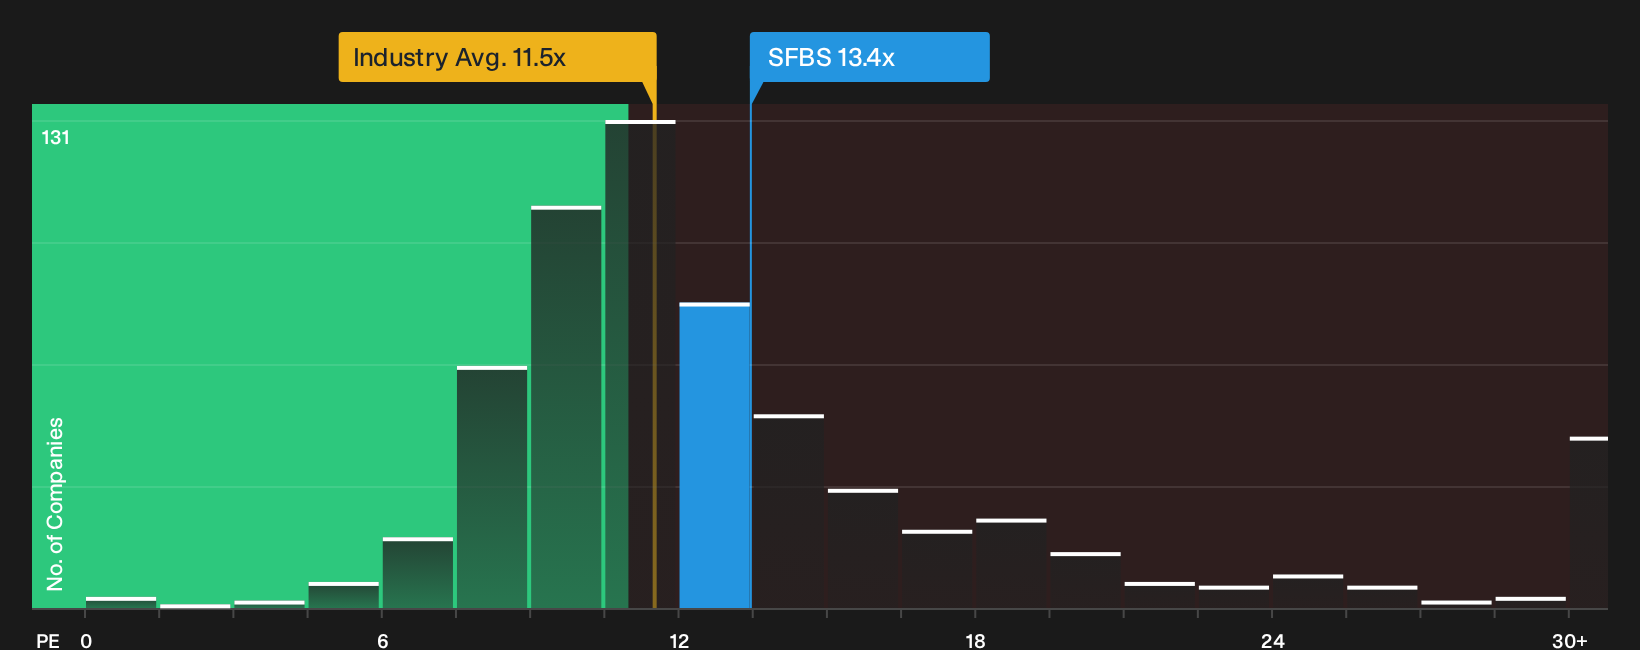
There is a different story when ServisFirst Bancshares is viewed through its P/E ratio. The stock trades at 13.4x earnings compared with a fair ratio of 13x, and above the US Banks average of 11.5x. That premium suggests less room for error if growth or returns disappoint.
See what the numbers say about this price in our valuation breakdown, then decide which story you find more convincing, the discount from fair value or the premium to peers, by running through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
So far, the signals on ServisFirst Bancshares appear mixed. If you want to move quickly and form your own stance, start with the 4 key rewards and 1 important warning sign.
Looking For More ServisFirst Bancshares Investment Ideas?
If ServisFirst Bancshares has sharpened your focus on value and risk, do not stop here. Use the screener to pressure test fresh ideas before capital moves.
- Target potential mispricings by scanning a curated 33 high quality undervalued stocks shortlist that blends quality fundamentals with what could be attractive entry points.
- Strengthen the defensive side of your portfolio by reviewing a 32 resilient stocks with low risk scores designed to spotlight resilient businesses with steadier risk profiles.
- Broaden your opportunity set by checking a 20 high quality undiscovered gems filter that focuses on lesser-known companies with solid financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com