
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Centuria Industrial REIT (ASX:CIP) Could Be 7% Overvalued Following Its Leasing Update
The latest operating update for Centuria Industrial REIT (ASX:CIP) put leasing outcomes in focus, with strong re leasing spreads, an under rented portfolio, and new renewable energy income streams shaping expectations for future cash flows.
Centuria Industrial REIT’s recent operating update lands after a tougher run for the units, with the share price down 15.76% year to date and the 1 year total shareholder return declining 14.76%. The 3 year total shareholder return of 10.73% signals longer term momentum that contrasts with the weaker 90 day share price return of 7.95% and suggests that sentiment around leasing outcomes, income visibility and valuation is still being reassessed at A$2.78.
Compare Centuria Industrial REIT’s leasing and cash flow profile with a curated list of solid balance sheet and fundamentals (12 results) that could handle tougher conditions without relying on perfect market sentiment.
After a tough stretch for the units despite solid leasing progress, the question becomes sharper: Does Centuria Industrial REIT at A$2.78 still offer enough upside potential to justify the current risks on cash flow and asset values?
Most Popular Narrative: 7% Overvalued
Against the last close at A$2.78, the prevailing narrative for Centuria Industrial REIT pegs fair value at A$2.59, which frames current pricing as slightly ahead of that assessment and puts the income yield and asset backing under a stricter lens.
CIP owns industrial and logistics properties. Management reports the portfolio is approximately 17% under-rented, creating potential income growth as leases reset. Separately, five FY26 property sales achieved an average 17% premium to book value. These support my willingness to accept a lower starting yield. At $2.785, reported annual distributions of 16.8c yield 6.03%. My $2.59 buying ceiling requires at least 6.48% yield, 20% above the 5.40% Australian 10-year bond benchmark, and a minimum 20% discount to $4.01 NTA. Rental upside depends on successful leasing, while vacancies and debt costs remain key risks.
See why 1 investors see Centuria Industrial REIT as 7% overvalued.
Result: Fair Value of A$2.59 (OVERVALUED)
Still, any stumble in leasing activity or a rise in debt costs could quickly erode Centuria Industrial REIT’s appeal at a 6.03% distribution yield.
Find out about the key risks to this Centuria Industrial REIT narrative.
Another View On Centuria Industrial REIT’s Value
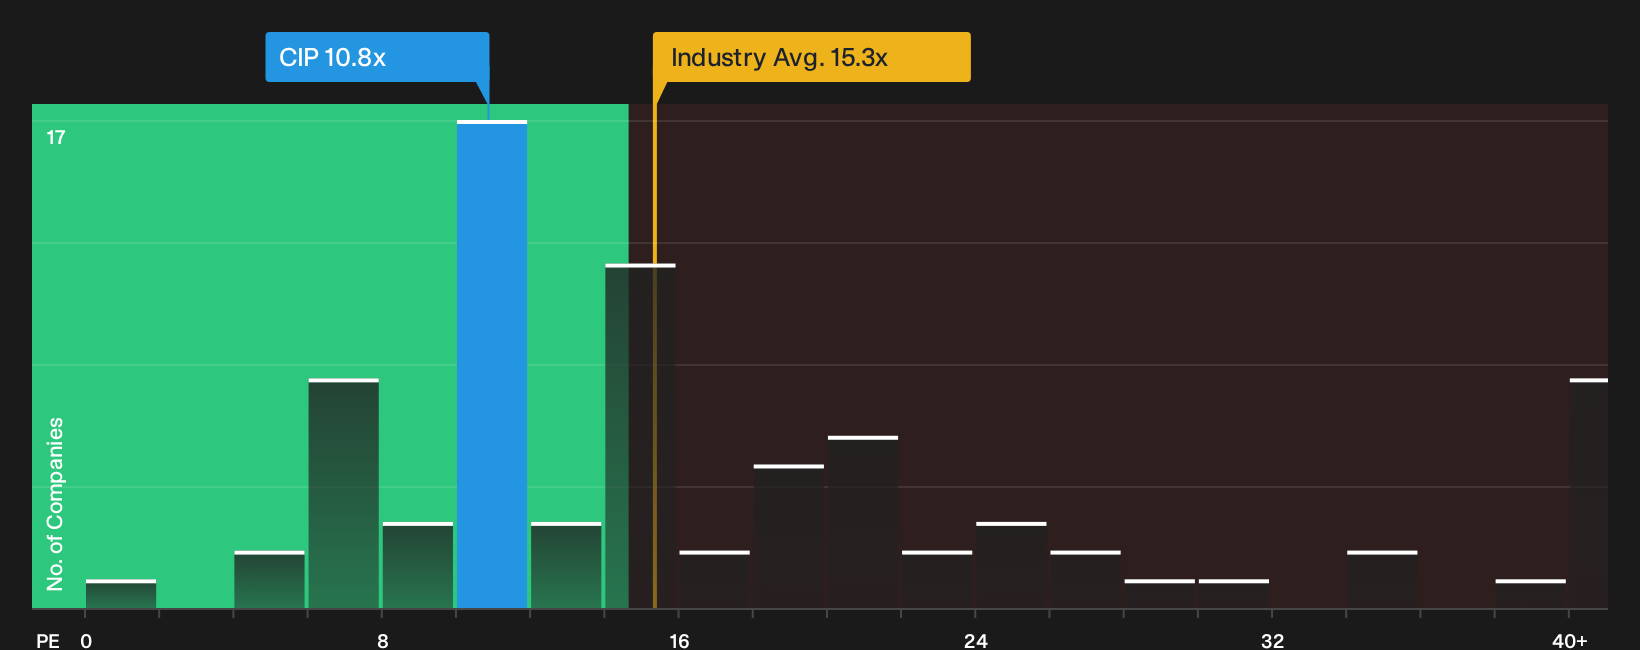
A second lens tells a different story. On a P/E of 10.8x compared with 15.3x for both global industrial REIT peers and the peer average, Centuria Industrial REIT looks cheaper today, even though that ratio sits just above a 10.3x fair ratio, which hints at only modest upside before value risk creeps in.
That kind of gap can close in either direction, through price moves or changes in earnings, so the real question is whether you think the A$2.78 unit price or the multiple does more of the heavy lifting from here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the split between risk and reward around Centuria Industrial REIT feels finely balanced, consider testing the numbers yourself and pressure testing the thesis. Start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Centuria Industrial REIT?
If Centuria Industrial REIT has sharpened your thinking on yield, valuation and risk, do not stop with a single trust. Broader comparisons can keep your decisions grounded and disciplined.
- Target resilience by scanning a 6 resilient stocks with low risk scores that focuses on businesses with sturdier profiles when conditions get tougher.
- Hunt for value by reviewing a 15 high quality undiscovered gems that highlights smaller companies with strong fundamentals that many investors may still overlook.
- Strengthen your income short list by checking a 4 dividend fortresses that concentrates on higher yielding opportunities with an emphasis on durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com