
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
InterDigital (IDCC) Could Be 31% Undervalued Following Its Recent Pullback
InterDigital stock performance snapshot
InterDigital (IDCC) draws attention after a recent move that has left the share price at US$319.30, with the stock down over the past month but higher across the past 3 months.
InterDigital’s recent pullback, including a 1-day share price return that declined 2.67% and a 7-day share price return that fell 3.62%, comes after a 90-day share price return of 23.67%. The 1-year total shareholder return declined 12.15%, but the 3-year total shareholder return is up more than 3x. This suggests short-term momentum is cooling after a strong multi-year run that investors may now be reassessing against current expectations for the business.
Scan how InterDigital compares with other tech-focused stocks showing strong cash generation and licensing-based models by reviewing the curated 20 high quality undiscovered gems in the same corner of the market.
InterDigital now trades at a sharp discount to analyst targets after a strong multi year run and recent pullback. Is that gap caution well placed, or has sentiment swung too far and created a valuation mismatch?
Most Popular Narrative: 31% Undervalued
InterDigital’s most followed narrative pegs fair value around $462.67, well above the recent $319.30 close. The gap between price and story is wide and is described as being rooted in recurring licensing economics rather than short term swings.
The shift in InterDigital’s licensing mix toward streaming and cloud video services, supported by the Amazon agreement that currently recognizes revenue on a conservative estimate during arbitration, leaves scope for higher recurring revenue and earnings if the final award comes in above the booked level.
See why 21 investors see InterDigital as 31% undervalued.
Result: Fair Value of $462.67 (UNDERVALUED)
Still, this bullish InterDigital story leans heavily on the Amazon arbitration outcome and on enforcement spending, which may affect those high margin licensing streams.
Find out about the key risks to this InterDigital narrative.
Another View: InterDigital through a cash flow lens
InterDigital’s most popular narrative argues the stock is about 31% below fair value, yet the SWS DCF model paints a different picture. Based on estimated future cash flows, that model points to a value of $210.75 per share, which sits well below the current $319.30 price and flags potential overvaluation on this measure.
For investors, that split between story driven targets and cash flow based fair value raises a practical question. Which set of assumptions feels closer to how you think InterDigital’s licensing income and costs will actually evolve, and how much of a gap are you comfortable underwriting if the cash flows arrive more slowly than hoped?
Look into how the SWS DCF model arrives at its fair value.
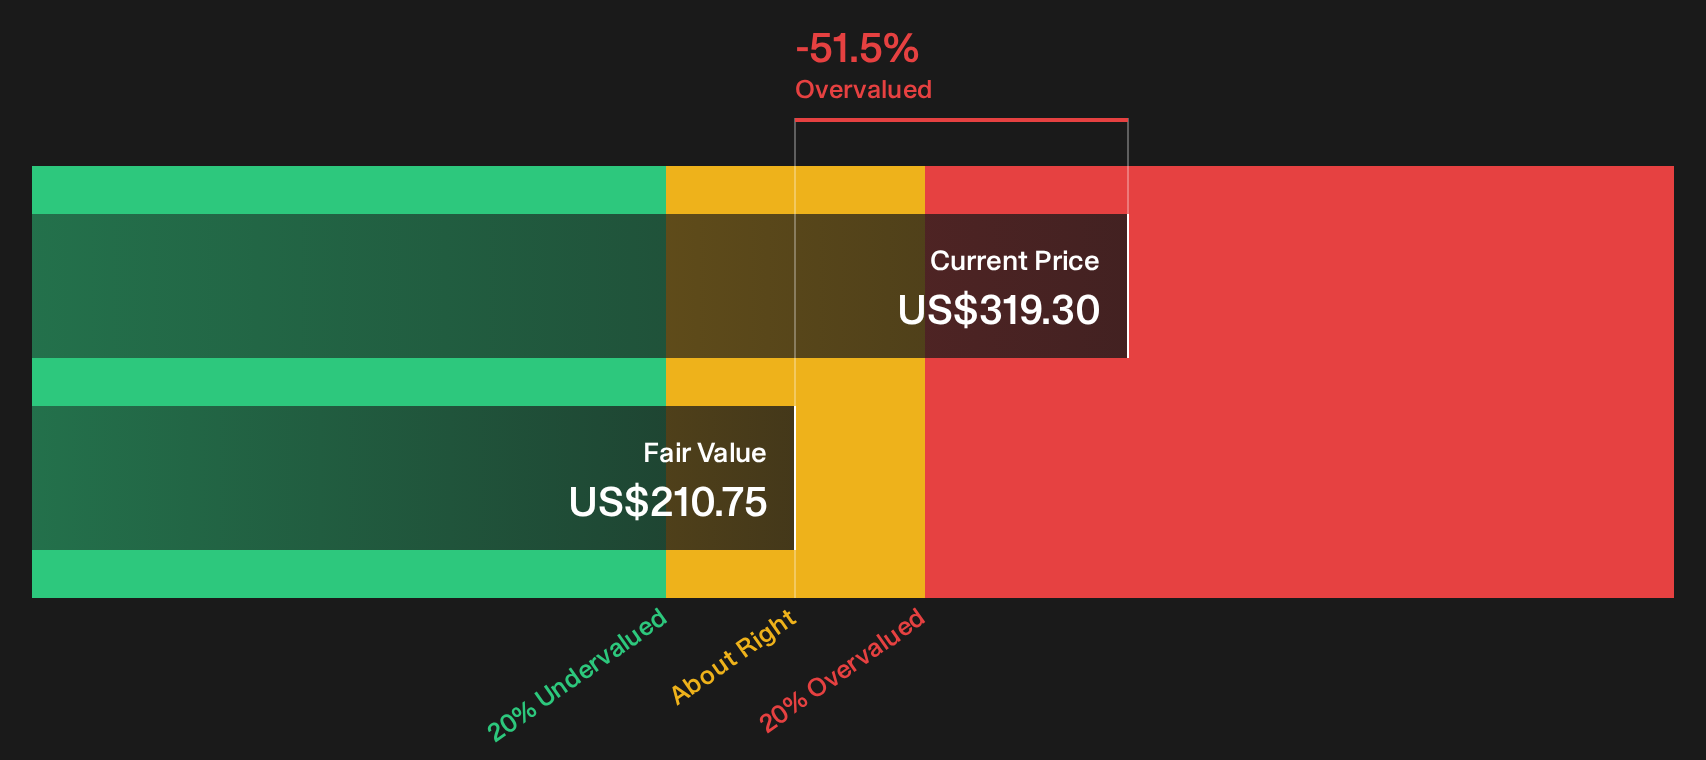
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out InterDigital for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on InterDigital split between cash flow models and narrative fair values, it makes sense to move quickly and test the assumptions yourself using the 3 key rewards.
Looking for more InterDigital style investment ideas?
If you stop with InterDigital, you miss the chance to line up other opportunities that fit your risk, return, and income goals just as precisely.
- Target potential underpriced opportunities by scanning companies with strong fundamentals in the 33 high quality undervalued stocks.
- Build a more resilient portfolio and stress test your downside protection using the 32 resilient stocks with low risk scores.
- Hunt for future leaders before the crowd catches on by combing through the 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com