
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
What Group 1 Automotive Bears Saw Before The Fall
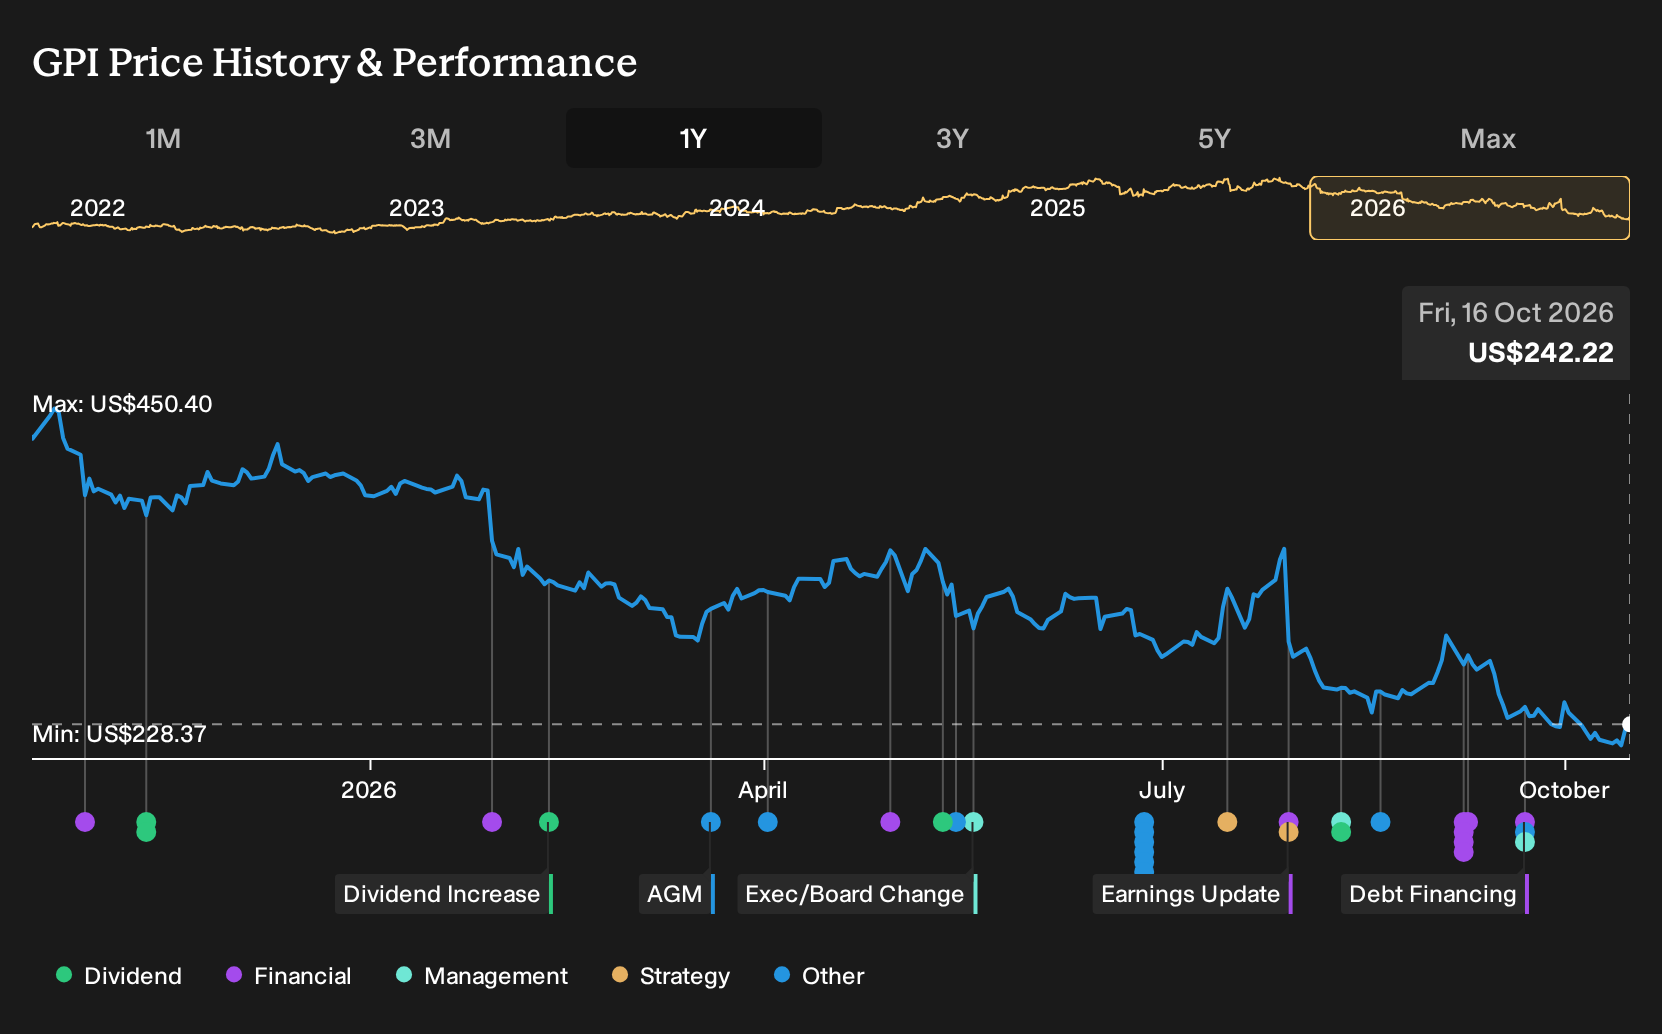
Group 1 Automotive has had a busy year, from mixed quarterly results and a sharp workforce cut to a plan to buy 10 Hennessy dealerships in Atlanta backed by US$1.25b of new senior notes. Investors who held Group 1 Automotive over the past year are down 43.9%, including dividends. If you had put money to work in October 2025 based on the published optimism around aftersales and digital retail, how do those expectations compare with the way acquisitions, branding and cost cuts are now reshaping the business?
The easy part of this move is behind Group 1 Automotive. Zero in on 33 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Weigh On Group 1 Automotive
The shares cost US$431 at the start of the period, which set the reference point for both the optimistic and cautious views on Group 1 Automotive.
The upbeat Narrative argued that a Fair Value of US$475, essentially a price implied by strong aftersales and digital assumptions, was justified. It leaned on high margin parts and service activity supported by an aging vehicle fleet and heavier investment in technology and customer outreach.
The sceptical Narrative pointed to a Fair Value of US$401 based on pressure from electric vehicles and online platforms. It assumed rising direct to consumer sales models and digital only competitors would steadily chip away at dealer pricing power and profitability.
What The Results Put To The Test For Group 1 Automotive
Group 1 Automotive’s decision to fund the planned Hennessy acquisition with US$1.25b in new senior notes supported the narrative about scale and premium clusters, while the Q2 2026 numbers told a tougher tale. Revenue slipped to US$5,385.1m from US$5,703.5m and net income fell to US$103m, with net margin down from 2.5% to 1.9%. The evidence pointed in both directions.
The main assumption on trial was that aftersales and digital tools would protect profitability. For any retailer with a similar pitch, the lesson is simple: track net margin and segment profitability against each expansion move, rather than taking high level growth stories at face value.
What Group 1 Automotive’s Drop Might Be Asking You To Believe
Group 1 Automotive trades at US$242 today after a 43.9% share price fall over the past year, and the selected Narrative’s Fair Value sits above the current price. That view leans on mix, cash generation and capital allocation rather than pure volume recovery.
The pitch is that premium clusters, aftersales and virtual F&I together could reshape earnings quality. Anyone buying now would need to believe that portfolio pruning, Hennessy integration and higher leverage will still feed sustained cash generation without breaking the firm’s balance sheet guardrails.
"The nationwide rebranding to a unified Group 1 identity, which has temporarily weighed on search-driven traffic, creates scope for higher marketing efficiency, better cross-selling across clustered dealerships and stronger share-of-garage capture. This can support same-store revenue and customer lifetime value once the new brand equity is fully established."
One Narrative disagrees with today's price. → See where this Narrative says Group 1 Automotive should trade
Looking Past Group 1’s Forecourt
Group 1 Automotive lives in the physical world of showrooms, lifts and loan desks. Your attention naturally stays there.
Shift the angle a little. Think about where those same customers spend, save and borrow once they leave the lot.
In another market, a single platform blends online shopping with payments, savings tools, credit and logistics into one stitched experience.
It keeps building financial rails as it lends, so reported cash flow can look weaker even as the economic engine deepens.
If that model keeps drawing more shoppers and money flows onto the platform, the unresolved question is how far an all-in-one ecosystem can stretch.
One Narrative has already put a figure on it. → Uncover the company trading 43% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com