
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is SS&C Technologies Holdings (SSNC) Undervalued After Its Thornburg ETF Services Win?
Thornburg win puts SS&C’s ETF services in focus
Thornburg Investment Management’s decision to use SS&C Technologies Holdings (SSNC) for its actively managed ETF share class structure puts fresh attention on the stock and its role in fund operations.
The mandate covers oversight, calculation, reconciliation, shareholder coordination and conversion processing for Thornburg’s ETF share classes, which sit alongside existing ETFs with more than $860 million in assets.
Against that backdrop, SS&C Technologies Holdings has seen momentum build over the past quarter, with a 20.9% 90 day share price return and a 7.0% one year total shareholder return, even though the year to date share price move is slightly down from the US$84.07 level at the start of the year.
Scan for more fund administration and ETF infrastructure stocks that could be benefiting from similar client flows using our curated list of list of solid balance sheet and fundamentals (25 results).
After a strong 90 day run and a mixed set of recent returns, SS&C Technologies Holdings now faces a simpler question. Does the current price still compensate you for the risks on offer, once valuation is laid out in full?
Most Popular Narrative: 10.1% Undervalued
On the most followed narrative, SS&C Technologies Holdings screens as undervalued, with an implied fair value of $93.56 against the last close of $84.07. That gap rests on a view that current profitability, capital returns and revenue guidance can support a higher valuation than the market is assigning today.
The current numbers, including record adjusted revenue, high EBITDA margins and ongoing buybacks and dividends, imply a share price that some observers view as not fully reflecting this business performance, leading to the view that SS&C Technologies Holdings stock may be undervalued.
See why 8 investors see SS&C Technologies Holdings as 10% undervalued.
Result: Fair Value of $93.56 (UNDERVALUED)
Still, the SS&C Technologies Holdings narrative depends heavily on maintaining high adjusted margins and converting its AI and automation spend into sustained profitability rather than creating additional pressure on returns.
Find out about the key risks to this SS&C Technologies Holdings narrative.
Another View: What SS&C’s P/E Is Telling You
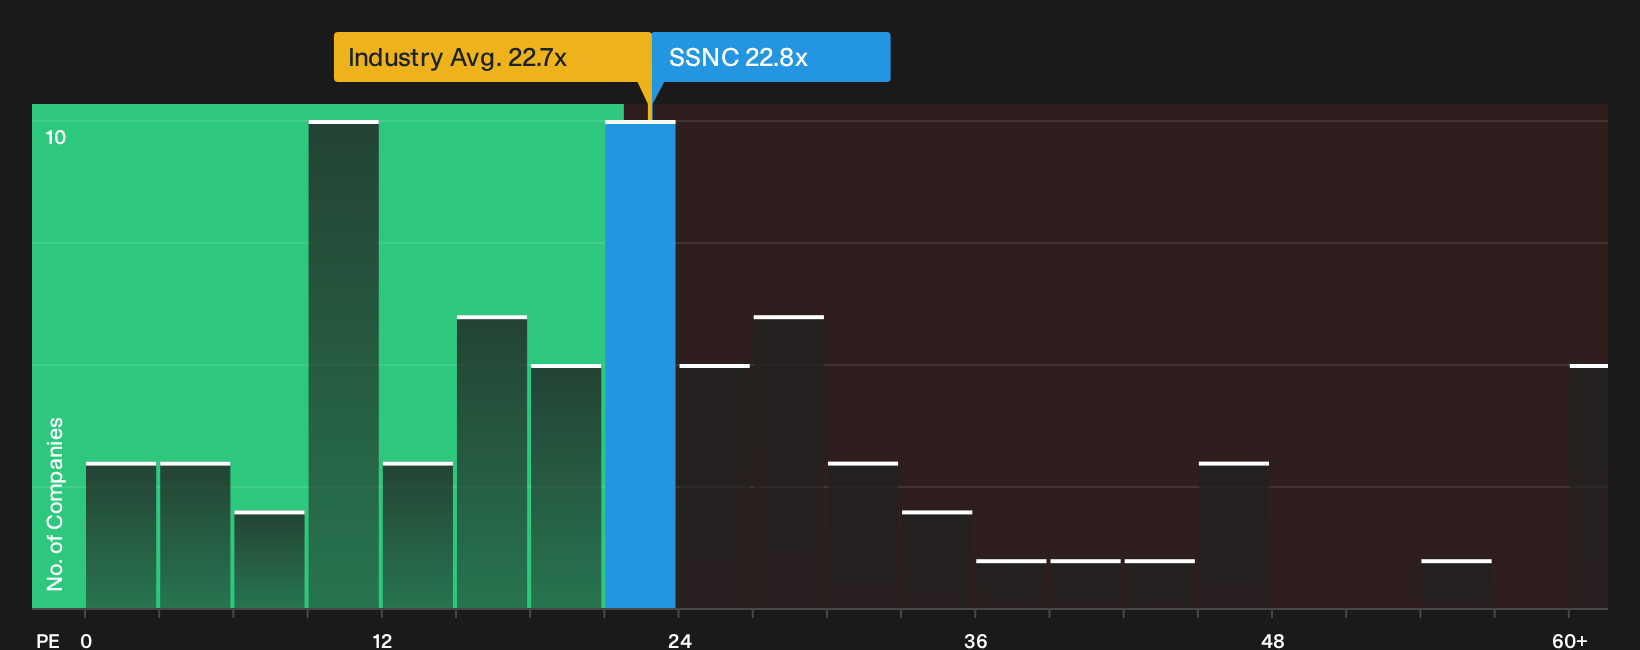
On a simple earnings multiple, SS&C Technologies Holdings looks slightly expensive. The stock trades on a P/E of 22.8x, a touch above both the US Professional Services industry at 22.6x and its own fair ratio of 22.7x. That small premium points to limited margin for error if sentiment cools or growth expectations ease.
When a stock already trades above peers and its fair ratio, even by a narrow band, any disappointment on earnings or cash returns can hit the share price faster than a textbook model suggests. The question is whether the ETF and fund services momentum you have just read about is enough compensation for that tighter valuation cushion, or whether patience is worth more here than urgency.See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the SS&C Technologies Holdings story so far. If you want a sharper view, move fast and stress test the details yourself against 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond SS&C Technologies Holdings?
If you stop with SS&C Technologies Holdings, you risk missing other opportunities that could fit your risk profile and income needs even better.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results) that filters for financial strength first.
- Hunt for potential mispricings with the 33 high quality undervalued stocks that screens for quality businesses the market might be pricing too cautiously.
- Build a cash flow focused watchlist using the 8 dividend fortresses that highlights higher yielding payouts with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com