
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Cash Flow Debate Could Be A Game Changer For Dollarama Stock (TSX:DOL)
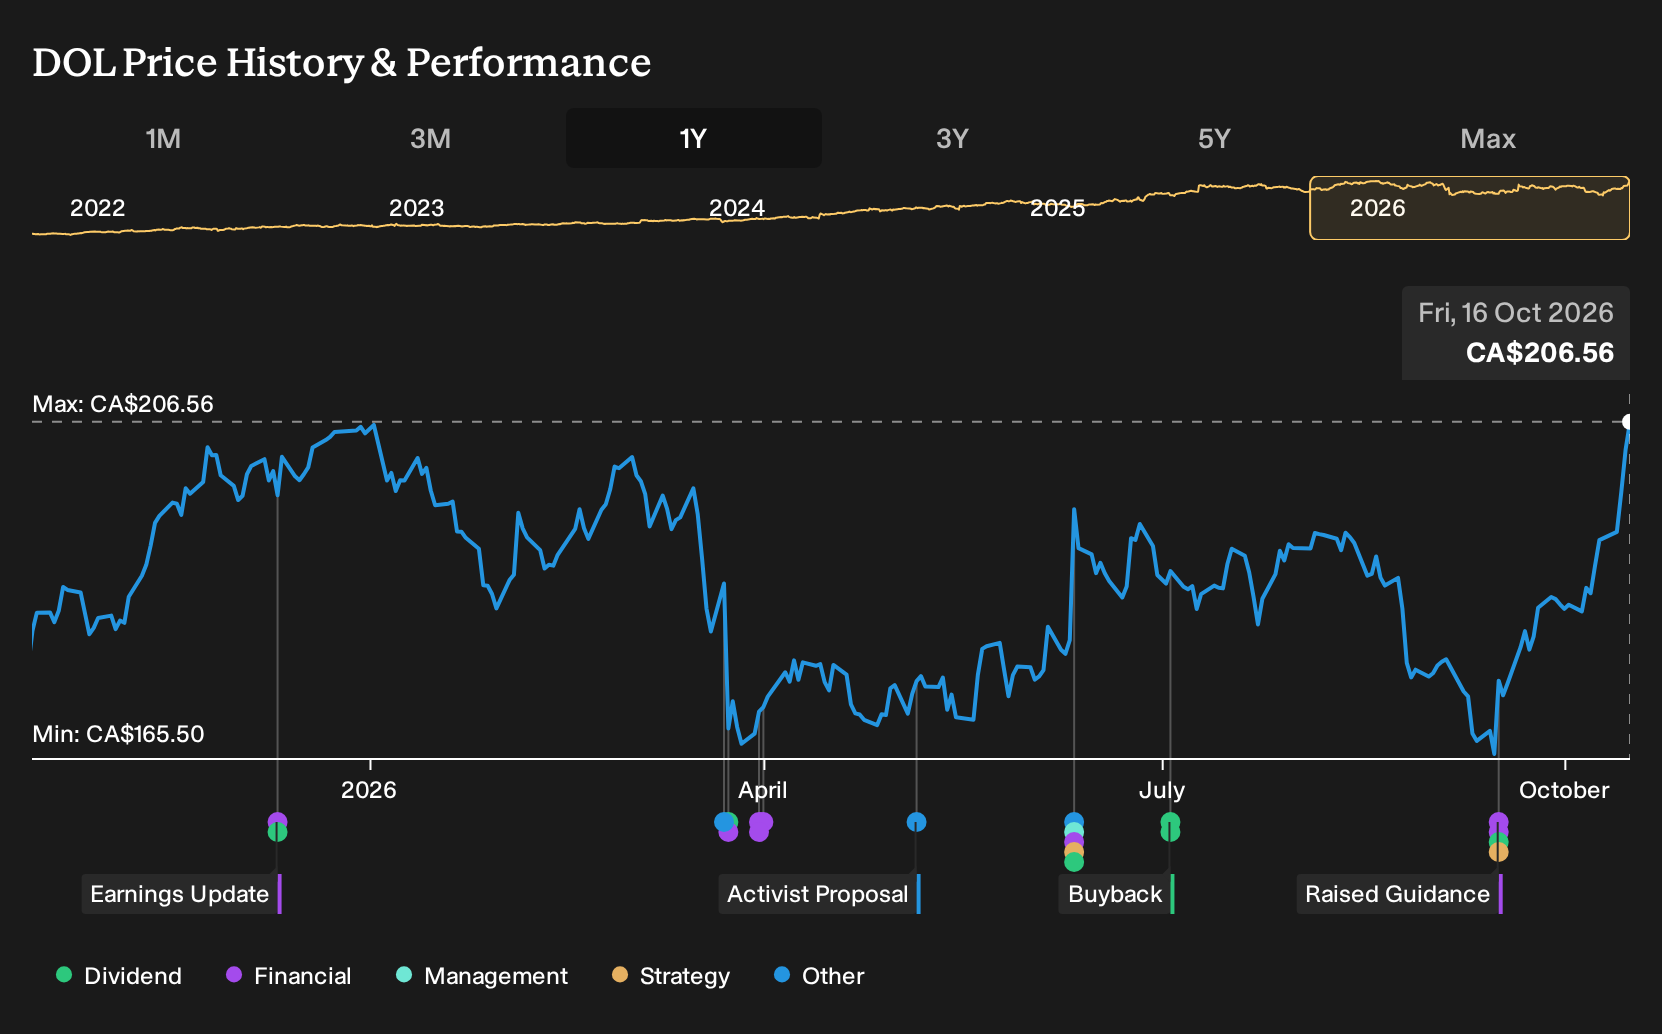
- Dollarama has become one of the most actively traded stocks on the TSX, with about C$196.89m in trading value around a C$203.14 share price, as investors weigh its discount retail model, same store sales drivers and store rollout against updated cash flow modelling.
- The debate now hinges on how well Dollarama can convert its international expansion into sustained cash generation, with DCF models suggesting intrinsic value estimates that differ from the current market price and increasing focus on execution risk in new markets.
- This article will look at how Dollarama's investment narrative is shaped by fresh questions around cash flow projections and international expansion execution.
Compare Dollarama's cash flow story with other retailers and consumer stocks by scanning our curated 5 high quality undervalued stocks that may offer a similar mix of resilience and valuation tension.
Dollarama Investment Narrative Recap
To own Dollarama, you need to be comfortable with a simple idea. The core Canadian chain keeps throwing off cash while management pours time and money into building out Mexico and Australia. The recent spike in trading activity does not change that basic thesis. In the near term, the key swing factor is still how well same store sales and merchandising hold up as consumers lean into value.
The biggest operational risk remains execution in newer regions, especially The Reject Shop integration in Australia and the ongoing ramp in Mexico, which are currently loss making. Higher transport and product costs also matter. If those pressures persist while Dollarama keeps price points low in Canada, margins could stay under pressure in the short run.
With no fresh company announcements tied directly to this trading surge, the most relevant reference point is still management’s multiyear expansion and infrastructure program. Investors are watching how new logistics capacity in Western Canada and IT spending in Australia translate into on-the-ground efficiency, shelf availability and store-level profitability.
This context matters for potential catalysts. If the Canadian store rollout stays on track and the international segments narrow their current losses from merchandise transitions and ramp-up costs, future cash generation may better support Dollarama’s current P/E multiple of 40.6x. If integration issues drag or cost inflation bites harder, that same valuation looks more demanding.
What The Current Analyst Models Assume For Dollarama
Dollarama's narrative projects revenues of CA$9.8b and earnings of CA$1.8b by 2029. That profile rests on analysts pencilling in 7.5% yearly revenue growth and an earnings increase of about CA$400m from CA$1.4b today.
Behind the share price debate sits a relatively tight analyst playbook. Sell side models cluster around revenue growth of 7.5% a year over the next three years, with profit margins moving from 17.3% today to 18.8% by roughly 2029 as the store base and logistics network scale up.
Earnings are a big swing factor in that story. Consensus points to profit of CA$1.8b by 2029 compared with CA$1.4b today, an uplift of roughly CA$400m that assumes both higher revenue and slightly better margins across the group, including the still loss making international pieces.
These same forecasts sit inside a valuation framework investors can easily benchmark. On the Simply Wall St numbers, the analyst models assume a discount rate of about 8.3% and a 2029 P/E of 36.2x on those CA$1.8b of projected earnings, down modestly from 37.1x today but still above the 25.9x P/E cited for the Canadian multiline retail industry.
Share count assumptions also matter for anyone thinking about per share outcomes. Forecasts currently bake in a 1.91% annual decline in shares outstanding over the next three years, which means the buyback program features directly in the path from headline earnings to earnings per share for Dollarama holders.
Pulling these inputs together, the analyst consensus price target lands at CA$207.47, with a bullish high of CA$236.00 and a cautious low of CA$148.00. Against a recent share price of CA$188.74, the average target sits about 9% higher, which implies analysts as a group see Dollarama as broadly fairly valued on their 2029 revenue and earnings path rather than deeply mispriced in either direction.
Uncover why Dollarama's fair value aligns with its current price.
Exploring Other Perspectives
One alternate view puts Dollarama’s Canadian margin story at the center. The most optimistic analysts were pencilling in revenue of about CA$9.9b and earnings near CA$1.9b by 2029 before this trading spike. This reflects a much stronger profit narrative that the latest market move may either reinforce or challenge. Consider how your own expectations sit between these paths.
Explore 4 other Dollarama fair value estimates, including one that suggests there may be as much as 14% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Dollarama research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Dollarama. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dollarama's overall financial health at a glance.
Looking for more Dollarama investment ideas?
If the Dollarama story has sharpened your thinking and you want to broaden your watchlist, use the Simply Wall St screener to test the same cash flow and balance sheet questions across a wider set of businesses.
- For investors who care most about quality at a sensible entry point, start with our curated list of resilient companies that screen as potentially mispriced using the 5 high quality undervalued stocks.
- If capital preservation and lower volatility matter to you, focus on businesses with steadier profiles by reviewing a 8 resilient stocks with low risk scores that match a more defensive style.
- When you want both strength and staying power on the balance sheet, filter for robust finances and consistent fundamentals through the list of solid balance sheet and fundamentals (8 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com