
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Auto Qualified EV Chip Will Impact Skyworks Stock Investors
- Skyworks Solutions has now completed AEC-Q100 automotive qualification for its Si829x isolated safety gate driver with ProVCD technology and made samples, development tools and documentation available for EV, industrial and safety-critical inverter designs.
- The Si829x targets both SiC FET and IGBT platforms with software-configurable gate control and integrated bias regulation, which could tighten Skyworks Solutions’ link to electrification programs where design wins often translate into multi-year content opportunities.
- We will now look at how Skyworks Solutions’ newly qualified Si829x safety gate driver could influence the broader investment narrative around electrification.
Scan other electrification plays that are positioned for multi-year hardware content wins with our curated list of 41 power grid technology and infrastructure stocks.
Skyworks Solutions Investment Narrative Recap
To own Skyworks Solutions right now, you need to believe the merged Skyworks and Qorvo can keep growing premium mobile and broad markets like Wi-Fi, AI data center and automotive, while lifting margins from a relatively low 7.2% net level. The big near term swing factor is execution on integration and cost structure as the new management team beds in.
The main risk remains customer concentration, with roughly 57% to 60% of revenue tied to the largest mobile buyer, plus any disruption from merger integration, board changes and higher reliance on debt funding. The fresh bond exchange itself does not materially alter the operating outlook, but it does modestly increase focus on balance sheet discipline.
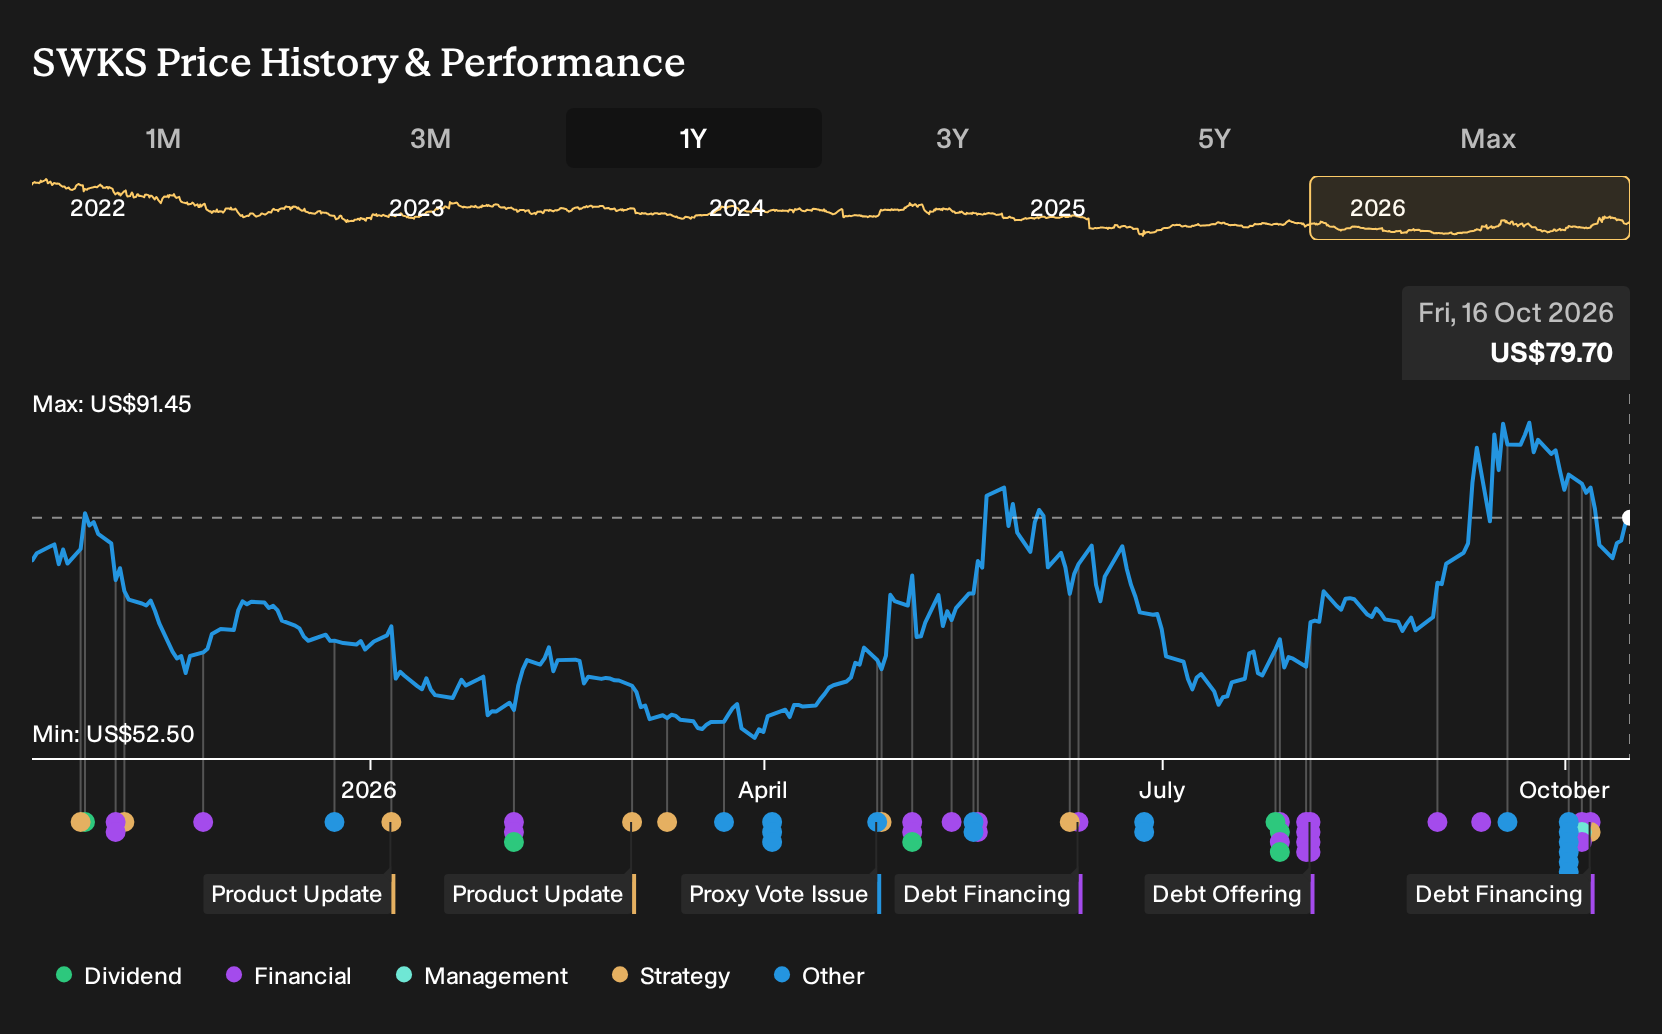
The fixed income exchange tied to Qorvo’s 2029 and 2031 notes is the clearest financial backdrop to watch alongside the Si829x launch. Skyworks Solutions issued about US$778.1m of new 2029 notes at 4.375% and US$646.8m of new 2031 notes at 3.375%, with the instruments ranking as senior unsecured obligations of the parent.
For equity holders, those terms frame the cost of capital as management pursues merger synergies and electrification wins, including SiC and IGBT content in EV inverters. Catalysts around RF content per handset, AI data center demand and EV power design wins now sit against a capital structure that leans more on unsecured debt. Execution on cash generation becomes more important if growth assumptions prove optimistic.
Skyworks Solutions' narrative projects US$4.5b revenue and US$320.3 million earnings by 2029. This assumes 3.5% yearly revenue growth and an earnings increase of about US$30 million from US$290.1 million today.
Uncover why Skyworks Solutions' fair value indicates a 12% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
Bullish analysts focus on one thing you may weigh very differently. They see the Qorvo merger and new debt stack as a springboard, not just a liability, backing revenue of about US$7.9b and earnings of roughly US$1.3b by 2029. That is far above consensus. These views were formed before the Si829x launch and recent note exchanges, so you may want to explore how each camp might now refresh its story around Skyworks Solutions.
Explore 4 other Skyworks Solutions fair value estimates, including one that suggests as much as 113% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Skyworks Solutions research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Skyworks Solutions. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Skyworks Solutions' overall financial health at a glance.
Looking For More Investment Ideas Beyond Skyworks Solutions?
If the Skyworks Solutions story has you thinking about where else consistent hardware or cash flow themes might show up, it can help to scan a wider field of stocks that meet clear, rules based criteria using the Simply Wall St Screener.
- If capital preservation and smoother ride potential matter to you, start with companies that score well on resilience and risk using our 32 resilient stocks with low risk scores.
- If reliable cash generation plus healthy finances are a priority, focus on businesses with strong balance sheets and solid fundamentals through this curated list of solid balance sheet and fundamentals (25 results).
- If you are hunting for mispriced quality that is still under the radar, cast a wider net across our 20 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com