
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Lower P E Metrics At TBC Bank Group Stock Have Changed Its Investment Story
- TBC Bank Group has attracted fresh attention after a multiyear share price gain left its current P/E ratio below both the wider banks industry and key peers, prompting questions about how the market is pricing its earnings power.
- The gap between TBC Bank Group’s solid long-term operational track record and its lower P/E multiple is pushing investors to reassess how much risk they assign to its business mix in Georgia and Uzbekistan.
- We will now examine how TBC Bank Group’s lower P/E multiple, alongside its multiyear execution record, could influence the broader investment narrative.
Compare TBC Bank Group’s valuation gap with a curated set of other potentially mispriced opportunities by scanning the 7 high quality undervalued stocks that share strong fundamentals with muted market expectations.
TBC Bank Group Investment Narrative Recap
TBC Bank Group appeals to shareholders who believe in a long runway for digital banking and financial deepening in Georgia and Uzbekistan, with earnings supported by fee income and retail lending. The short term swing factor is how well management holds net interest margins while funding costs and credit quality in Uzbekistan are being tested. The recent valuation focus does not change that core equation.
The biggest immediate risk is that credit losses in Uzbekistan, already framed by a 7 to 10% cost of risk, stay elevated or rise, which would pressure profitability despite growth. Liquidity in that market is another watchpoint if loan growth keeps outpacing deposits, since that could push funding costs higher and temper near term earnings momentum.
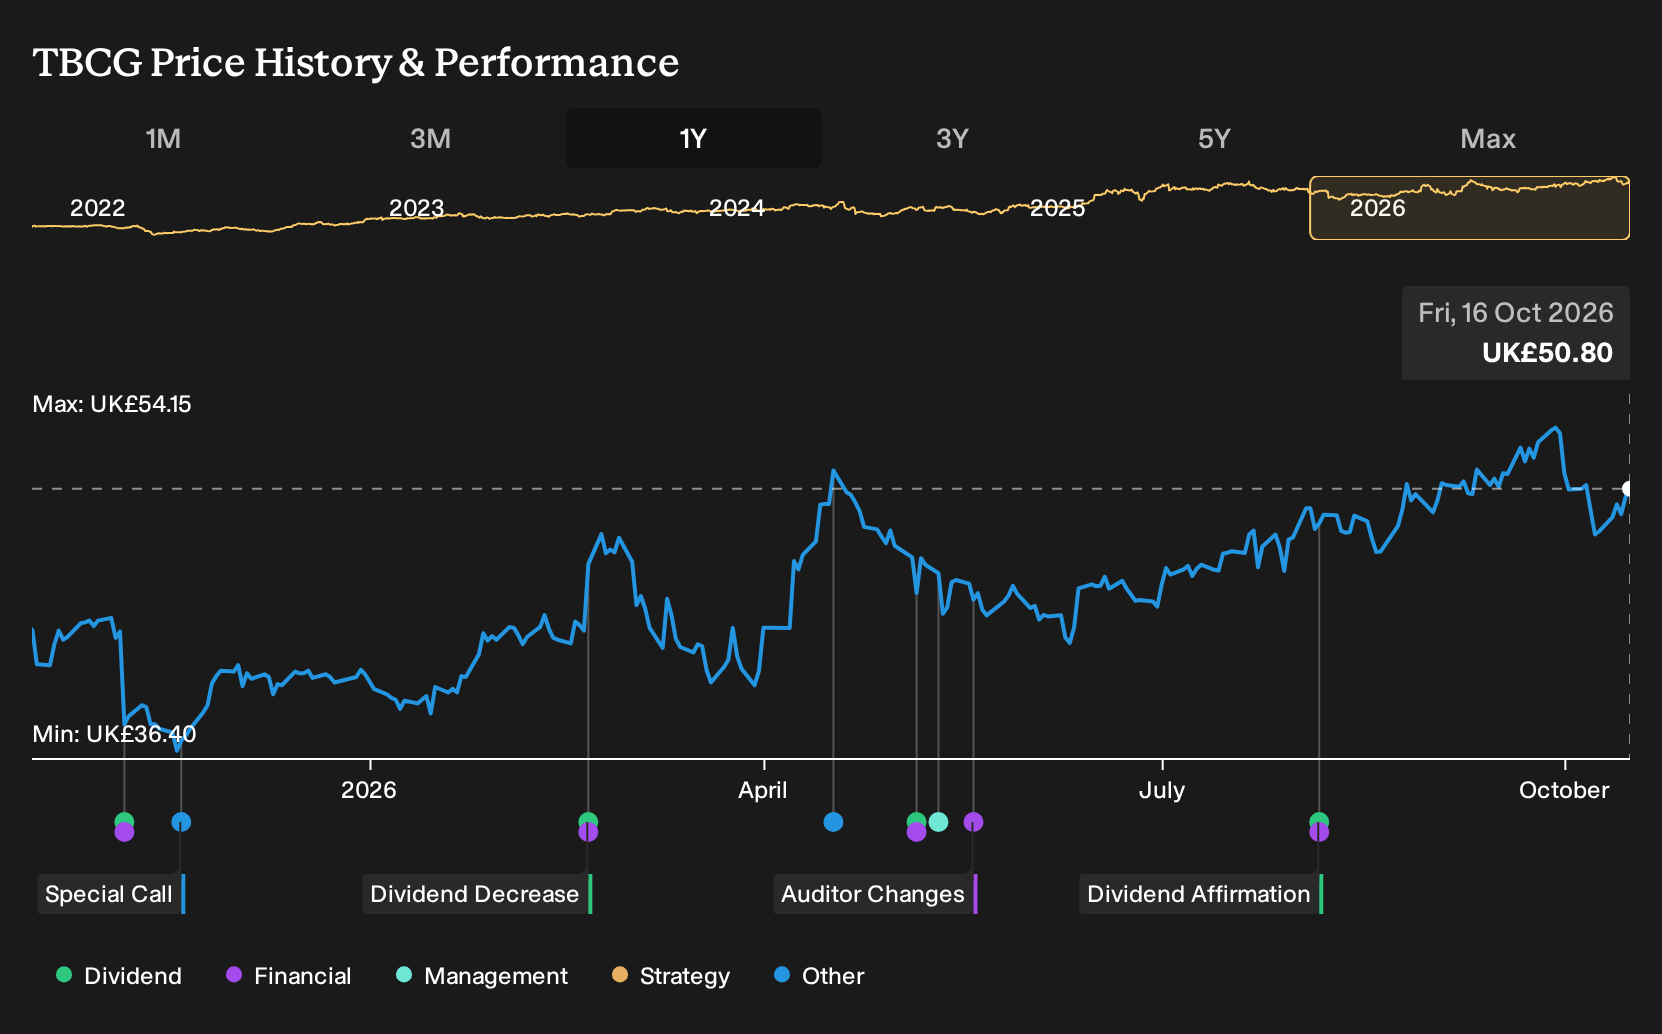
Recent commentary around TBC Bank Group has centered on its P/E discount to peers after a strong 5 year share price run. That attention ties directly to the existing catalyst investors already cared about, whether earnings from digital and Uzbekistan expansion can compound at a rate that makes the current multiple look conservative.
There has not been a specific new operational announcement tied to this valuation discussion, so the more interesting angle is how existing data points fit together. Earnings growth over the past 5 years, high reported return on equity and strong digital penetration all feed the bull case. At the same time, items like a relatively low bad loan allowance and a higher level of non performing loans keep the risk side of the ledger very real.
TBC Bank Group's current analyst narrative points to GEL5.5b in revenue and GEL2.2b in earnings by 2029, based on an assumed 21.7% yearly revenue growth rate and an earnings increase of about GEL800m from GEL1.4b today.
Uncover why TBC Bank Group's fair value indicates a 14% potential upside to its current price before the valuation gap narrows.
Exploring Other Perspectives
Fair value estimates for TBC Bank Group from three Simply Wall St Community members stretch from 57.79 to 117.09, a wide span that hints at very different assumptions on growth, risk and required returns. When you also consider concerns about Uzbekistan credit costs and regulation, there is plenty of room for sharply opposing views. Explore them.
Explore 2 other TBC Bank Group fair value estimates, including one that suggests it could be worth just £57.79.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TBC Bank Group research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for TBC Bank Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TBC Bank Group's overall financial health at a glance.
Looking for more investment ideas beyond TBC Bank Group?
If the debate around TBC Bank Group has sharpened your view on valuation and risk, you can use that same checklist to scan a wider watchlist. The Simply Wall St Screener lets you apply those filters in a structured way so you can quickly surface other candidates that fit your own return and risk profile.
- If capital preservation ranks high on your list, you could start with companies that score well on resilience and balance sheet strength by reviewing 4 resilient stocks with low risk scores.
- For investors who care about quality at a reasonable price, you can compare TBC Bank Group with a broader set of firms that combine strong fundamentals with subdued expectations through the 7 high quality undervalued stocks.
- If you are hunting for less crowded opportunities with solid financial profiles, you might broaden your search to a 5 high quality undiscovered gems that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com