
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Kmart Regulatory Action Could Be A Key Test For Wesfarmers Stock
- Regulators have taken action against Wesfarmers subsidiary Kmart Australia over compliance issues, putting a spotlight on potential extra costs and pressure on retail profit margins.
- The scrutiny lands while Wesfarmers trades on a P/E meaningfully above sector peers, sharpening debate on how much investors should pay for its current earnings profile.
- The next step is to assess how Wesfarmers' premium valuation compares with the fresh regulatory pressure on Kmart Australia within the broader investment narrative.
Wesfarmers Investment Narrative Recap
To own Wesfarmers, you need to believe its mix of Bunnings, Kmart, Officeworks, chemicals and health can keep converting steady demand into resilient earnings, even as growth expectations are modest. The big short term swing factor is how well retail margins hold up while cost pressures and softer pockets of demand are managed across Australia and New Zealand.
The Kmart Australia regulatory action plugs directly into that risk. Extra compliance work and any remedial spend could nibble at profitability, although the impact looks more like an incremental headwind than a thesis breaker. For now, the tension is simple: premium P/E versus rising scrutiny on a key discount retail engine.
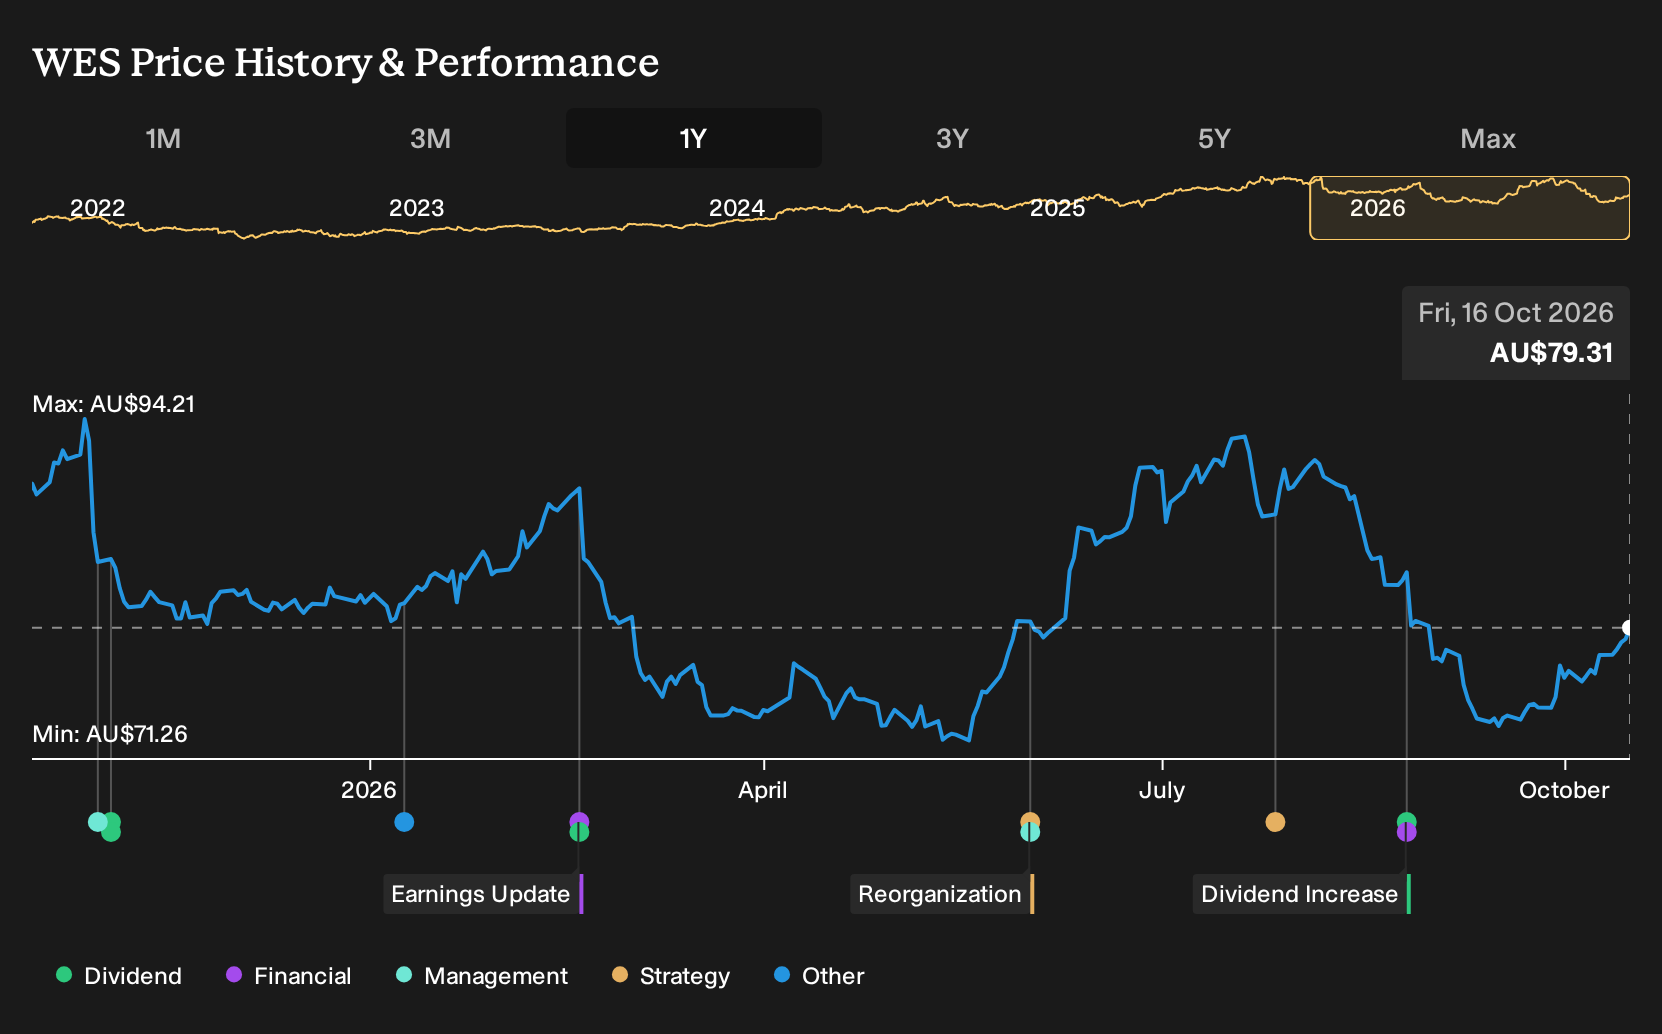
With no fresh trading update tied directly to this regulatory move, the most relevant reference point is still the recent data showing Wesfarmers on a P/E of 31.3x against lower sector and global multiline retail averages. That valuation gap is the live catalyst that interacts most clearly with the Kmart compliance story.
Investors are weighing a business with high forecast return on equity and expected earnings growth of about 7% a year against a share price sitting above some intrinsic value estimates and analyst targets. Any sign that regulatory costs, debt levels or execution in newer areas such as health and lithium push returns lower could quickly change how comfortable that premium feels.
Wesfarmers' narrative projects A$52.8b revenue and A$3.5b earnings by 2029. This assumes 4.4% yearly revenue growth and an earnings increase of about A$0.4b from A$3.1b today.
Uncover why Wesfarmers' fair value indicates a 4% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate Wesfarmers view leans heavily on the risk that higher security, labour and digital upgrade costs bite harder than expected, especially now that Kmart faces fresh compliance pressure. Some analysts with a more bearish outlook were already only pencilling in A$53.3b revenue and A$3.3b earnings by 2029, so their narrative may shift further after this news.
Explore 7 other Wesfarmers fair value estimates, including one that suggests as much as 54% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Wesfarmers research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Wesfarmers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Wesfarmers' overall financial health at a glance.
Looking for more Wesfarmers-sized investment ideas?
If Wesfarmers has you thinking about quality, pricing power and risk, it can help to line it up against other listed businesses that fit different profiles on value, balance sheet strength and volatility. The Simply Wall St Screener lets you quickly compare those angles so you can build a watchlist that actually matches your own tolerance for risk and return.
- If you want potentially mispriced quality without the same P/E stretch, scan through a curated set of companies screened as 4 high quality undervalued stocks that may offer sturdier margins of safety.
- For investors who care more about resilience than excitement, filter for businesses with robust finances and conservative leverage using a list of solid balance sheet and fundamentals (12 results) that can help anchor a portfolio.
- Those hunting for underfollowed opportunities can turn to a 15 high quality undiscovered gems that focuses on lesser-known stocks with strong fundamentals that the broader market may not be watching closely.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com