
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
CAE (TSX:CAE) Secures Seahawk Upgrade Win, Is The Stock Fully Priced?
CAE (TSX:CAE) just secured a key defense contract, with its MAD-XR magnetic anomaly detector selected for the Royal Australian Navy’s 36 SH-60R Seahawk helicopters in partnership with the US Navy and Lockheed Martin.
At around CA$34.10, CAE’s recent 1 month share price return of 4.12% contrasts with a year to date share price decline of 19.67%. The 3 year total shareholder return of 19.06% suggests longer term holders have seen a different story from the past year’s 11.15% total shareholder return decline.
Scan other defense and aerospace contractors riding similar contract momentum by zeroing in on the hand picked 41 power grid technology and infrastructure stocks aligned with long term government and infrastructure spending themes.
CAE appears to be a solid training and defense platform winning real contracts, yet the share price is still down sharply this year. Is that recent contract win fairly reflected in what you are paying today?
Most Popular Narrative: 23% Undervalued
CAE last closed at CA$34.10, while the most followed narrative pegs fair value near CA$44.47, using a 7.7% discount rate and a long term transformation story to frame that gap.
Execution of CAE’s multi year transformation program, targeting $125 million to $150 million of structural cost reductions and adjusted segment operating income of $950 million to $1b by fiscal 2030, is intended to lift net margins, free cash flow conversion and returns on invested capital. Refocusing the portfolio by pursuing strategic alternatives for noncore businesses that make up roughly 8% of revenue, with management expecting proceeds to at least fund the US$200 million to US$250 million transformation program, could simplify CAE’s model and support free cash flow and leverage metrics.
See why 31 investors see CAE as 23% undervalued.
Result: Fair Value of CA$44.47 (UNDERVALUED)
Still, the CAE story can weaken quickly if civil training demand stays soft or if higher leverage and transformation spending strain the balance sheet more than expected.
Find out about the key risks to this CAE narrative.
Another View: What CAE's P/E Is Signalling
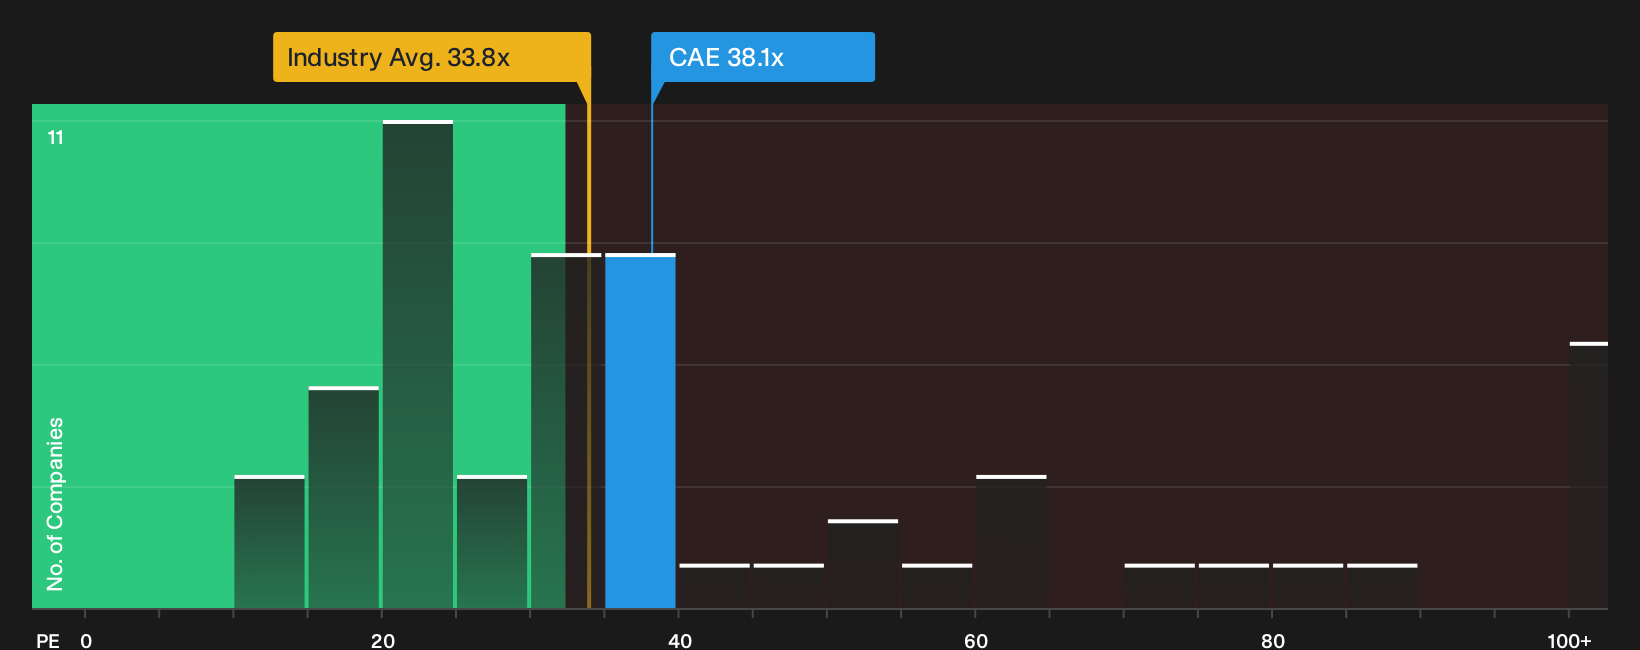
There is a clear split once you switch from narratives about CAE to simple price ratios. The stock trades on a P/E of 38.1x, which is higher than both the peer average at 35x and the broader North American Aerospace & Defense group at 33.8x, and also above a fair ratio of 32.4x that the market could move toward over time.
If earnings forecasts miss or get pushed out, that gap suggests more room for disappointment than for a cheap entry point. Are you comfortable paying a premium today for a story that already has a lot of good news baked into the multiple, or would you rather wait for the math to line up more cleanly with the narrative?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on CAE so far. Act while the data is fresh, review both the concerns and the upside, then weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CAE?
If CAE has you thinking about where else the numbers and story might line up, use the screener to surface fresh opportunities before others move first.
- Target dependable income and filter for companies that aim to sustain higher yields with the 3 dividend fortresses.
- Spot potential value gaps early by scanning companies flagged as 5 high quality undervalued stocks.
- Zero in on financial resilience and prioritise balance sheets that look sturdier using the list of solid balance sheet and fundamentals (8 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com