
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
THOR Industries (THO) Looks Pricey On A 3.8% Dividend Lift
THOR Industries dividend move and what it signals
THOR Industries (THO) has drawn fresh attention after its board approved a 3.8% lift in the regular quarterly dividend to US$0.54 per share following the October 13 meeting.
Recent trading tells a mixed story. THOR Industries’ share price has risen 7.2% over the past week but is down 35.1% year to date, with a 1-year total shareholder return decline of 33.1%. This points to fading longer term momentum despite this dividend lift.
Scan how THOR Industries compares with other income-focused opportunities by reviewing our hand-picked list of 8 dividend fortresses.
THOR Industries just lifted its payout while the share price lags its 1-year level and sits well below the average analyst target. Is the market discount justified, or is fair value closer to those estimates?
Preferred P/E of 19.9x for THOR Industries: Is it justified?
On valuation, the market is currently paying a P/E of 19.9x for THOR Industries at a last close of $68.44, and that sits against a backdrop where the shares have fallen sharply over one and five years. That is a full earnings multiple for a business that has seen earnings decline over time while analysts still see scope for future profit growth.
The P/E ratio compares the share price to earnings per share and gives a quick sense of how much investors are willing to pay for each dollar of profit. For a cyclical manufacturer like THOR Industries that sells recreational vehicles across North America and Europe, the metric effectively wraps the market’s expectations about future demand, profitability, and balance sheet resilience into a single number.
Here, several signals pull in different directions. Earnings declined at an average rate of 34.9% per year over the past 5 years and fell 31.3% over the last year, and profit margins of 1.8% are below last year’s 2.7%. At the same time, forecasts point to earnings growing 19.9% per year, which is quicker than the broader US market forecast of 17% per year. The current P/E therefore suggests investors are already paying up for that recovery profile, even as the SWS DCF model estimates THOR Industries is trading above an implied future cash flow value of $27.01.
Compared with benchmarks, the 19.9x P/E sits above both the global auto industry average of 13.6x and a peer average of 19.3x. It also exceeds an estimated fair P/E of 16.3x, which indicates the current earnings multiple is richer than the level the market could move toward if expectations cool or forecasts are not met.
Explore the SWS fair ratio for THOR Industries.
Result: Price-to-earnings of 19.9x (OVERVALUED)
Still, earnings have declined sharply in recent years and profit margins are thin at 1.8%. Any setback in RV demand or dealer inventory could hit sentiment.
Find out about the key risks to this THOR Industries narrative.
Another view on THOR Industries valuation
The P/E screen paints THOR Industries as expensive, yet our DCF model tells a different story. On that cash flow lens, the stock at $68.44 trades well above an estimated value of $27.01, which points to a rich price rather than a bargain. So which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
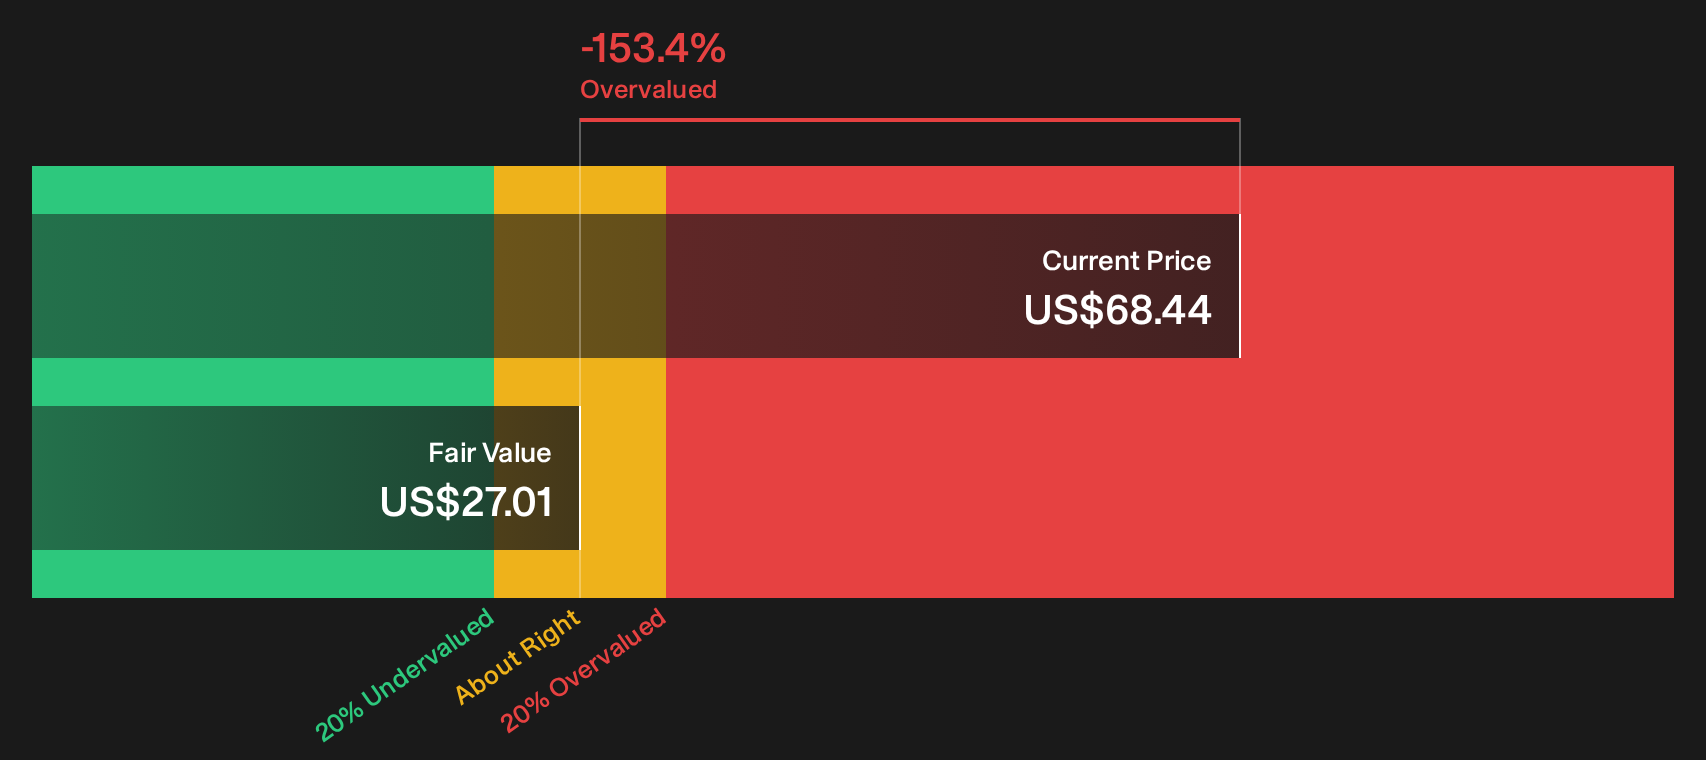
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out THOR Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the THOR Industries picture still feels mixed, that is the point, and it is why the next move is yours. Weigh the pressures against the potential by reviewing the 2 key rewards and 1 important warning sign
Looking for more THOR Industries sized opportunities?
If THOR Industries has you rethinking where your money works hardest, now is the time to widen your lens with fresh, data driven stock ideas.
- Target steadier compounding by scanning a 32 resilient stocks with low risk scores that highlights businesses with more resilient profiles when markets turn choppy.
- Hunt for mispriced potential through a 20 high quality undiscovered gems that focuses on quality companies many investors are still overlooking.
- Rebuild your income toolbox using a list of solid balance sheet and fundamentals (25 results) that points you toward firms combining financial strength with capacity to continue rewarding shareholders.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com