
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Harrow (HROW) Stock May Be Reasonable Given Its Current Sales Base
Harrow has had a bumpy ride, with sharp swings that leave the current US$27.28 share price looking like a referendum on how much investors are willing to pay for its sales. With the stock pulling back recently but still showing a strong longer term record, the core question is whether the present valuation lines up with what the business is generating on the top line.
- Over the past 5 years the stock has gained 180.1%, which puts real weight on whether the revenue base can support that kind of re-rating.
- The business model depends heavily on converting product demand into durable sales growth and cash generation, which can matter a lot for how much investors are prepared to pay for each dollar of revenue.
- Your read on Harrow is one view; the desks covering it have another. See what analysts think Harrow's shares could be worth.
The issue now is whether Harrow's current share price is adequately supported by its sales when stacked against the Fair Ratio benchmark.
If you want to test this same sales based valuation question beyond Harrow, widen the lens with the 33 high quality undervalued stocks.
Is Harrow Still Cheap on Sales?
A sales based lens suits Harrow because revenue is the clearest line investors get today on what the market is paying for its ophthalmic franchise.
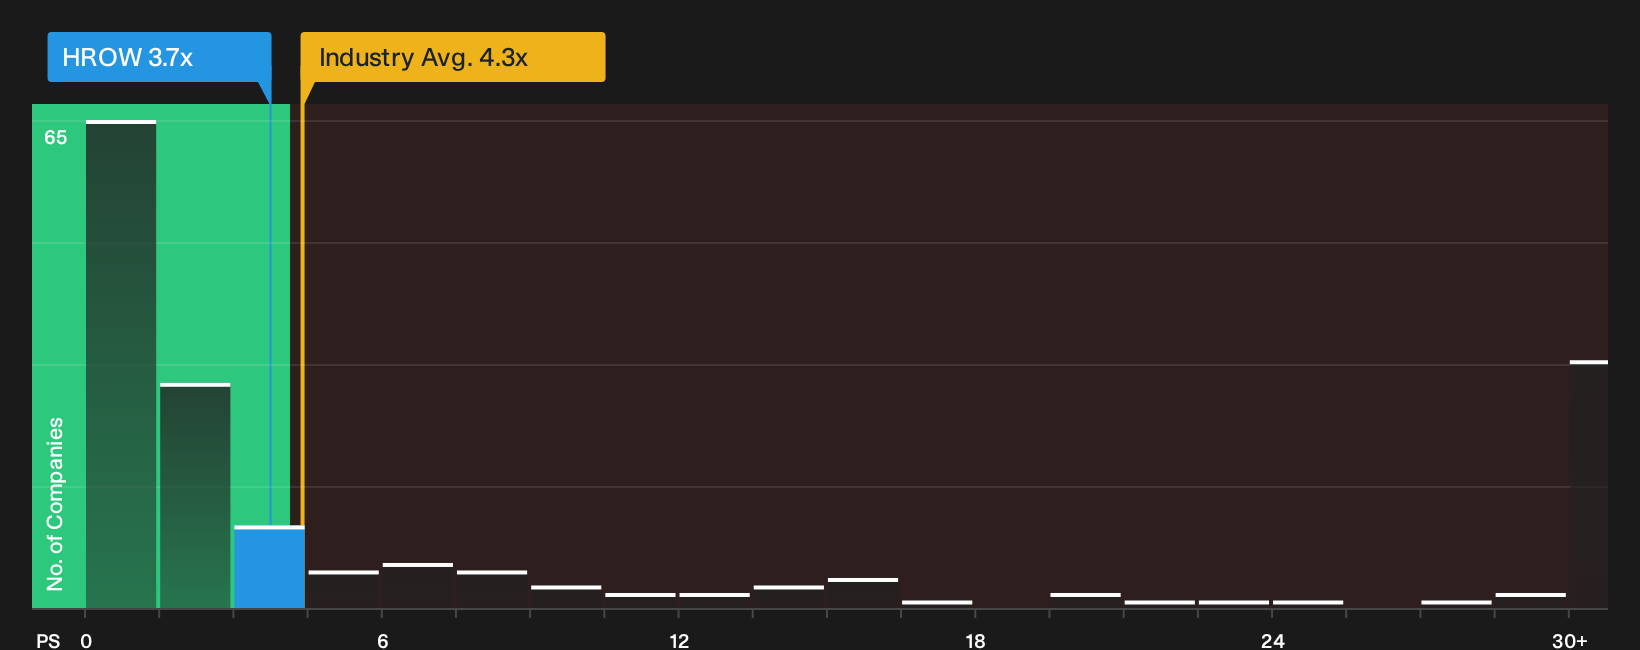
On this measure, Harrow trades on a P/S of 3.7x. That is below the Pharmaceuticals industry average of 4.3x and also under the peer group on 5.6x. This means the market is currently attaching a lower price tag to each dollar of Harrow's revenue than to many comparable companies. The Fair Ratio, which adjusts the benchmark P/S for Harrow's own growth profile, margins, size and risk, points to a higher level than where the shares change hands. For readers, that gap suggests the stock screens as undervalued on this sales yardstick once those business characteristics are taken into account. Explore the numbers behind Harrow's P/S valuation.
The Harrow Narrative: What Would Justify Today's Price?
Harrow's valuation question naturally leads to Simply Wall St Narratives, which explain what kind of future path for growth, margins and earnings would need to occur for the stock to be worth materially more or materially less than the current share price. Each narrative presents fair value as a thesis about the business that you can watch over time, rather than a one-off snapshot, with all of this available on the Community page.
One of the top community narratives on Harrow: 39% undervalued
"While the company's expansion of its branded ophthalmic pharmaceutical portfolio and recent strategic acquisitions significantly grow its addressable market and promise operational leverage..."
Discover why this Narrative puts Harrow at 39% undervalued.
Harrow’s share price is only one piece of the decision
Who actually steers Harrow, how their pay is structured and whether those incentives align with shareholders can matter as much as any multiple or ratio you have seen so far. See who runs Harrow and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com