
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Southwest Gas Holdings (SWX) Priced Too Richly For Its Earnings?
Southwest Gas Holdings has given shareholders a strong ride in recent years, which puts a brighter spotlight on whether the current share price lines up with what its earnings can reasonably support. With the stock now trading at US$87.45, the key issue is how that market tag stacks up against the profit power of the underlying utility business.
- Over the past 3 years the stock has returned 67.9%, which raises a clear question about whether earnings have kept pace with that kind of share price climb.
- The group relies on a regulated gas distribution model, so the way its allowed returns, operating costs, and capital spending translate into net income may support or limit how much investors are prepared to pay for each dollar of earnings.
- There is a second opinion on Southwest Gas Holdings worth weighing. See what analysts think Southwest Gas Holdings's shares could be worth.
The issue now is whether Southwest Gas Holdings' current market price is adequately backed by its earnings when judged against the Fair Ratio benchmark.
If you are weighing whether Southwest Gas Holdings' recent 67.9% three year return lines up with its earnings, it can help to compare that question across 33 high quality undervalued stocks.
Is Southwest Gas Holdings Getting Expensive on Earnings?
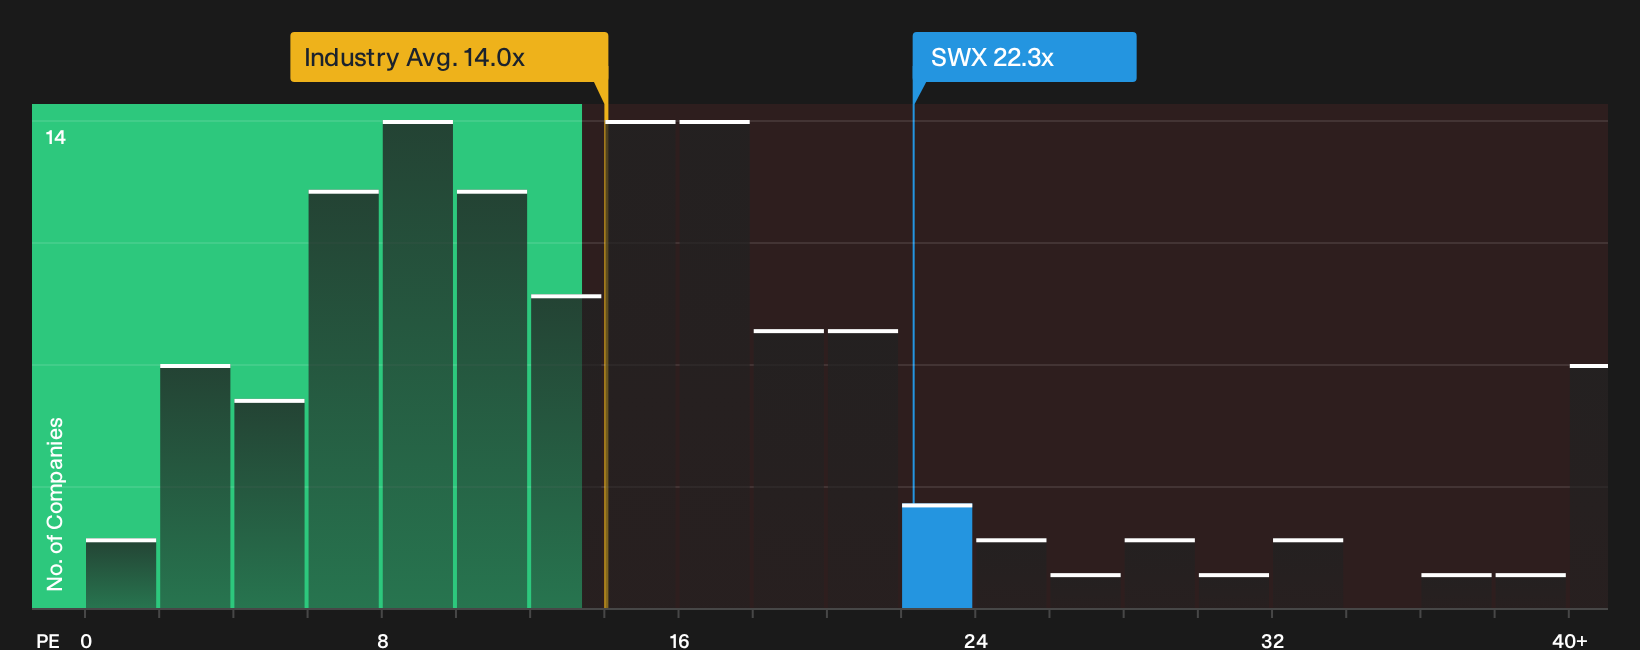
The P/E ratio usually works well for a regulated utility such as Southwest Gas Holdings because earnings are a central focus for both regulators and investors. At a current P/E of 22.3x, the stock trades above the Gas Utilities industry average of 14.0x and above the broader peer group on about 16.3x earnings. That places a relatively rich price on each dollar of the company’s profit compared with many similar gas distributors.
The Fair Ratio, which reflects what investors might expect to pay for Southwest Gas Holdings once its growth outlook, margins, size, and risk profile are accounted for, implies a lower earnings multiple than where the shares now change hands. The present 22.3x P/E therefore sits above that tailored benchmark, so buyers are paying a premium versus what this model suggests for the utility’s fundamentals. That leaves the question of whether the quality and resilience of Southwest Gas Holdings' earnings justify paying up on this measure, or whether the premium multiple may be asking too much at the current price. Explore the numbers behind Southwest Gas Holdings's P/E valuation.
The Southwest Gas Holdings Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where this valuation question leaves off for Southwest Gas Holdings' stock and spell out what would need to happen to growth, profitability, and earnings for today’s price to look either generous or conservative. Rather than a single ratio or one-off fair value line, each scenario lays out the assumptions behind its estimate so you can track how those expectations hold up as quarterly numbers arrive.
One of the top community narratives on Southwest Gas Holdings: 13% undervalued
"Accelerated infrastructure investment opportunities are now anchored by a larger US$2.3b capital plan for the Great Basin 2028 Expansion Project and a broader US$6.3b 5 year utility capital program..."
Discover why this Narrative puts Southwest Gas Holdings at 13% undervalued.
One more piece of the Southwest Gas Holdings puzzle before you act
Before you lean too heavily on today’s multiples, it helps to see how professional forecasters map out Southwest Gas Holdings' earnings path over the next few years and compare that with the current price tag. Explore where analysts expect Southwest Gas Holdings to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com