
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Learn Why The Bull Case For Renishaw Stock Could Change Following Tech Sector Selloff
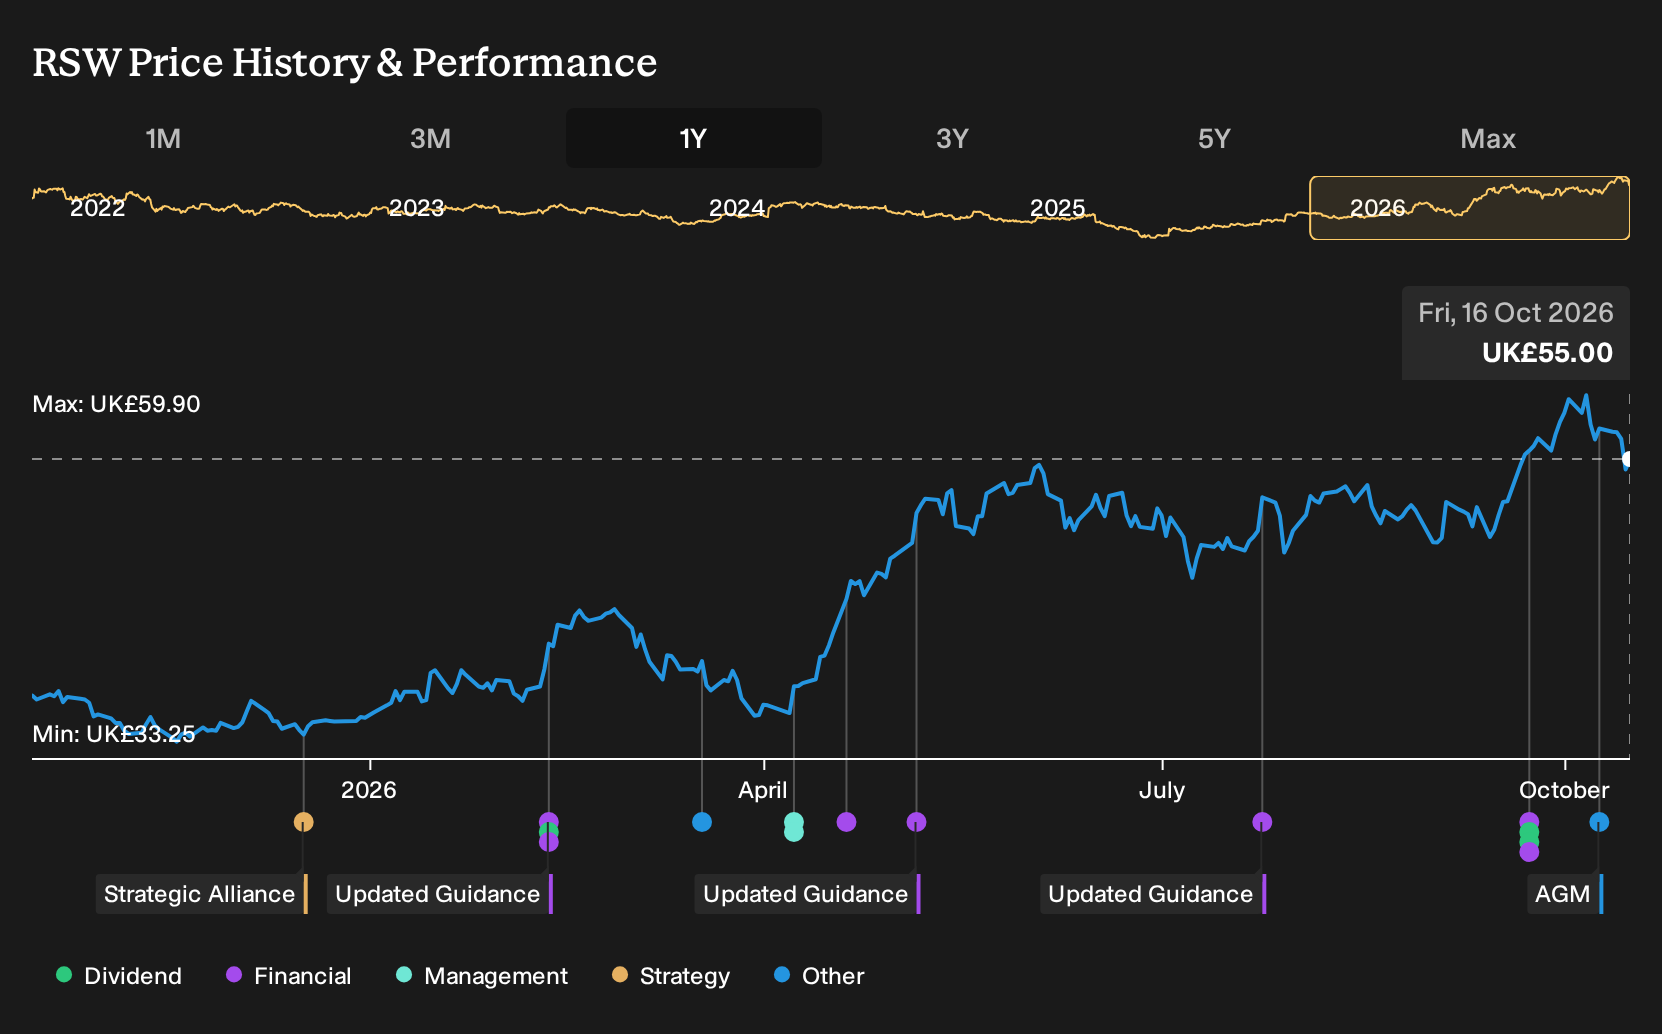
- Renishaw recently saw its shares fall more than 7% as investors pulled back from technology stocks during a wider sector selloff tied to questions over the sustainability of the AI rally.
- The move linked Renishaw more closely to concerns around cost pressures and semiconductor related valuations, even though the broader UK market was supported by positive GDP data and strength in software names.
- We will now look at how Renishaw's investment narrative interacts with the tech selloff that followed doubts over the AI rally.
Pressure test Renishaw against peers by scanning a curated group of 91 robotics and automation stocks to either confirm this pullback or highlight stronger setups elsewhere in the automation theme.
Renishaw Investment Narrative Recap
To own Renishaw, you need to believe its metrology, encoder and additive manufacturing products can maintain relevance across semiconductor, aerospace and advanced manufacturing demand cycles. The short term swing in sentiment around the AI trade mainly affects how the market values that story, rather than the viability of the products or customer relationships.
The key near term catalyst is how solid encoder orders into semiconductor and electronics stay as customers reassess spending after the tech selloff. The biggest operational risk remains a sharp pause in that equipment demand combined with pricing pressure in China, which could test both revenue consistency and the push toward higher margins.
With no fresh company announcements tied directly to the October tech pullback, the most relevant context for Renishaw is still the earlier message around strong encoder demand, a growing order book and the £23m annualised cost reduction programme. Those factors frame whether a sentiment driven share move lines up with what is happening inside the business.
If order momentum in semiconductor, aerospace and defense linked encoder and additive products holds up against this sector wobble, the focus returns to execution on IT upgrades, factory automation and defending pricing against lower cost APAC rivals. For you as a shareholder or potential investor, the real question is whether those internal projects progress as planned while external sentiment remains volatile.
Renishaw's current analyst scenario points to revenue of £1.1b and earnings of £194.5m by 2029, based on an assumed 9.1% yearly increase in revenue and a rise in profit from £119.0m today. This implies an earnings uplift of about £75.5m over that period.
Uncover why Renishaw's fair value indicates an 11% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One bullish twist on Renishaw focuses on its cost reduction and productivity plan. The most optimistic analysts were pencilling in revenue of about £1.1b and earnings near £206.8m by 2029. That is a more upbeat path than the baseline. After a 7% slide tied to the tech selloff, those pre news forecasts may evolve.
Explore 3 other Renishaw fair value estimates, including one that suggests as much as 23% potential upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Renishaw research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Renishaw. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Renishaw's overall financial health at a glance.
Looking For More Ideas Beyond Renishaw?
If the recent Renishaw move has you rethinking sector exposure, it can help to widen the lens and compare this story with other listed businesses that share similar qualities or sit at different points on the risk spectrum.
- For readers who want mispriced quality at the top of their list, start with a curated 7 high quality undervalued stocks that already screen for stronger fundamentals and cleaner balance sheets.
- If resilience matters more to you than chasing every swing, consider scanning a 4 resilient stocks with low risk scores which filters for companies with steadier financial profiles.
- Those hunting for fresher ideas with less crowded shareholder registers can run through a 5 high quality undiscovered gems and see which stories warrant a spot on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com