
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Freshworks (FRSH) Shares Just Moved, So What Is Going On?
Freshworks index inclusion and earnings spark investor interest
Freshworks (FRSH) has come into focus after being added to multiple S&P indices and reporting a Q2 update that topped analyst revenue expectations, along with upgraded full-year EPS guidance.
The stock has risen 18.2% since that earnings release, as investors weigh the index inclusions alongside management’s confidence in AI-powered SaaS products across customer support, IT service, sales, and marketing workflows.
Freshworks now trades at US$13.74, with a 30-day share price return of 12.16% and a 90-day gain of 24.34%. The 1-year total shareholder return of 26.29% contrasts with a 3-year total shareholder return that remains down 25.93%, signalling improving momentum after a tougher longer-term stretch as investors reassess growth and risk following the earnings beat and index additions.
Seize this Freshworks momentum shift to size up other AI-focused SaaS players, screened for quality and financial strength through our curated 38 profitable AI stocks that aren't just burning cash.After a sharp rerating on index inclusion and upbeat guidance, Freshworks now faces a cleaner question for new capital: Does the current valuation still leave enough upside to justify the AI and SaaS execution risks investors are taking?
Most Popular Narrative: 4% Undervalued
Freshworks closed at $13.74 compared with a narrative fair value of $14.38, so the widely followed thesis sees modest upside relative to today’s price while still anchoring expectations to a fairly tight valuation band.
The rapid adoption of AI-powered features (such as Copilot and Agentic AI) across both new and existing Freshworks customers is outpacing internal expectations, with over 5,000 paying customers and high attach rates in large deals; as AI monetization expands and early-access Agentic products move to paid solutions, management expects this to materially boost revenue growth and average selling prices in 2026 and beyond.
See why 33 investors see Freshworks as 4% undervalued.
The most popular narrative applies an 8.55% discount rate and arrives at a fair value of $14.38, only 4.5% above the current share price. This keeps the implied upside tight and puts most of the debate on whether Freshworks can earn the earnings multiple that is embedded in those forecasts.
Analysts in that narrative expect revenue growth of about 14.3% a year and earnings of $60.4 million by 2029, with a P/E of roughly 64x on those future earnings, compared with the current P/E of 19.4x and the US Software sector on 31.7x today.
That gap between today’s multiple and the implied future valuation places a lot of weight on successful AI monetisation, employee experience adoption and share count reduction. At the same time, those same analysts also forecast earnings to decline by an average of 8.2% a year over the next 3 years and profit margins to compress from 20.5% to 4.5%.
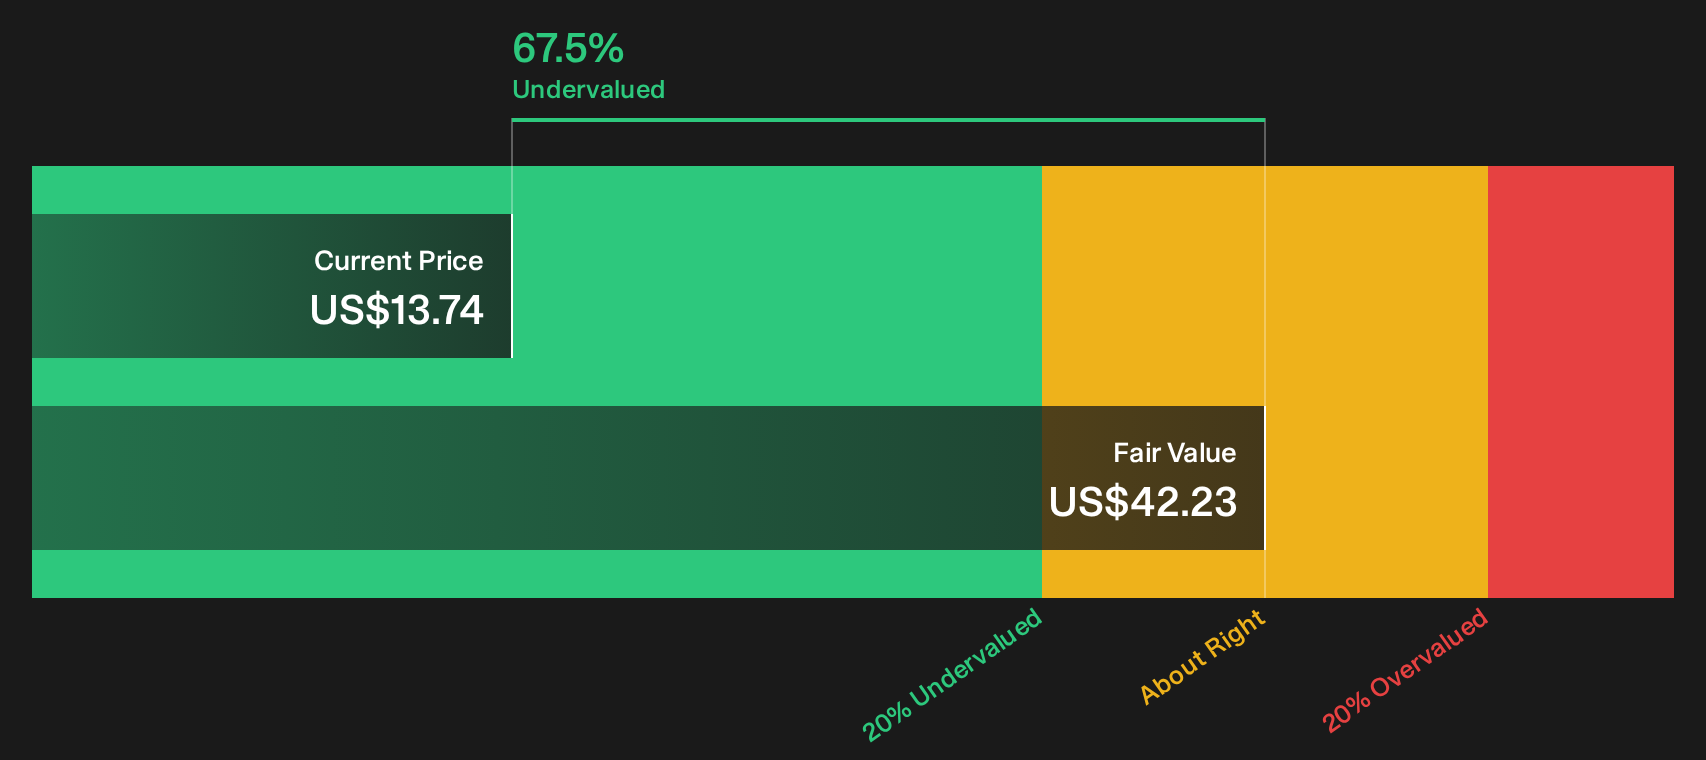
For readers comparing this to other software stocks, it is worth noting that the same framework still labels Freshworks as “good value” on a discounted cash flow basis, with an estimated future cash flow value of $42.23 per share and the narrative itself tagged as “undervalued,” even though the headline fair value of $14.38 only sits slightly above where the stock trades now.
Result: Fair Value of $14.38 (UNDERVALUED)
Still, the Freshworks narrative can be knocked off course if AI monetisation remains limited to a small fraction of customers or if larger rivals increase pricing pressure and churn.
Find out about the key risks to this Freshworks narrative.
Another view on Freshworks valuation
Freshworks looks inexpensive based on our DCF model, which estimates a future cash flow value of $42.23 per share compared with the current $13.74 price. That difference suggests a very different picture from the tight 4% upside in the popular narrative and raises a simple question: Which set of assumptions do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed views on whether the current Freshworks story leans more toward opportunity or risk. Act while the data is fresh, review the full spread of sentiment, and weigh both the upside and the concerns through 2 key rewards and 2 important warning signs.
Want more ideas beyond Freshworks?
Do not stop with one opportunity. Broaden your watchlist with a few focused stock ideas filtered for quality, resilience, and different ways to generate returns.
- Target reliable income and see which companies show up as potential yield workhorses through the 8 dividend fortresses.
- Hunt for potential bargains by scanning companies that combine stronger fundamentals with discounted valuations using the 33 high quality undervalued stocks.
- Prioritise capital preservation and steady compounding by filtering for resilient businesses with healthier risk profiles via the 32 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com