
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Hingham Institution for Savings (HIFS) Stock Price Faces Q3 Earnings Squeeze
Hingham Institution for Savings just posted its Q3 2026 report and the headline looks far less dramatic than the mood usually seen on bank earnings days. The share price slipped a mild 0.2% to about US$293, even as net profit margin for the trailing year sat at 53.8% and quarterly net interest margin printed at 2.23%. That tiny move signals that investors are still processing a more complicated story, where strong profitability metrics collide with questions about how much earnings power the bank is really being valued for.
Love Hingham Institution for Savings' 53.8% net profit margin but unsure whether a 2.23% net interest margin justifies the current pricing risk. Benchmark it against a curated group of banks and lenders in our list of solid balance sheet and fundamentals stocks (25 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$25.666 million vs US$30.627 million (down 16.2%)
- Net Income (Q3 2026 vs Q3 2025): US$12.674 million vs US$17.295 million (down 26.7%)
- Basic EPS (Q3 2026 vs Q3 2025): US$5.76 vs US$7.93 (down 27.3%)
- Net Interest Margin, or NIM (Q3 2026 vs Q3 2025): 2.23% vs 1.74% (higher by 0.49 percentage points)
Tired of scrolling through dense earnings tables and trying to piece together what it all means for Hingham Institution for Savings? See the full financial picture in clean charts that spotlight valuation and context around the recent results in our company report for Hingham Institution for Savings..
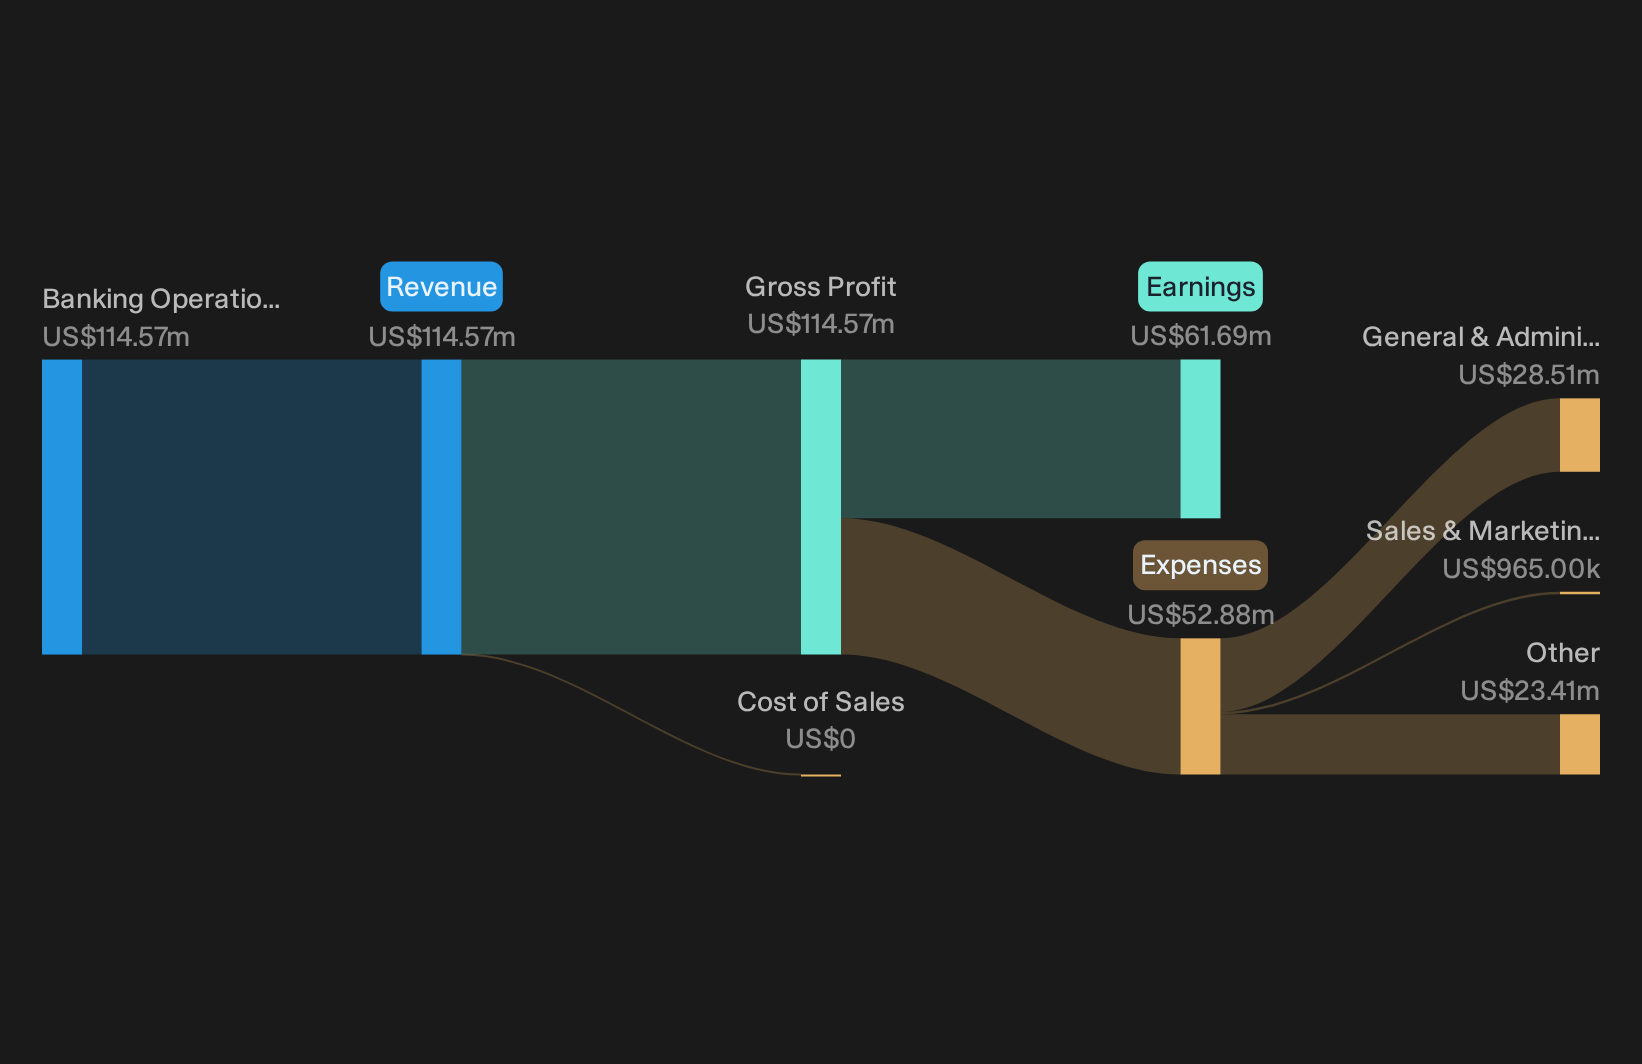
Hingham bullish story meets firmer margin trend
For anyone leaning into the conservative regional bank angle, Hingham Institution for Savings just gave you one clear support. Net interest margin, a key earnings engine for a traditional lender, improved to 2.23% while the trailing net profit margin held at 53.8%. That combination indicates the basic deposit and loan model is still generating solid economics. Even with revenue and earnings lower year on year, the recent 7 day share return of about 1.8% suggests investors have not rushed to abandon the stability narrative.
Profit pressure tests the conservative bank narrative
The flip side is harder to ignore. Revenue declined 16.2% and net income fell 26.7% versus Q3 2025, which means Hingham Institution for Savings is earning less from the same straightforward business model that investors often praise for its simplicity. Basic EPS decreased from US$7.93 to US$5.76. Over 30 days the stock is down about 3.5%, indicating that some holders are weighing whether this traditional regional lender is more exposed to the interest rate and credit cycle than the calm headline margins suggest.
After a 16.2% slide in revenue and a 26.7% drop in net income, the risk question is not just about one soft quarter. Review whether Hingham Institution for Savings is showing early structural cracks or if this is an overreaction by scanning the independent risk analysis for Hingham Institution for Savings which shows 3 important warning signsHunt For Quiet Mispricings
Hingham Institution for Savings just reminded you how clean headline metrics can mask deeper questions about earnings power. The real opportunity is spotting companies that could be undervalued before expectations and prices meet.
- Company 1 - 41% below our estimate - uses specialty deposit niches and a relaunched payments platform to pursue higher fee-based revenue.
- Company 2 - 33% below our estimate - converts a large AI infrastructure contract backlog and expanding multicloud databases into subscription and licensing income from enterprise clients.
- Company 3 - 46% below our estimate - integrates a significant acquisition to widen its Pacific footprint while targeting earnings from lower cost deposits and conservative loan growth.
Three companies from the same screener. Open every one of the 33 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com