
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
How Investors May Respond To Berkshire Hathaway (BRK.A) Homebuilding Push
- Berkshire Hathaway has expanded its U.S. housing exposure through acquiring Taylor Morrison, building stakes in major homebuilders, and formalizing its Lennar position in a recent regulatory filing.
- The push into homebuilding, combined with Greg Abel’s concentrated bets on Apple, American Express, Alphabet, and select tech driven investments, is reshaping Berkshire Hathaway’s earnings mix and risk profile.
- The next area of attention is how Berkshire Hathaway’s heavier homebuilding exposure under Greg Abel could influence its broader investment narrative.
Berkshire Hathaway Investment Narrative Recap
Berkshire Hathaway appeals to shareholders who want a sprawling operating mix of insurance, rail, utilities, housing and a concentrated equity portfolio working together over long periods. That belief now has to include comfort with Greg Abel’s tilt toward homebuilding and tech exposure, plus modest forecast revenue growth and pressure on earnings over the next few years.
The key near term swing factor remains how well Berkshire Hathaway executes on utilities, insurance expansion and housing against higher interest rate sensitivity and leadership transition risk. The Lennar related regulatory filing looks process oriented rather than transformational, so it does not materially change the immediate business catalyst or primary risk.
The Lennar Schedule 13G that Berkshire Hathaway submitted to the Federal Energy Regulatory Commission matters mainly because it crystallizes how embedded homebuilding has become in the group. Formalizing Lennar alongside Taylor Morrison, MF1 and other stakes makes housing more central to Berkshire Hathaway’s earnings mix and more exposed to interest rate and affordability pressures.
That extra housing tilt sits next to concentrated positions in Apple, American Express and Alphabet and newer tech driven bets like Bending Spoons. For you as an investor, the catalyst is execution across these clusters without stretching the balance sheet, while the risk is that softer housing or slower equity portfolio contribution drags on already challenged earnings forecasts.
Berkshire Hathaway's current analyst narrative assumes revenue of US$448.5b and earnings of US$53.1b by 2029, based on 5.3% yearly revenue growth and an earnings decline of US$32.7b from US$85.8b today.
Uncover why Berkshire Hathaway's fair value aligns with its current price.
Exploring Other Perspectives
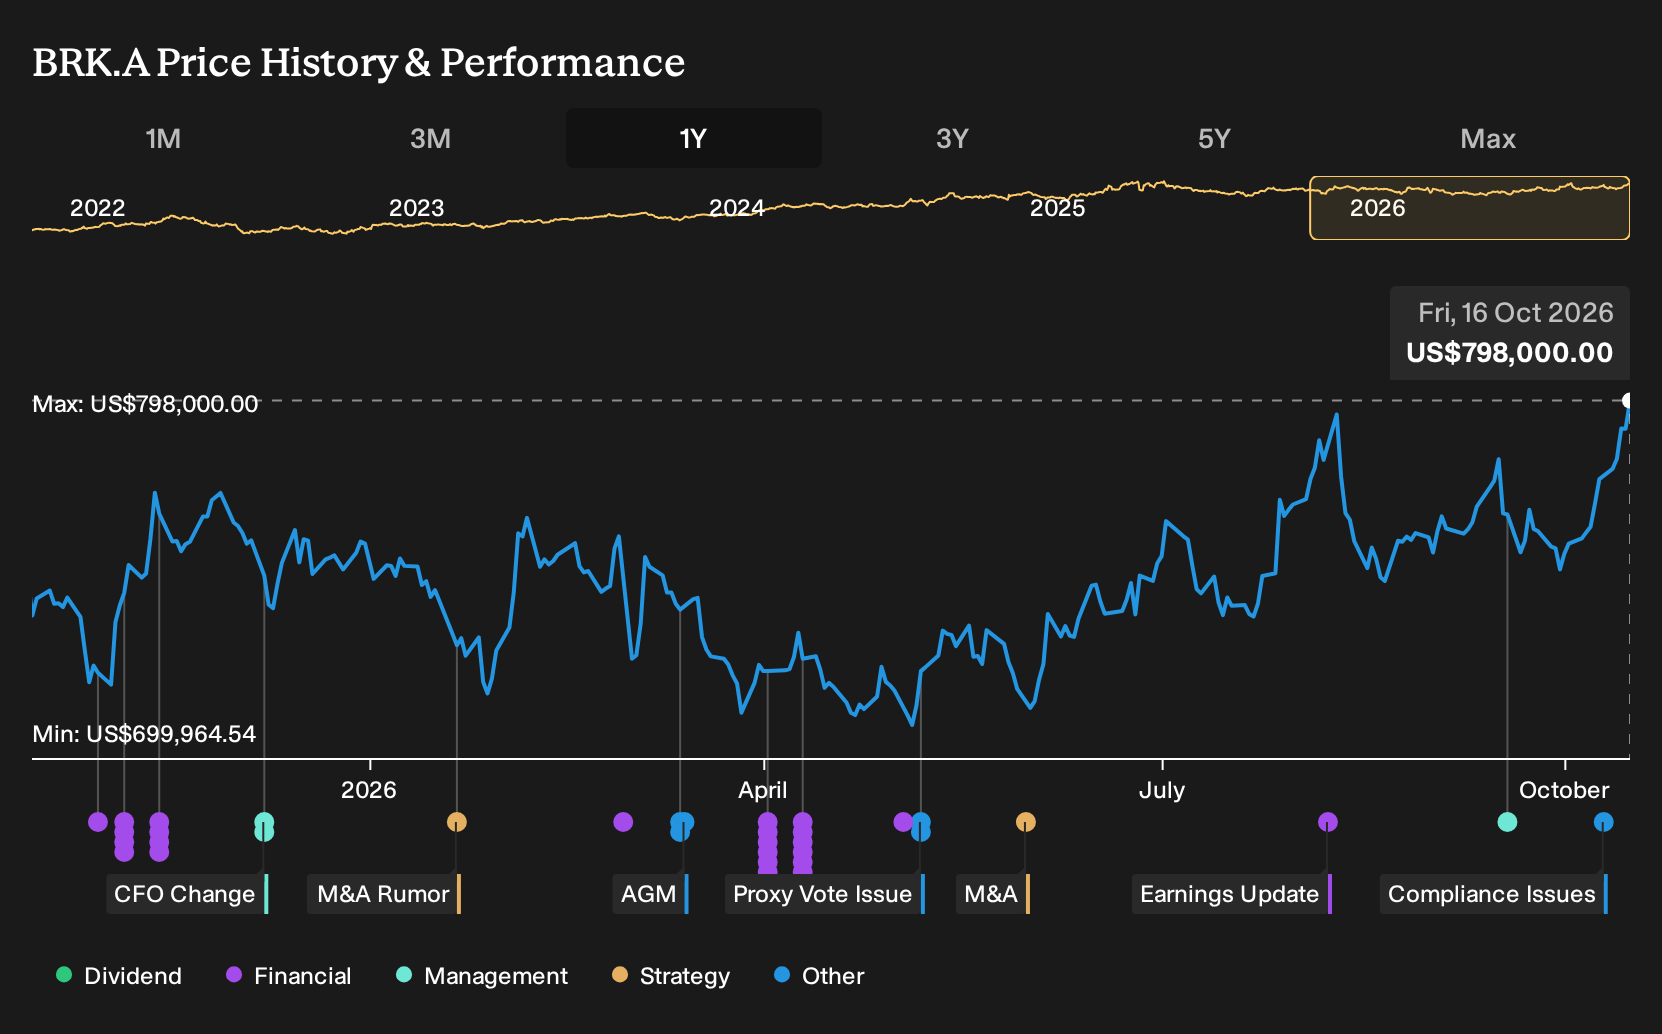
Five fair value estimates from the Simply Wall St Community span roughly US$799,503 to US$1,183,090 per Berkshire Hathaway share, so community views already stretch wide before factoring in the Lennar filing or heavier homebuilding tilt. Use that spread, along with leadership transition and data center utility risks, as a prompt to compare several alternative viewpoints.
Explore 4 other Berkshire Hathaway fair value estimates, including one that suggests up to 48% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your Berkshire Hathaway research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Berkshire Hathaway. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Berkshire Hathaway's overall financial health at a glance.
Looking for more Berkshire Hathaway style investment ideas?
Once you have a view on Berkshire Hathaway, it can help to scan a wider set of companies that pair solid fundamentals with different sources of risk and return. The Simply Wall St Screener offers a few focused starting points if you want to broaden your watchlist beyond a single conglomerate.
- If capital preservation and smoother portfolio swings matter most to you, consider using the screener that highlights 32 resilient stocks with low risk scores so you can focus on resilience first.
- For readers who want financial strength without overpaying, filter for companies with solid cash generation and conservative leverage through the list of solid balance sheet and fundamentals (25 results) to see which businesses pass those checks.
- If you prefer to hunt for less crowded opportunities with room for fresh coverage, scan through the 20 high quality undiscovered gems and see which ideas merit a spot on your research list.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com