
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Elementis (LSE:ELM) Draws Fresh Value Interest After Cash Flow Focus Turns Heads
Recent commentary around Elementis (LSE:ELM) has zeroed in on its free cash flow forecasts and cost simplification efforts, prompting fresh questions about whether the current valuation fully reflects those cash generative expectations.
Elementis shares have been building momentum, with a 30-day share price return of 8.94% and a 90-day move of 14.46% helping lift the stock to £1.852. A 1-year total shareholder return of 16.90% and 3-year total shareholder return of 80.86% frame that strength against a longer record as investors reassess cash flow prospects and perceived risk.
Compare Elementis' cash focused story with a curated set of companies that pair strong balance sheets with value style pricing through our 7 high quality undervalued stocks.
After that kind of run, the temptation is to wait for Elementis to cool off. Or does the current price already offer enough value based on the cash on offer?
Most Popular Narrative: 13% Undervalued
Elementis is framed as undervalued in the most followed narrative, with a fair value of £2.13 set against the recent close at £1.85 and a discount rate of 7.97% anchoring that view.
The company's increased focus on high-growth specialty additives following the divestiture of commoditized and carbon-intensive Talc and Chromium businesses positions Elementis to benefit from rising global demand for advanced, sustainable materials in urbanization-driven end markets such as personal care and coatings, supporting both topline revenue growth and higher operating margins.
See why 2 investors see Elementis as 13% undervalued.
Result: Fair Value of £2.13 (UNDERVALUED)
Still, the Elementis story depends on higher margins and focused additives remaining on course, without being affected by weaker innovation spend or sharper competition in key end markets.
Find out about the key risks to this Elementis narrative.
Another View: Elementis On Earnings Multiples
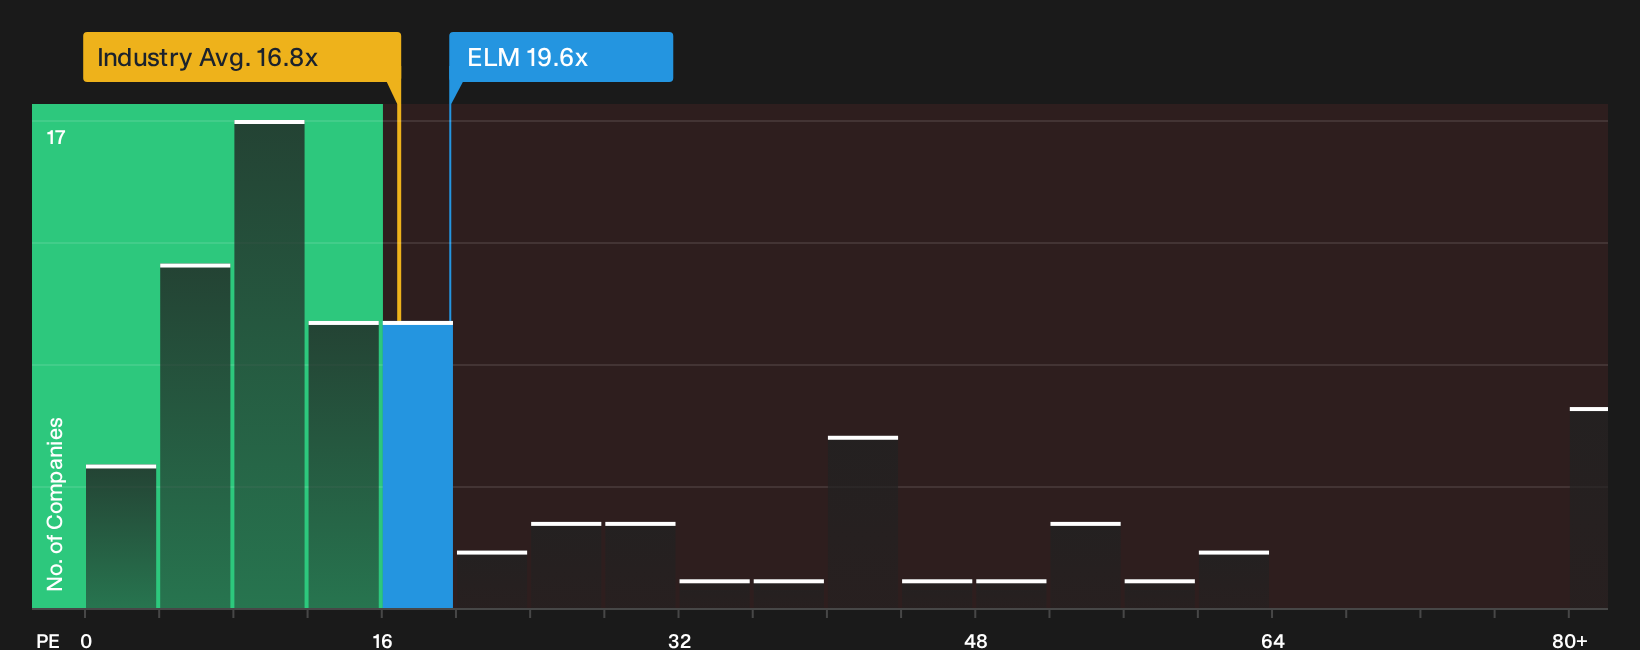
Elementis may screen as undervalued on fair value estimates, but its current P/E of 19.6x is higher than the European Chemicals sector at 16.8x and well above a fair ratio of 13.4x. That gap points to valuation risk if sentiment cools or earnings delivery disappoints.
To see how that earnings multiple compares in more detail, and what the fair ratio implies for future repricing, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If this Elementis story appears finely balanced between opportunity and risk, consider taking action while the data is fresh and pressure test it yourself through the 3 key rewards.
Looking for more Elementis style investment ideas?
Elementis may sit at the center of your watchlist today, but you give yourself a stronger edge when you compare it with a wider set of opportunities.
Use the Simply Wall Street Screener to pressure test your thinking, spot fresh ideas, and avoid missing quality stocks that quietly fit your checklist.
- Target resilient compounding by scanning a 4 resilient stocks with low risk scores that focuses on businesses with stronger balance sheets and lower risk profiles than the market average.
- Hunt for tomorrow's leaders before the crowd pays attention by working through a curated 5 high quality undiscovered gems with solid fundamentals behind them.
- Anchor your shortlist around financial strength by filtering for a list of solid balance sheet and fundamentals (9 results) so you are comparing Elementis against companies built on firmer footing.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com