
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Eaton (ETN) Dropped, What Is Driving Attention Now?
Eaton (ETN) has reshuffled a key finance role, with former Senior Vice President and Controller Adam Wadecki moving to Senior Vice President, Finance, Electrical, and Andrea Trabacchin stepping in as principal accounting officer.
Eaton’s reshuffle in finance comes after a choppy few weeks for the shares. The 7-day share price return is down 8.94% and the 30-day share price return is down 7.89%, even though the year-to-date share price return is still up 19.54% and the 5-year total shareholder return is 160.36%. This indicates that longer term momentum remains strong while near term sentiment has cooled.
See how Eaton fits into the broader power and infrastructure theme by checking out the hand-picked 41 power grid technology and infrastructure stocks that are also reacting to grid upgrade and electrification demand.
Eaton shares have cooled after a strong multi year run, which puts the spotlight squarely on price. Is most of the easy upside already spent, or does the recent pullback reset the valuation case?
Most Popular Narrative: 24% Undervalued
Eaton last closed at $391.25, while the most followed valuation narrative points to a fair value near $517. This sets up a clear tension between recent share weakness and a much higher long run price anchor.
Eaton Corporation (NYSE: ETN) is one of the rare institutions that has managed to turn the physical constraints of heavy industry and metallurgy to its advantage. Its monopolistic position, benefiting from high material constraints (GOES), years-long delivery times, and in-cabinet thermal densities of 120 kW, along the Voltage Cascades from a 400,000-volt grid to 1 volt on a chip, has provided the company with an unsurpassable economic moat.
See why 14 investors see Eaton as 24% undervalued.
Result: Fair Value of $517 (UNDERVALUED)
Still, Eaton’s thesis leans heavily on sustained AI infrastructure build outs and tight transformer supply, so any slowdown in data center capex or easing GOES constraints could blunt that 24% undervaluation case.
Find out about the key risks to this Eaton narrative.
Another View: Eaton Looks Fully Priced on Earnings
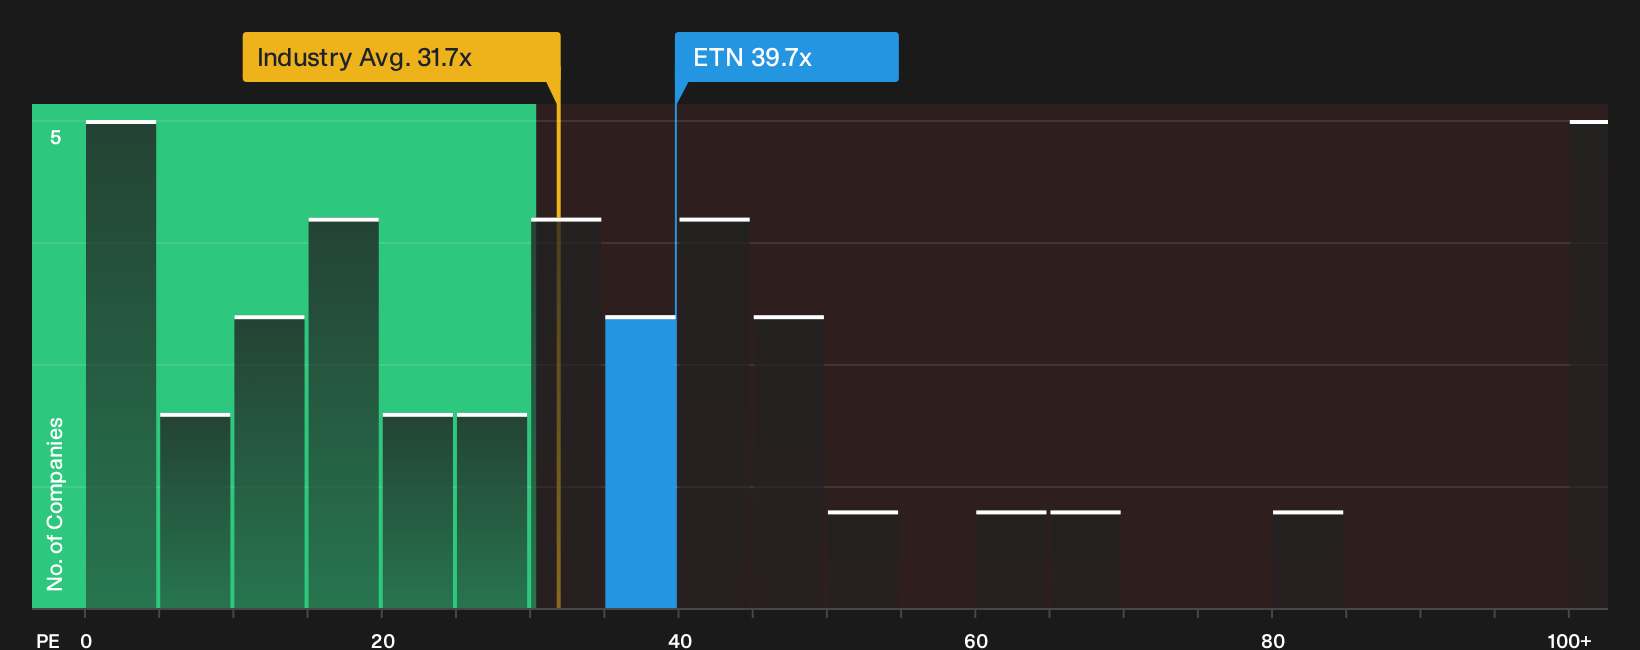
The crowd-sourced fair value of $517 paints Eaton as 24% undervalued. The P/E picture is far less generous. At 39.7x earnings, the stock trades above the US Electrical industry on 31.7x and only slightly above a 39x fair ratio that our model suggests the market could lean toward.
That gap means the upside case relies on the current rich multiple at least holding, while any slide toward the sector or fair ratio levels would work against shareholders even if profits track forecasts. Which version of Eaton do you trust more: the narrative-driven fair value, or a market that already prices the shares at a premium?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Eaton leaves you unsure, move quickly to check the underlying data and pressure test your own thesis with the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Eaton?
If Eaton has sharpened your focus on quality, do not stop here. Broaden your watchlist with a few focused screens that surface very different types of opportunities.
- Chase asymmetric upside by scanning a tightly filtered set of higher risk, higher potential opportunities through the 14 elite penny stocks with strong financials.
- Target quality at a discount by reviewing the 33 high quality undervalued stocks that combine solid fundamentals with valuations that still look reasonable.
- Prioritise resilience and balance sheet strength by working through the list of solid balance sheet and fundamentals (25 results) that keep financial risk in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com