
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Entergy (ETR), What Is Drawing Fresh Attention Now?
Entergy (ETR) has drawn fresh attention after recent trading left the stock around $105.11, with short term returns mixed between the past week, month, and past 3 months. Investors are reassessing the utility’s longer run profile.
Recent trading has been mildly positive, with a 1-day share price return of 1.11% and a 30-day share price return of 3.04%. However, the 90-day share price performance is down 6.08%, which tempers the otherwise constructive year to date share price return of 11.99% and 1-year total shareholder return of 12.40% for Entergy.
Scan beyond Entergy and see how other utilities and essential infrastructure stocks compare on quality and value in our hand picked 32 resilient stocks with low risk scores.
Bulls point to Entergy’s recent gains and steady utility profile, while bears focus on the 3 month pullback and valuation risk. Which side does the current price actually support as the numbers stack up?
Most Popular Narrative: 14% Undervalued
Against Entergy’s last close of $105.11, the most followed narrative anchors fair value at about $122.68. This frames the recent pullback as a potential gap between price and longer term earnings power.
Substantial long term electricity demand growth from industrial development, population migration to the Gulf South, and large scale data center expansions in Entergy’s service territory now includes approximately 7 to 12 GW of hyperscale data center potential, 3 to 5 GW of traditional industrial demand, and signed agreements with AWS and Meta that together support the updated outlook for roughly 8.5% to 9% annual retail sales growth, which could lift regulated revenue and earnings over time.
See why 26 investors see Entergy as 14% undervalued.
Result: Fair Value of $122.68 (UNDERVALUED)
Still, the Entergy story comes with pressure points, including potential regulatory pushback on large projects and the risk that capital needs outstrip current financing plans.
Find out about the key risks to this Entergy narrative.
Another View: Entergy On Earnings Multiples
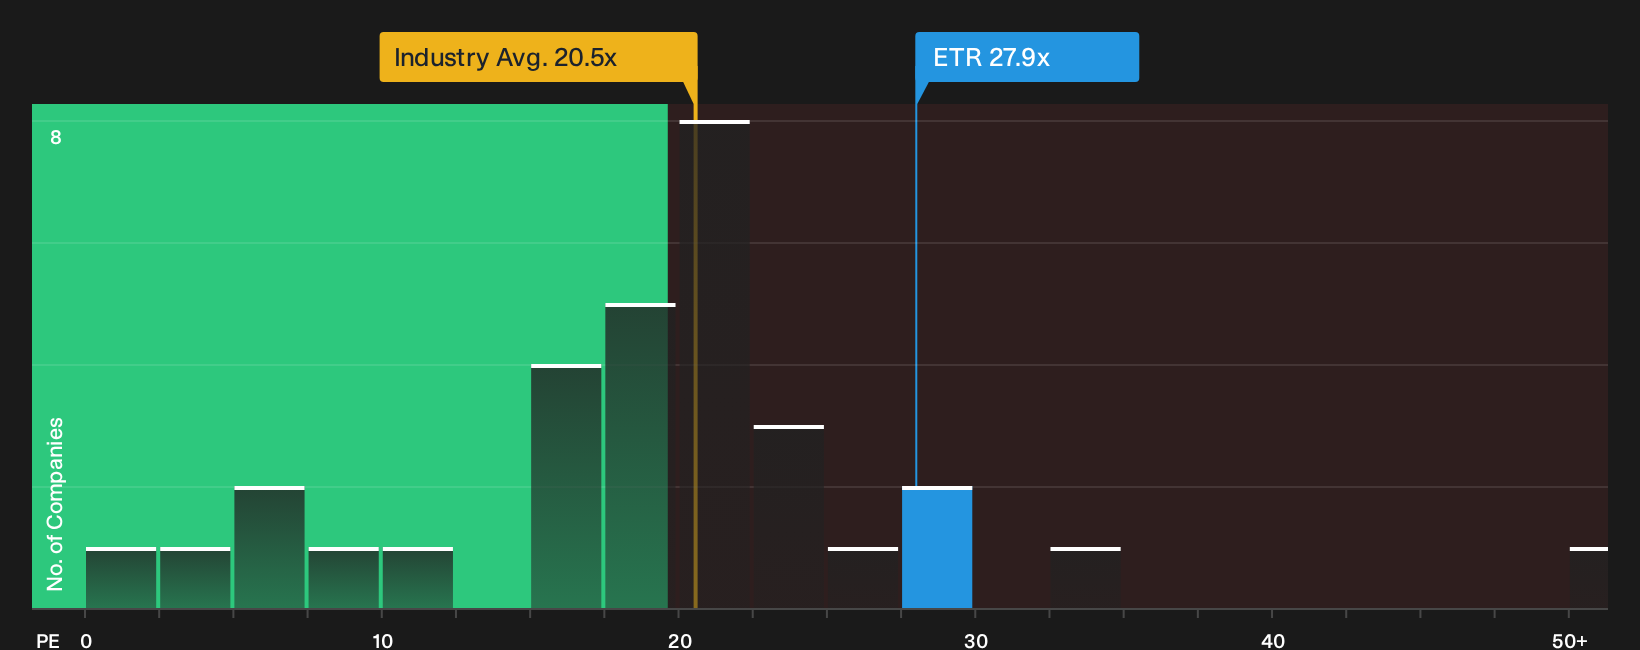
The fair value narrative around Entergy leans on long term growth and capital plans. On current numbers though, the stock trades on a P/E of 27.9x, compared with an estimated fair ratio of 23.5x, the US Electric Utilities sector at 20.5x, and peers at 17.2x. That premium points to valuation risk if the growth story stumbles. This raises a key question: which signal do you trust more, the story or the sticker price?
For a closer look at how this earnings based view stacks up against other ways of pricing Entergy, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views like this only matter if you pressure test them yourself using the underlying numbers and risk flags. To see both sides of the Entergy story quickly and form your own judgement, start with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Entergy?
If Entergy has sharpened your thinking, do not stop here. Broaden your watchlist and pressure test fresh ideas built from the same data driven process.
- Target potential mispricing by scanning companies flagged as 33 high quality undervalued stocks that pair strong fundamentals with what could be conservative market expectations.
- Strengthen your income stream by reviewing the 8 dividend fortresses that focus on higher yields supported by underlying cash generation.
- Guard the downside first by checking our list of solid balance sheet and fundamentals (25 results) to see which businesses keep leverage and funding risk in tighter check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com