
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
MakeMyTrip (MMYT) Heads Into October Results With Fair Value Still In Focus
MakeMyTrip (MMYT) has set a clear near term catalyst, with fiscal 2027 second quarter financial and operating results due before markets open on October 26, 2026, followed by a management Zoom webinar.
Recent trading has been choppy for MakeMyTrip, with the share price down about 15% over the past 90 days and the year-to-date share price return lower by 43.1%. However, the 5-year total shareholder return of 73.93% points to longer-term momentum built on earlier gains.
Scan beyond MakeMyTrip ahead of its results and compare this pullback with a curated 32 high quality undervalued stocks featuring similar businesses where price and fundamentals may be starting to diverge.
The recent slide in MakeMyTrip now meets a wide spread between the current US$46.60 share price and valuation estimates near US$73.40. Where does fair value really sit in that gap?
Most Popular Narrative: 38% Undervalued
On the most followed narrative, MakeMyTrip screens as undervalued, with a fair value anchor of $75.40 against the recent $46.60 close. This places significant attention on how its business mix evolves from here.
The shift of Indian travel from occasional to recurring consumption, with customers taking more frequent leisure, family, pilgrimage and short break trips across both air and ground transport, gives MakeMyTrip a larger base of repeat transactions to drive gross bookings and revenue.
Expansion of higher margin, non air segments such as hotels and packages, bus ticketing, intercity cabs and tours and activities, which have been growing faster than air and now contribute a larger share of adjusted margin, is expected to support blended margin improvement and adjusted operating profit.
What is behind 10 investors see MakeMyTrip as 38% undervalued.
Result: Fair Value of $75.40 (UNDERVALUED)
Still, the narrative around MakeMyTrip can be knocked off course if elevated oil prices keep air travel subdued or if the India listing and US$1.6b convertibles result in earnings dilution.
Find out about the key risks to this MakeMyTrip narrative.
Another View On MakeMyTrip’s Valuation
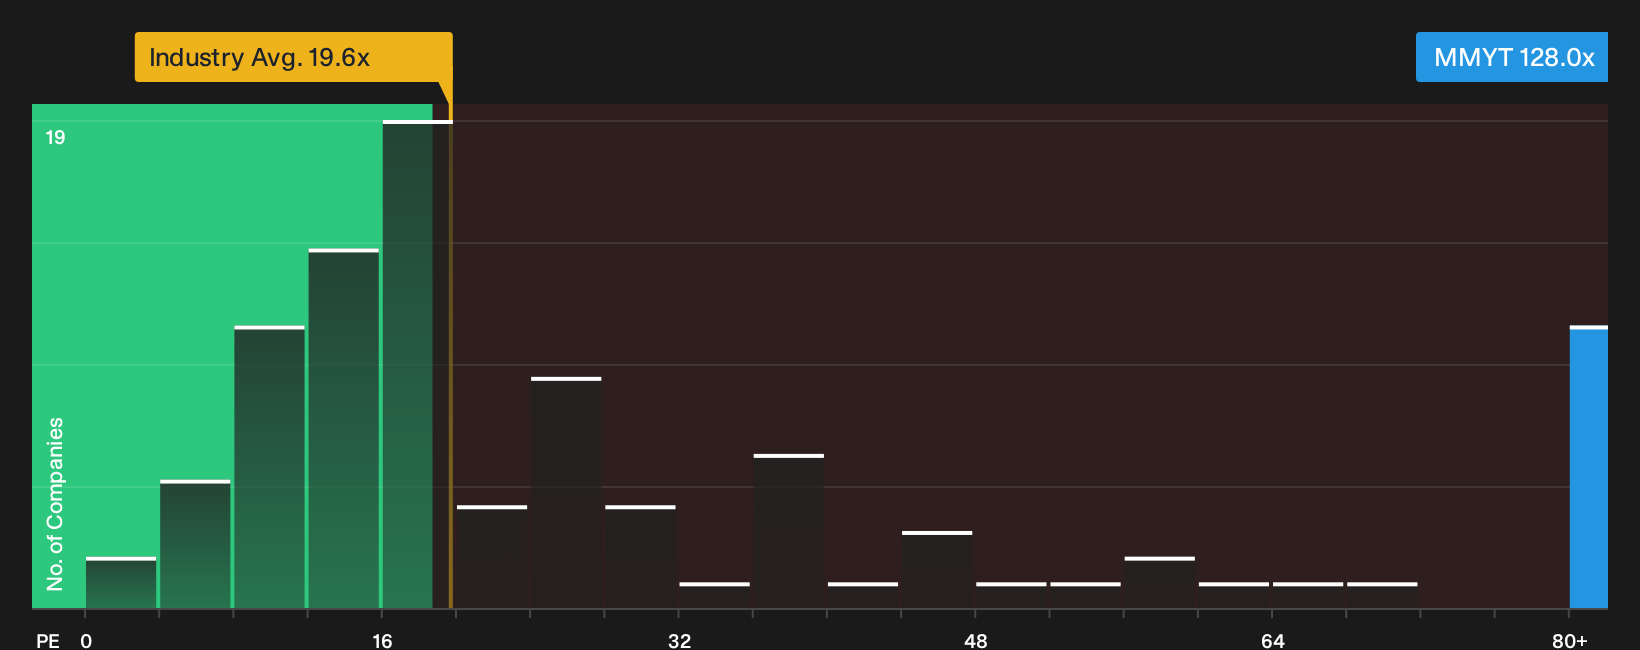
The story changes once price multiples are brought in. MakeMyTrip trades on a P/E of 128x, while the US Hospitality group sits at 19.7x and the fair ratio is 45.5x. That is a large gap. Is the market overpaying for the growth story you just read?
For a closer look at how this earnings multiple could reset over time, and what that might mean for future return potential, see the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around MakeMyTrip’s valuation and business momentum can be interpreted in different ways, so move quickly and consider the full picture for yourself using the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond MakeMyTrip?
Do not stop at one opportunity. Broaden your watchlist with a few targeted stock ideas that match how you like to balance risk, quality and income.
- Spot potential mispricings early and review a curated 32 high quality undervalued stocks where fundamentals and share prices appear to be pulling in different directions.
- Strengthen the defensive side of your portfolio and scan a list of solid balance sheet and fundamentals (25 results) that can help you focus on financial resilience first.
- Hunt for lesser known opportunities with strong numbers and track a 20 high quality undiscovered gems before broader attention starts to close the valuation gap.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com