
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
NCC (OM:NCC B) Wins Fresh Nordic Contracts Following An Undervalued Narrative
New Nordic projects put NCC stock in focus
NCC (OM:NCC B) just added three sizable Nordic contracts, together worth several hundred million SEK, including heritage refurbishments in Helsinki and Turku and a new swim and bowling center in Örkelljunga.
NCC’s recent contract wins arrive while the share price sits at SEK175.0, with a 3-month share price return of 3.24% but a year-to-date share price decline of 20.60%, and a 3-year total shareholder return of 80.90% that contrasts with a 12.97% decline over the past year.
Scan other Nordic construction and infrastructure plays that show similar contract momentum to NCC using our hand picked list of solid balance sheet and fundamentals (205 results) as a starting universe.
Order momentum is clear at NCC, while the share price has already given back a chunk of its multi year gains. Is most of the re rating already done, or does current pricing still leave meaningful upside on the table?
Most Popular Narrative: 14% Undervalued
NCC last closed at SEK175, while the most followed narrative anchors fair value at SEK202.5, implying a discount that catches the eye for a construction group with fresh Nordic orders coming in.
The company's strong financial position and balance sheet readiness for selective mergers and acquisitions (M&A) can act as a catalyst for future revenue growth and margin expansion. Positive outlook for key contracting segments such as water treatment, energy generation, and infrastructure suggests potential for sustained revenue growth.
See why 11 investors see NCC as 14% undervalued.
Result: Fair Value of SEK202.5 (UNDERVALUED)
Still, a muted property transaction market and pricing pressure from smaller competitors could quickly challenge the bullish NCC narrative if project economics tighten.
Find out about the key risks to this NCC narrative.
Another View: NCC through the SWS DCF lens
While the popular narrative leans on a SEK202.5 fair value anchored in earnings forecasts and target P/E, the SWS DCF model points in a very different direction. On this cash flow view, NCC at SEK175 trades well above an estimated value of SEK62.51, which frames the stock as expensive rather than discounted.
Two models pointing in opposite directions leaves you with a choice about which set of assumptions you find more realistic and which risks you are most comfortable with.
Look into how the SWS DCF model arrives at its fair value.
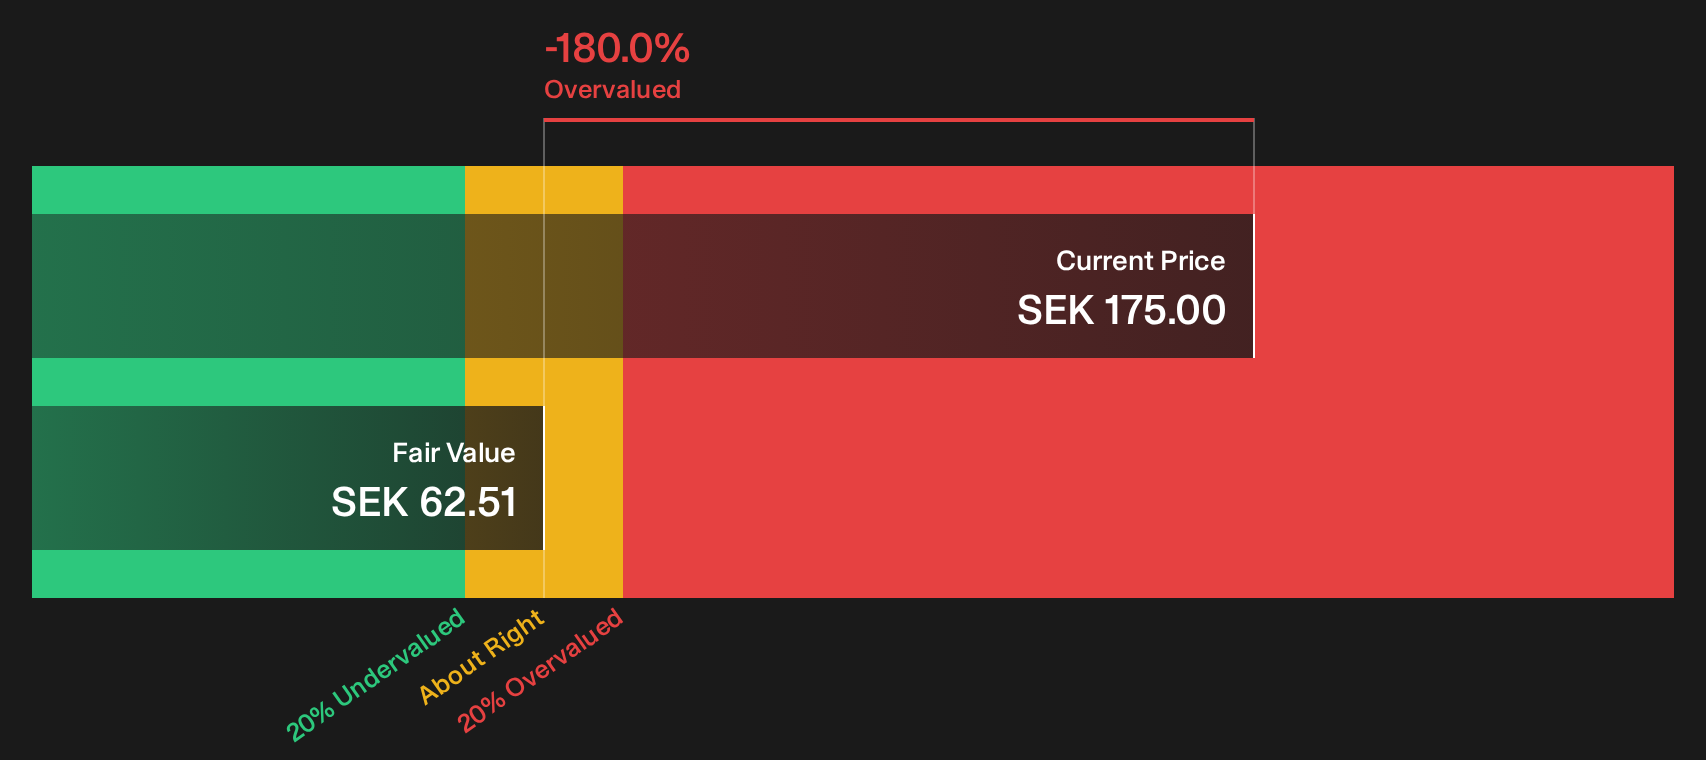
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NCC for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 190 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on NCC can create noise, yet the real edge comes from checking the underlying data yourself and weighing the trade off between optimism and concern. To pressure test both sides of the argument in one place, start with our breakdown of 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond NCC?
Do not stop with NCC. A broader watchlist gives you options when stories change and new opportunities appear, especially when those candidates have been pre filtered for quality signals.
- Target potential mispricing as you review our 190 high quality undervalued stocks that combine stronger fundamentals with discounted share prices.
- Sharpen your search for income ideas by scanning the 215 dividend fortresses that may offer higher yields with sturdier payouts.
- Limit unpleasant surprises by focusing on the 234 resilient stocks with low risk scores that show more resilient risk profiles across key checks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com