
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Will Premium Brand Launches Change Williams Sonama's Stock Narrative
- Popsmith previously announced a nationwide rollout of its stovetop popcorn poppers in Williams-Sonoma stores in Fourth Quarter 2026, alongside Pottery Barn’s Ashley Stark collaboration that adds more than 50 design-led pieces across furniture, lighting, and decor.
- The combination of a premium kitchen gadget rollout and a design-forward Pottery Barn collection suggests that Williams-Sonoma is placing greater emphasis on differentiated merchandise to attract holiday and gifting demand, even as it manages ongoing operational pressures.
- We will now explore how Williams-Sonoma’s nationwide Popsmith launch could influence the existing investment narrative around its omni-channel strengths.
Scan other retailers that pair premium brands with design-led assortments and may be building similar momentum to the current moves of Williams-Sonoma by reviewing our hand-picked 20 high quality undiscovered gems
Williams-Sonoma Investment Narrative Recap
To stay invested in Williams-Sonoma, you need to believe its omni-channel model, digital tools, and design forward brands can keep pulling in customers even while the broader housing market stays sluggish and tariffs plus fuel costs weigh on margins. The near term swing factor is whether engagement from AI platforms, B2B, and emerging concepts offsets any softness in big ticket demand.
The biggest risk still sits with external costs and demand, not with one product rollout. Popsmith and the Ashley Stark collaboration may help holiday mix and full price selling, but they do not fundamentally change exposure to trade policy, freight, or any lingering controls issues that could pressure earnings if they resurface.
The Popsmith nationwide launch at Williams-Sonoma ahead of holiday trading is the most relevant announcement here. It lines up neatly with the existing catalyst of higher conversion through curated, differentiated assortments, layered onto a strong e commerce base. It also leans into the company’s premium positioning rather than chasing lower margin volume.
For you as an investor, the key question is execution. If Popsmith drives incremental traffic and attachment online and in store without heavy discounting, it supports the case that Williams-Sonoma can protect its 14.7% net margin and high return on equity. If freight, tariffs, or a weak housing backdrop absorb those gains, the rollout becomes more of a branding win than a financial one.
Williams-Sonoma's current analyst narrative points to revenues of $9.4b and earnings of $1.3b by 2029, based on an assumed 5.4% yearly revenue growth rate and a move from $1.2b of earnings today to that 2029 consensus, which implies an increase of about $0.1b in profit over the period.
Uncover why Williams-Sonoma's fair value is roughly in line with its current price.
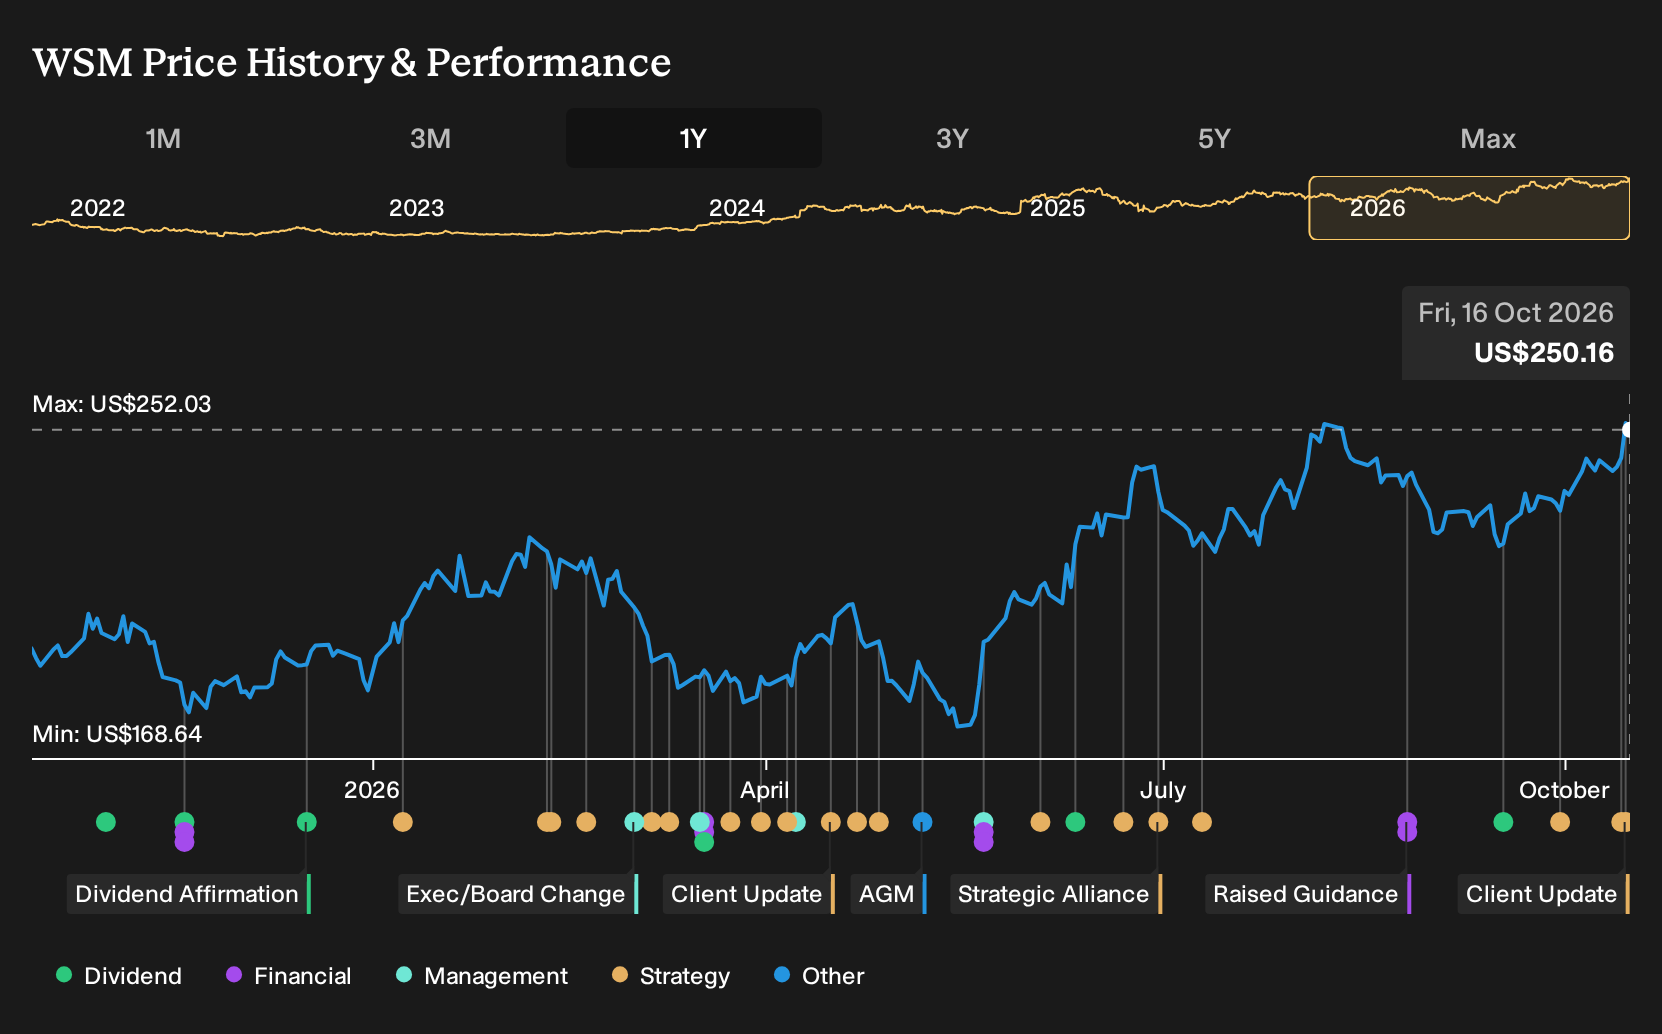
Exploring Other Perspectives
One alternate view puts store closures and revenue pressure at the center of the Williams-Sonoma story. The most bearish analysts were penciling in about US$9.3b of revenue and US$1.3b of earnings by 2029, with a lower 21.0x P/E. You might see this new Popsmith rollout and Ashley Stark collection as a real test of that more cautious script.
Explore 2 other Williams-Sonoma fair value estimates, including one that suggests it could be worth just $246.35.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Williams-Sonoma research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Williams-Sonoma. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Williams-Sonoma's overall financial health at a glance.
Looking for more investment ideas beyond Williams-Sonoma?
Once you have formed a view on Williams-Sonoma, it can help to cross-check that thesis against other potential opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you quickly filter for stocks that match the kind of balance sheet strength, value tilt, or yield focus you want to compare.
- If capital preservation is high on your list, consider reviewing a curated set of companies with steadier profiles through our 32 resilient stocks with low risk scores.
- For readers who care most about financial resilience, look at businesses with stronger balance sheets and fundamentals using this targeted list of solid balance sheet and fundamentals (25 results).
- If value is your priority, you can scan for potentially mispriced opportunities with a hand-picked 33 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com