
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Award Win Could Be A Key Moment For M.P. Evans Group Stock (AIM:MPE)
- M.P. Evans Group recently received the Best Investor Communications award at the 2026 AIM Awards after reporting interim revenue growth of 9%, a 25% rise in pre-tax profit and a higher dividend supported by firm palm oil prices.
- The recognition centers on how management addressed commodity price swings, sustainability questions and export regulation uncertainty, giving investors clearer visibility on cash generation and dividend capacity.
- We will now look at how M.P. Evans Group's award winning investor communication could influence the broader investment narrative around the business.
Expand your watchlist beyond M.P. Evans Group by scanning our curated list of solid balance sheet and fundamentals (9 results) that, like MPE, pairs clear communication with resilient financial footing.
M.P. Evans Group Investment Narrative Recap
An investor in M.P. Evans Group needs to be comfortable with a fairly concentrated agricultural operation that hinges on Indonesian and Malaysian palm oil yields, local tax regimes and pricing for certified sustainable product. The recent award for investor communications does not change those fundamentals, but it does suggest you are getting clearer disclosure around cash generation and capital allocation.
In the near term, the key catalyst is how effectively new planted areas and existing mills are run while firm palm oil prices hold. The biggest operational risk remains weather and regulatory pressure in Indonesia, which can quickly influence yields, export volumes, tax levies and in turn margins and dividend headroom.
The most relevant update linked to this award is the interim result where M.P. Evans Group reported 9% revenue growth, a 25% rise in pre tax profit and a higher dividend, supported by firm palm oil prices. Management also used that moment to spell out how export regulation and commodity swings were affecting cash flow rather than leaving investors to guess.
For you as a shareholder, that matters because future catalysts such as higher output from North Sumatra and East Kalimantan, more certified sustainable volumes or further land around existing mills all rely on disciplined capital spend and funding. Clearer commentary around regulation and pricing does not remove risks such as weather, tax or currency moves, but it can make it easier to track whether execution is staying on plan.
M.P. Evans Group's current analyst narrative points to forecast 2029 revenue of $353.3 million and earnings of $101.5 million, based on an assumed yearly revenue decline of 3.1%. That implies earnings would fall by $22 million from $123.5 million today to reach that 2029 consensus level.
Uncover why M.P. Evans Group's fair value indicates a 10% potential upside to its current price, which could narrow quickly.
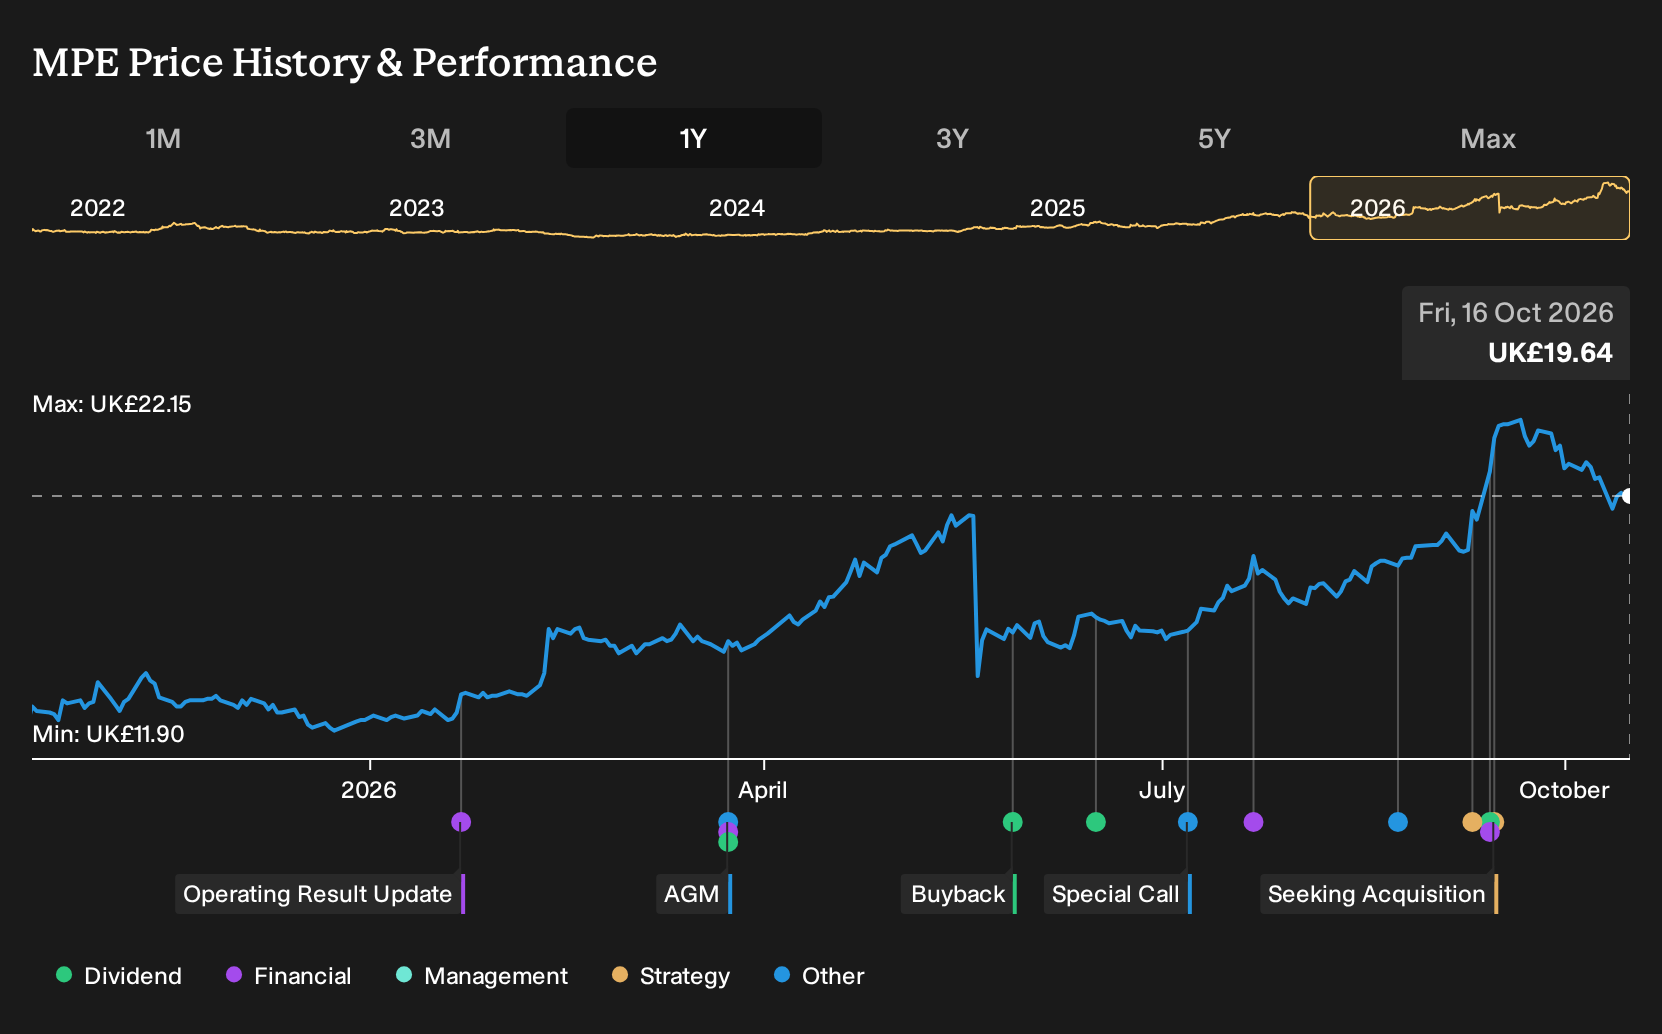
Exploring Other Perspectives
One alternate view on M.P. Evans Group leans hard into El Niño risk. Those analysts were modelling revenue of about $340.8 million and earnings of $93.4 million by 2029, well below consensus. That more pessimistic path has not been updated for the award win, so you may see forecasts shift as opinions adjust.
Explore 4 other M.P. Evans Group fair value estimates, including one that suggests as much as 29% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your M.P. Evans Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for M.P. Evans Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate M.P. Evans Group's overall financial health at a glance.
Looking for more M.P. Evans Group style investment ideas?
If you like the way M.P. Evans Group combines clearer disclosure with real operating detail, it can help to compare it with other opportunities that share a similar focus on fundamentals. The Simply Wall St Screener lets you filter for the kind of balance sheet strength, income potential or under the radar quality that fits your own approach.
- If capital preservation sits high on your list, start with a basket of 4 resilient stocks with low risk scores that score well on resilience and financial strength.
- For investors who want quality but do not want to overpay, scan a curated set of 5 high quality undiscovered gems with healthier fundamentals than their current attention suggests.
- If income matters and you care about consistency, compare M.P. Evans Group with a group of 2 dividend fortresses that pair higher yields with sturdier balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com