
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Does Revenue Growth With Lower Profit Change The Bull Case For Zigup (LSE:ZIG)?
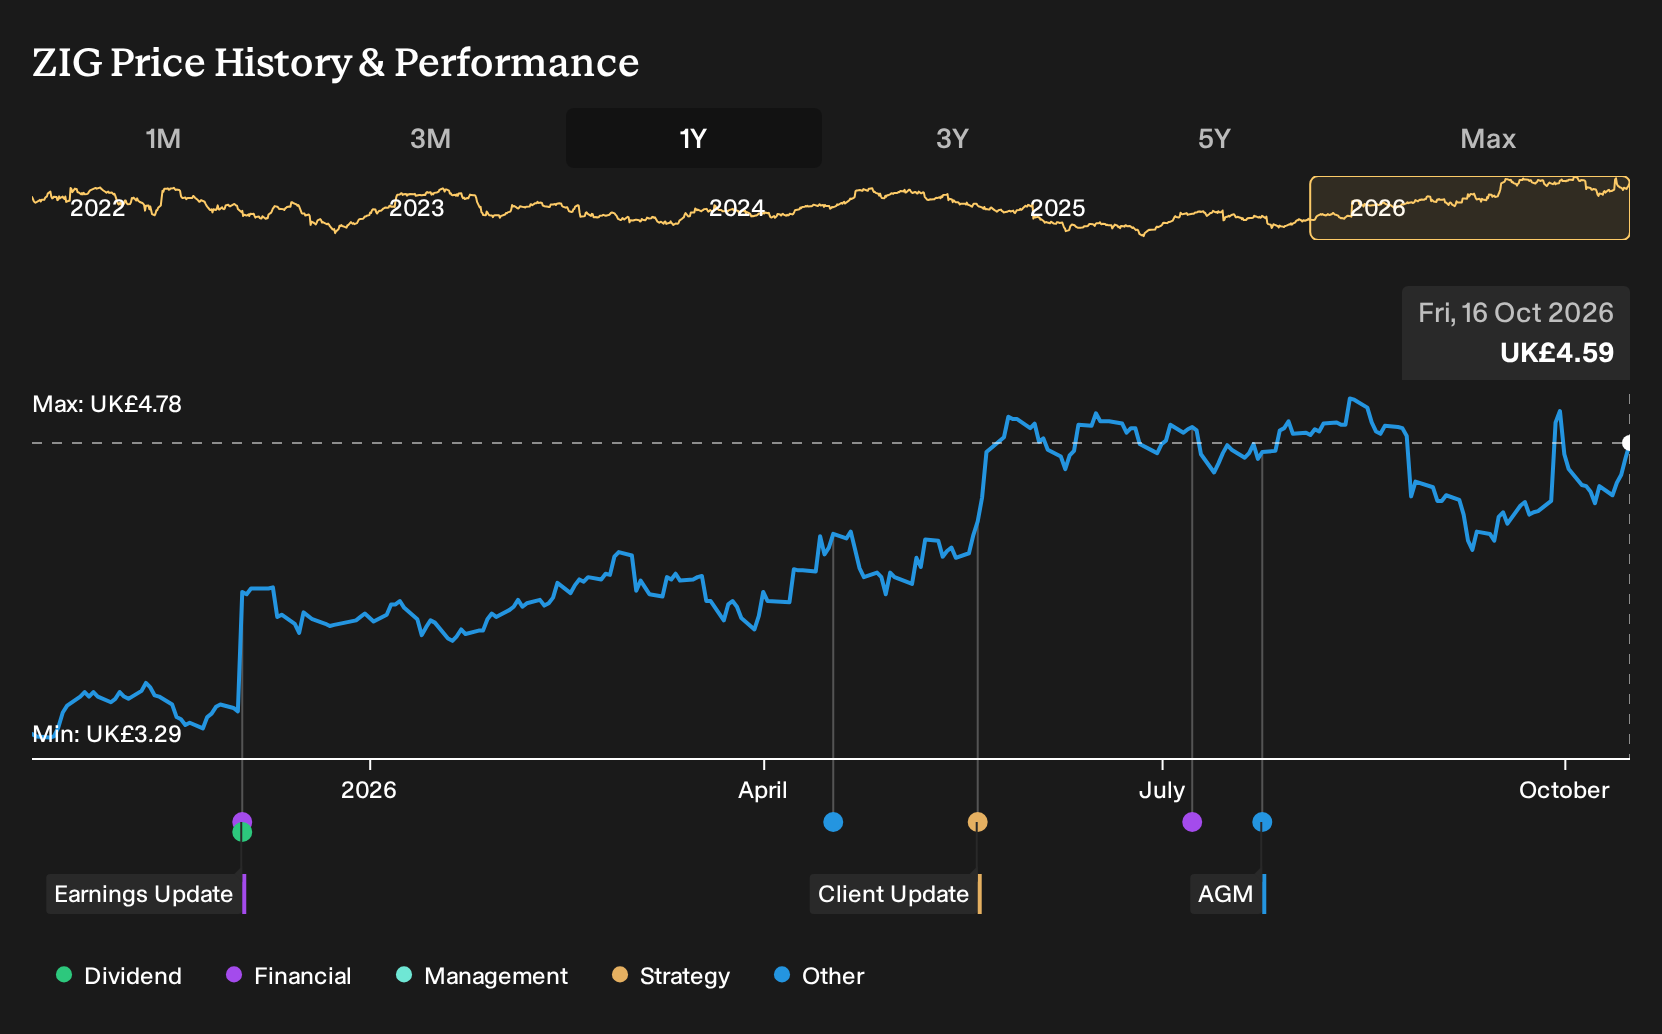
- Zigup's H2 2026 results showed higher revenue alongside weaker net income and margin, reflecting heavy spending on fleet and technology.
- The figures highlight a core tension for Zigup between funding digital expansion and fleet needs on the one hand, and maintaining profit resilience and cash discipline on the other.
- We now examine how Zigup's investment narrative is affected by revenue growth occurring at the same time as pressure on net income margins.
Compare Zigup's push into digital rentals and capital-heavy assets with other balance-sheet focused players by scanning our hand-picked list of solid balance sheet and fundamentals (9 results), which may be better aligned with your risk profile.
Zigup Investment Narrative Recap
To stay invested in Zigup, you need to be comfortable with a rental and services group that is prioritising digital tools and a larger fleet while accepting weaker net profit margins for now. The immediate swing factor is whether this heavier H2 2026 spending can translate into better EBIT margins and more consistent operating cash in the next few reporting periods.
The biggest near term risk is that rising wage costs, a lower margin Claims & Services mix and higher fleet replacement spending squeeze profitability faster than efficiency gains or pricing can offset. If disposal gains continue to normalise and one off items recur, the pressure on reported earnings and debt coverage could remain elevated.
The recent H2 2026 earnings update is the clearest operational signal. Revenue expanded but net income and margin fell, which matters when disposal profits are already normalising and leverage is edging toward the top of management guidance. That combination keeps balance sheet resilience and cash conversion right at the centre of the Zigup story.
With no fresh regulatory filings or deal announcements tied to this period, the most relevant context is the ongoing investment program management has outlined in fleet modernisation, digital platforms and repair capabilities. These projects are intended to support higher utilisation and lower unit costs over time. However, they also keep capital needs and debt high, so execution quality around returns on that spending is the key catalyst to watch.
What The Current Zigup Forecasts Assume
Zigup's narrative projects £2.1b revenue and £130.7 million earnings by 2029, based on analyst models that feed into the current price targets for the stock. This implies 4.4% yearly revenue growth and an earnings increase of about £54.5 million from £76.2 million today.
Uncover why Zigup's fair value indicates a 20% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
For Zigup, the key alternate angle is cash. The most cautious analysts saw revenue still reaching about £2.1b and earnings near £134.0 million by 2029, yet argued the share was already fairly priced on a 9.9x P/E. That is far more pessimistic on re rating potential. The latest results could push those expectations in either direction; treat this as one of several viewpoints to explore.
Explore 3 other Zigup fair value estimates, including one that suggests as much as 9% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zigup research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Zigup. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zigup's overall financial health at a glance.
Looking for more Zigup investment ideas?
If the latest Zigup update has sharpened your thinking about balance sheets, cash flows and risk, it can be useful to line it up against a broader watchlist of potential opportunities using the Simply Wall St Screener.
- For investors who want quality at a reasonable entry point, review 7 high quality undervalued stocks that combine solid fundamentals with more conservative pricing.
- If income stability ranks high for you, scan a curated set of 2 dividend fortresses that focus on higher yields with defensive characteristics.
- When capital preservation is the priority, filter for 4 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com