
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Is Keyera (TSX:KEY) Still Below Fair Value As Midstream Demand Draws Fresh Attention?
Why Keyera Is Back On Investor Radar
Keyera (TSX:KEY) is back in focus as energy price volatility and renewed demand for Canadian midstream capacity drive fresh scrutiny of its operations, cash generation, and adherence to guidance.
Recent trading has been lively. The share price is now at CA$55.78, with a 1-day share price return of 3.30% adding to a 30-day share price return of 4.61%. However, the 90-day share price return declined 6.96%, even as the 1-year total shareholder return reached 36.25% and the 5-year total shareholder return climbed 131.13%. This suggests near term momentum has cooled, even though longer term performance has been strong.
Benchmark your thesis on Keyera against a curated set of resilient infrastructure and energy plays by scanning our 8 resilient stocks with low risk scores, which is built around balance sheet strength and steadier return profiles.
The recent climb in Keyera’s share price still leaves a gap to both analyst targets and intrinsic value estimates. The key issue now is where fair value actually sits within that spread.
Most Popular Narrative: 13% Undervalued
Keyera’s most followed narrative pegs fair value at CA$64 per share, compared with the latest close of CA$55.78. The gap between price and that thesis is still meaningful if the assumptions hold.
The company’s updated outlook for fee-based adjusted EBITDA per share growth from 2025 through 2029, supported by filling capacity on KAPS and other assets and by sanctioned projects such as KAPS Zone 4, KFS Frac 3 and ACE Rail, points to a multi-year period where incremental volumes can contribute to higher revenue and operating earnings.
See why 29 investors see Keyera as 13% undervalued.
Result: Fair Value of CA$64 (UNDERVALUED)
Still, the narrative around Keyera could crack if Western Canadian production slows, or if the Plains acquisition drags through higher maintenance and regulatory friction.
Find out about the key risks to this Keyera narrative.
Another View On Keyera’s Valuation
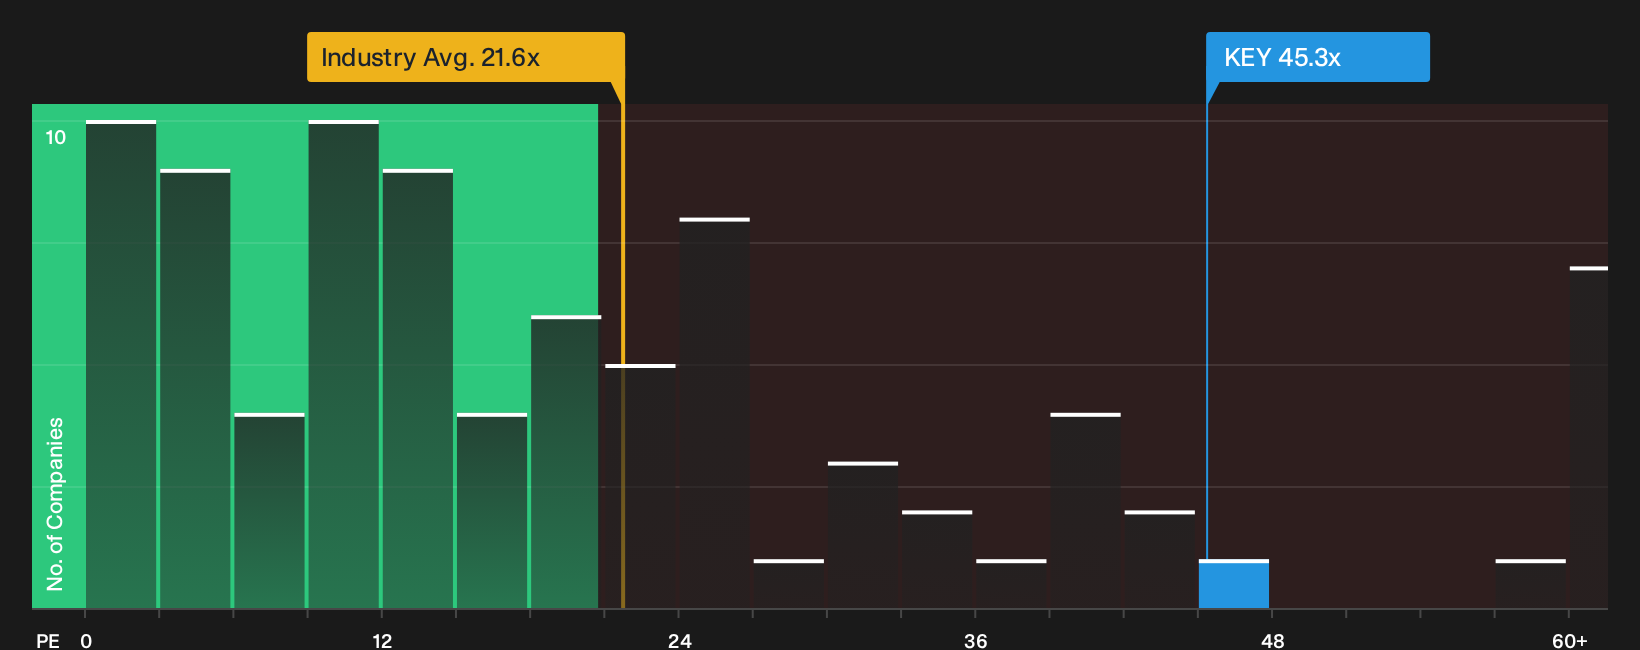
The fair value story around Keyera shifts once the focus moves to earnings multiples. The stock trades on a P/E of 45.3x, while the Canadian oil and gas group is at 20.9x, the peer average is 24.9x, and the fair ratio sits at 22.3x. That gap points to meaningful valuation risk if sentiment cools.
See what the numbers say about this price by reviewing the See what the numbers say about this price — find out in our valuation breakdown.. The next question is whether that premium stays in place if earnings or cash flow expectations change.
Next Steps
Mixed signals on Keyera’s valuation and risk reward profile make this a moment to move quickly, review the underlying data yourself, and weigh both sides of the story through the 2 key rewards and 4 important warning signs.
Looking For More Ideas Beyond Keyera?
If you stop with Keyera, you risk missing other opportunities that could fit your goals even better, so broaden your research using the Simply Wall Street Screener.
- Target potential mispricing by scanning a curated pool of resilient businesses through the 5 high quality undervalued stocks.
- Lock in potential income ideas by reviewing companies that appear in the 3 dividend fortresses.
- Focus on financial resilience by screening for companies featured in the list of solid balance sheet and fundamentals (8 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com