
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
Should Cloud Customer Wins Require Action From Akamai (AKAM) Investors?
- Akamai Technologies reported a new wave of customer adoption for its cloud computing services, with software, media, logistics, healthcare, and developer platforms shifting high performance CPU, GPU, and storage workloads onto Akamai Cloud across APJ and EMEA.
- The move by enterprises to run AI training, low latency inference, and disaster recovery on Akamai infrastructure, including NVIDIA RTX PRO 6000 Blackwell Server Edition GPU instances, signals deeper reliance on Akamai for both performance sensitive and cost constrained workloads previously hosted on larger hyperscalers.
- This surge in GPU driven Akamai Cloud adoption could influence the company’s wider investment narrative and risk balance.
Akamai Technologies Investment Narrative Recap
To own Akamai Technologies, you need to believe the shift from a shrinking legacy delivery business into higher value security and cloud infrastructure really plays out at scale. The latest wave of AI focused cloud wins supports that mix shift by showing real workloads choosing Akamai for GPU, storage, and Kubernetes hosting rather than only for content delivery.
The near term swing factor is whether this operational traction converts into profitable use of the heavy AI CapEx tied to Anthropic and other CIS contracts. The biggest risk remains that these GPU and CPU deployments do not reach targeted cash gross margins, which would pressure non GAAP operating margins and earnings.
The fresh customer momentum on Akamai Cloud matters most when set against the US$11.6b Anthropic CPU contract and roughly US$14.4b of total CIS commitments analysts track. Those multiyear take or pay deals already frame the long runway. New GPU intensive users in APJ and EMEA plug into the same build out and help validate capacity decisions.
It also sharpens the execution bar. Management is leaning into roughly US$5.5b of Anthropic related CapEx and an expected 40% of 2026 revenue going into infrastructure, while earnings forecasts point to mid teens annual growth. The more GPU heavy migrations like these keep landing, the more investors can test whether that spend is earning its keep.
Akamai Technologies' current analyst script points to revenues of US$7.2b and earnings of US$738.3m by 2029, based on an assumed 18.8% yearly revenue growth rate and an earnings increase of about US$327.3m from the US$411.0m reported today.
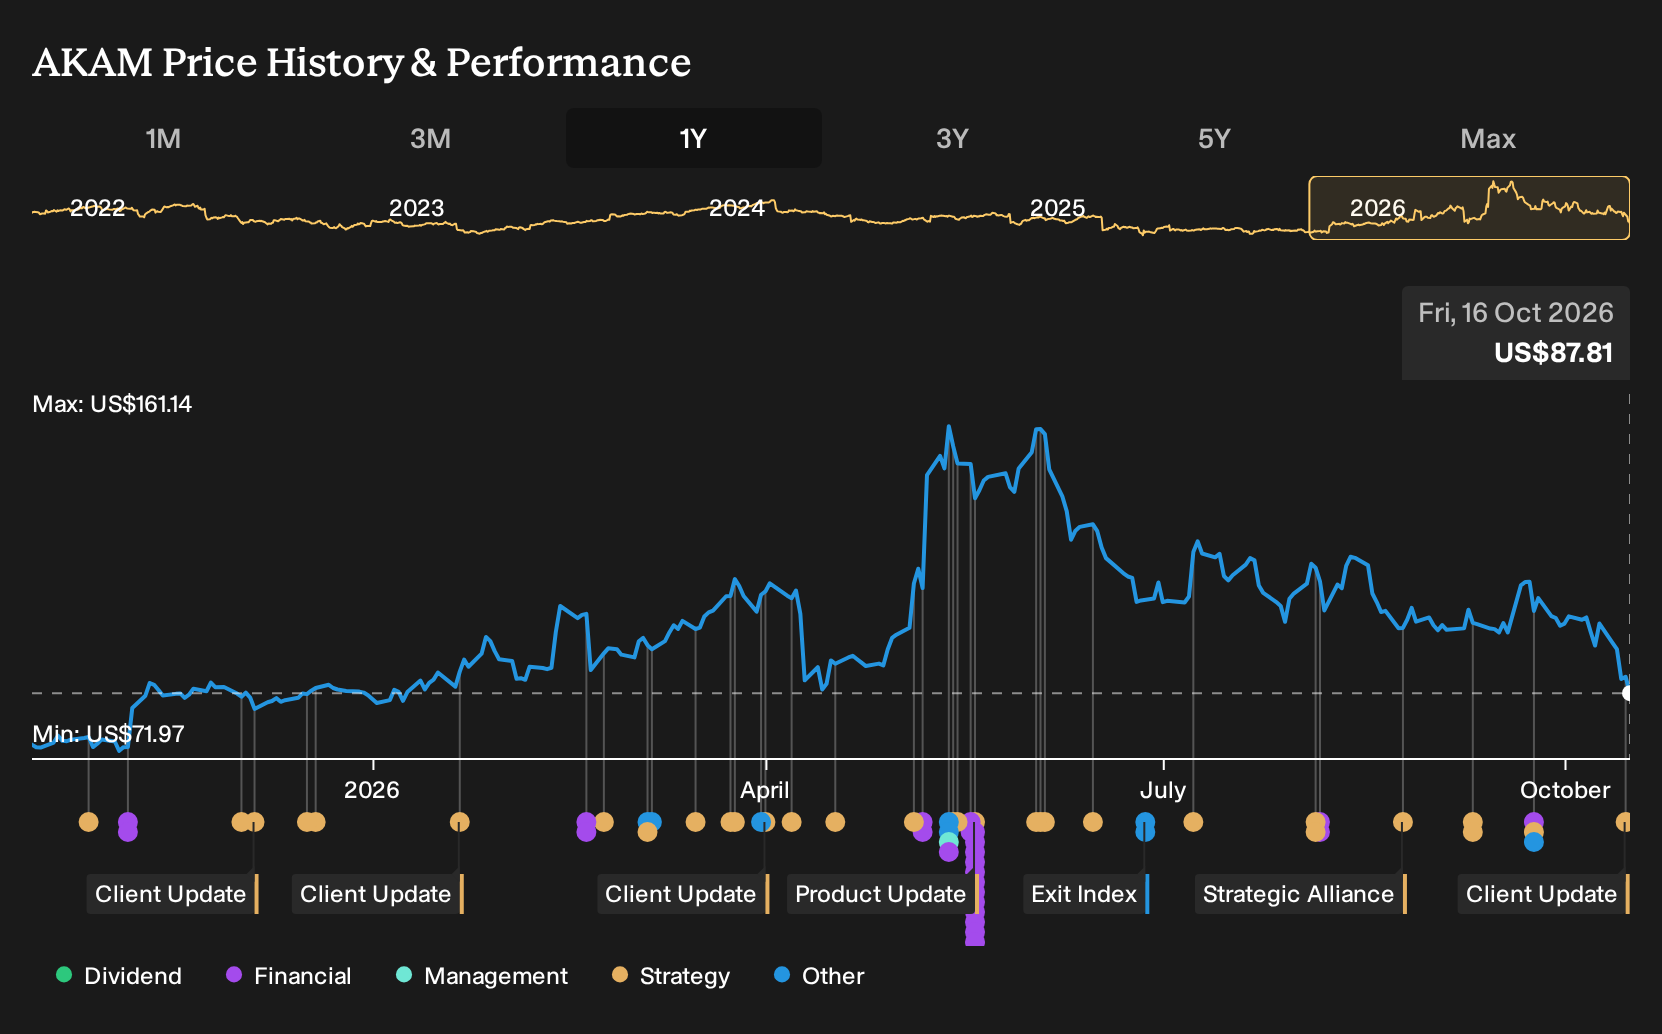
Uncover why Akamai Technologies' fair value indicates an 81% potential upside to its current price, a discount that could narrow quickly as sentiment shifts.
Exploring Other Perspectives
Some of the most optimistic analysts frame the real catalyst as Akamai Technologies hitting those higher margin targets, not just filling data centers. Before this news, the bullish camp was already penciling in about US$7.9b of 2029 revenue and US$1.1b of earnings, far above consensus. This shows how wide opinion can run and why it is worth comparing several viewpoints.
Explore 3 other Akamai Technologies fair value estimates, including one that suggests as much as 81% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Akamai Technologies research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Akamai Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Akamai Technologies' overall financial health at a glance.
Looking for more investment ideas beyond Akamai Technologies?
If Akamai Technologies has sharpened your interest in AI infrastructure and cloud heavy workloads, it can be useful to line it up against other opportunities with different risk and return profiles.
- For investors who want potential value with quality fundamentals, scan a curated set of 20 high quality undiscovered gems that may not yet be widely followed.
- If capital preservation sits higher on your priority list, check a focused group of 32 resilient stocks with low risk scores that screen well on resilience metrics.
- When balance sheet strength is your starting filter, sort through a targeted list of solid balance sheet and fundamentals (25 results) and compare leverage and liquidity against what you see at Akamai Technologies.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com