
- PRICING
- LIVE QUOTES
- LEARN
- HELP


EN
3 Stocks That Could Benefit If Russian Tariff Risks Ease
When a threatened 500% tariff on Russian products is suddenly taken off the table, the mood across energy and fuel hungry industries can flip from fear to curiosity. Instead of bracing for a shock, you are watching a market where trade routes, shipping, refineries and airlines might catch a break on costs and supply risks. This piece walks through 3 stocks that screens suggest could be positively exposed to that shift, and why each one may warrant a closer look right now.
The three stocks below are only a starting sample from this tariff-sensitive corner of global energy and fuel-intensive industries, and the full screen surfaced 7 more companies with equally detailed stories that are not covered here. If you want to identify and analyze your own highest-conviction ideas off the same criteria, head straight to the Global Energy and Fuel-Intensive Industries screener.
Packaging Corporation of America (PKG)
Packaging Corporation of America plugs directly into this screener’s energy heavy theme because running paper mills and box plants relies on power, fuel and chemicals, and that exposure sits behind why its containerboard and paper economics matter so much right now.
Packaging Corporation of America generates most of its revenue from packaging, with about US$8.8b coming from containerboard and corrugated products and around US$633 million from paper, on a total market value of roughly US$20.6b.
"Packaging Corporation of America is operating in a containerboard market that management describes as very tight. Mills are expected to run full through 2026, and customers have limited ability to source extra tons. This dynamic can support pricing power and revenue resilience."
The real swing factor for investors is what happens if one persistent cost pressure moves in a different direction than pricing power.
If that cost pressure does start to decouple, the full narrative for Packaging Corporation of America explains how pricing power, input volatility and capital plans could reshape Packaging Corporation of America’s earnings mix.

Myers Industries (MYE)
Myers Industries looks interesting for an energy and fuel intensive screen because it turns power hungry plastic, metal, and rubber processing into essential containers, fuel cans, tanks, and industrial products for North American and European customers, while carrying a market value of roughly US$1.2b.
Myers Industries provides focused exposure to industrial and infrastructure plastics that depends heavily on resin costs and cross border demand, so any relief on tariffs or fuel prices can matter more than headlines suggest.
"Record composite matting backlogs, consecutive quarterly sales records in infrastructure, and strong demand tied to utility and data center projects point to further uptake of Signature ground protection products. This can support continued revenue growth and earnings contribution from this segment."
What really decides how that story turns out is how one stubborn cost line behaves relative to the pricing power Myers Industries is trying to build.
If that cost swing is what you are watching, the full narrative for Myers Industries maps how resin, pricing and infrastructure demand could be quietly reshaping Myers Industries’ earnings mix.
Coeur Mining (CDE)
Coeur Mining brings an energy hungry twist to this screen because running gold and silver mines in the United States, Canada and Mexico means heavy diesel use and power consumption. Steadier fuel costs can feed straight through into how its multi site portfolio converts metal output into profit.
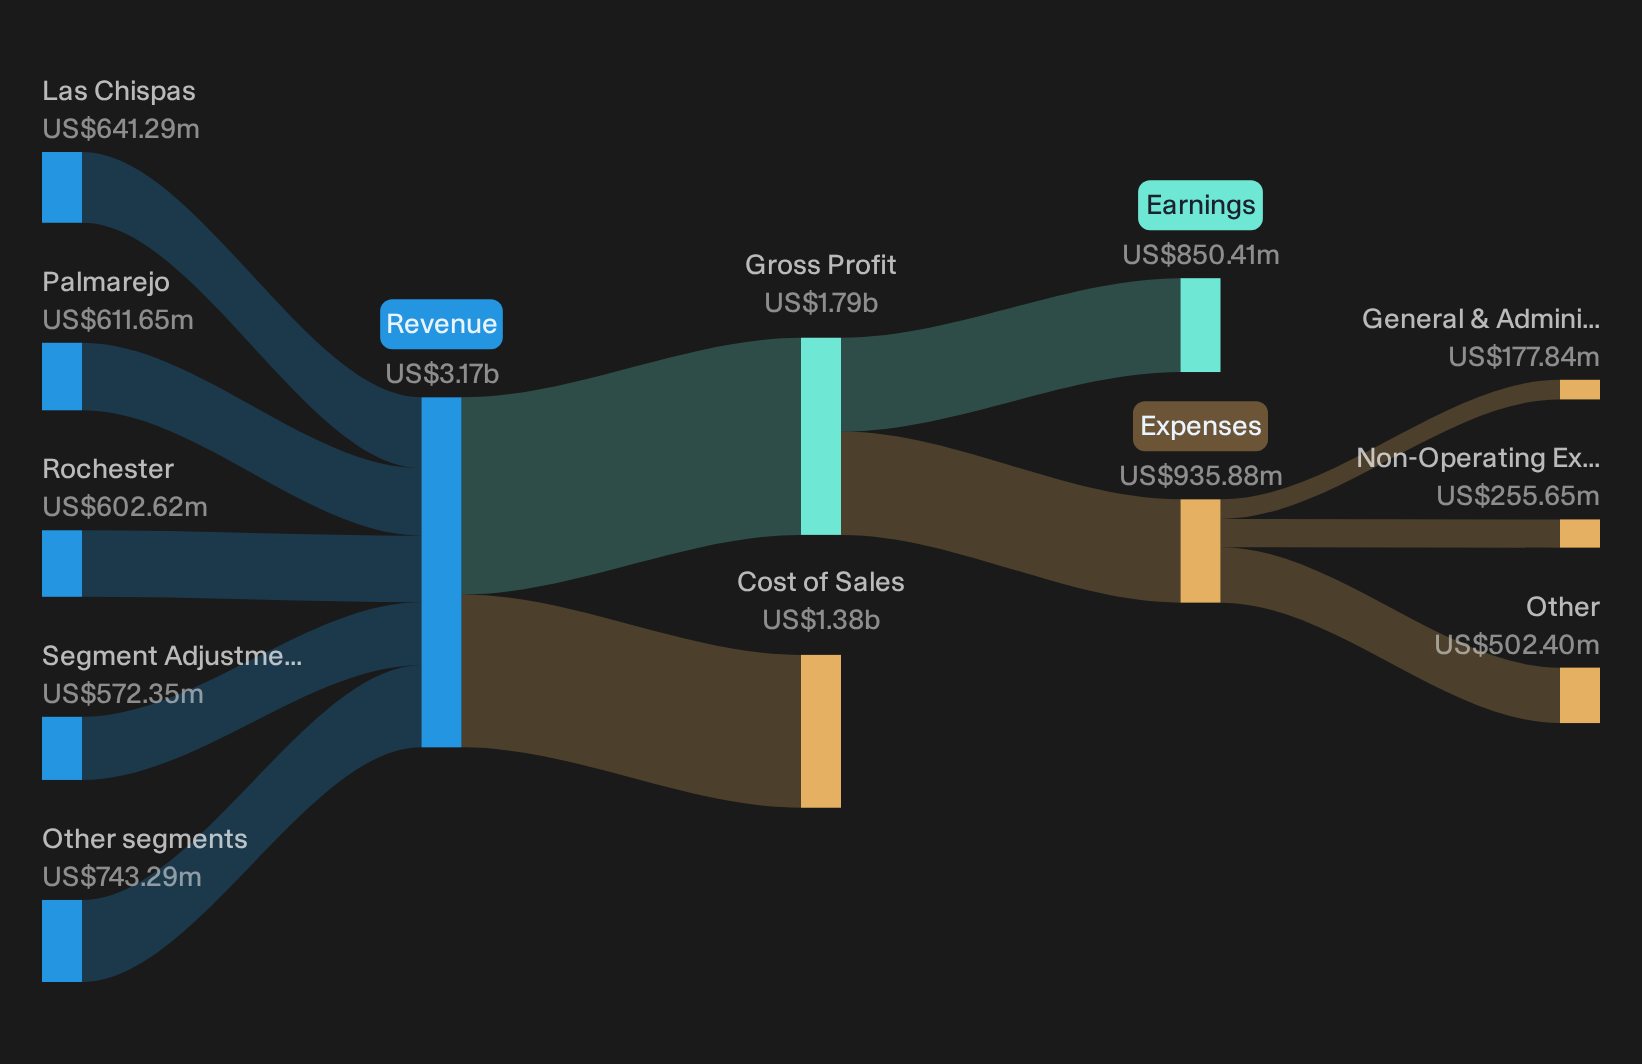
Coeur Mining generates about US$612 million from Palmarejo, US$603 million from Rochester, US$641 million from Las Chispas, US$419 million from Kensington and US$324 million from Wharf, and the stock carries a market value of roughly US$15.8b.
The successful ramp-up and integration of the Rochester expansion and Las Chispas asset are driving significant increases in silver and gold production, positioning Coeur for robust revenue and earnings growth in the near to medium term.
What happens if a single cost line tied directly to that power hungry mining footprint shifts in the opposite direction to revenue momentum?
If you are tracking the fuel-driven cost line, read the full narrative for Coeur Mining to see how Coeur Mining’s expansion, costs and risk profile could be decoupling.
Seeking Alternatives Before The Crowd?
Fresh ideas move fast. Breakout themes, dropping risk scores, and under the radar for now opportunities rarely stay quiet for long. Scan what is flying before it gets fully caught and act now.
- Spot resilient compounders early by reviewing the 32 resilient stocks with low risk scores that have been quietly building momentum while most attention stays glued to headline tickers.
- Ride potential infrastructure and electrification trends by scanning the 41 power grid technology and infrastructure stocks that could benefit if grid upgrades keep pulling capital and contracts their way.
- Get ahead of the next automation wave by tracking the curated 92 robotics and automation stocks that are already turning robotics demand into real operating scale.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com